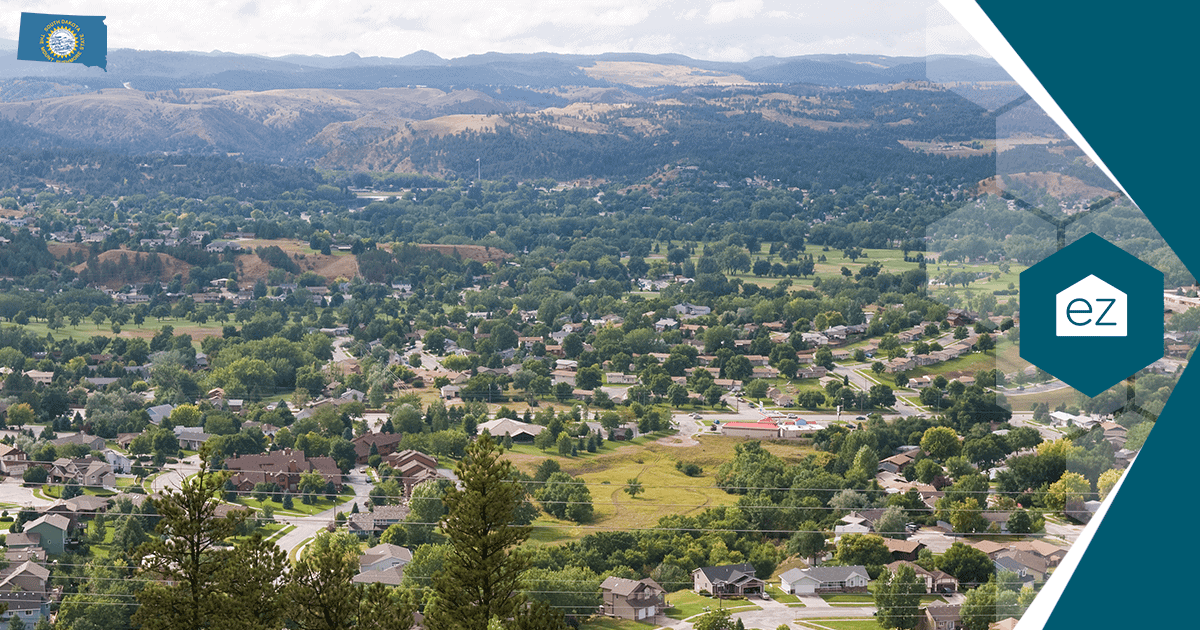08.27.2026

Wisconsin Real Estate Leads: Reach Buyers and Sellers Earlier

Wisconsin turns over roughly 4% of its owner-occupied homes in a given year. That ratio governs everything about Wisconsin real estate leads. The owner who signs a listing agreement next year already owns a Wisconsin home this year, has raised no hand, and is invisible to every lead source on the market. Add 72 counties that build, price, and turn over at rates with nothing to do with each other, and one statewide playbook becomes a guess across most of the state.

Wisconsin closes tens of thousands of homes every year, with an owner base well over a million households behind them. What most agents lack is arrival time. They meet these people in the last few weeks of a process that ran for years.

Where Wisconsin builds homes has little to do with where people currently live

Wisconsin’s building activity does not track its population, and the gap is not a rounding error. Milwaukee County holds more residents than any other county in the state, 926,331 of them, and it authorizes fewer new single-family homes in a year than several counties a fraction of its size. In 2025 it issued 199 single-family permits, down from 430 in 2024. Dane County, with roughly 62% of Milwaukee County’s population, issued 1,398 that year, up 23.0%.

Other counties widen the gap rather than close it. Waukesha County issued 1,003 permits in 2025, up 35.0%. St. Croix County, home to 96,033 people, issued 536, up 20.7%, which is more than two and a half times Milwaukee County’s total on roughly a tenth of the population. Those counts come from the Wisconsin Builders Association’s county report, built from the filings municipalities send the Wisconsin Department of Safety and Professional Services under 2015 Wisconsin Act 211. The ordering is not a one-year fluke either; it has held across the last decade.

Lead vendors sell the same product into all 72 counties, and most agents run the playbook they were trained on regardless of which county they work. A pricing instinct that is right in Waukesha County is off by a factor of two and a half in Clark County. That is how an agent works harder every year and watches the pipeline sit flat.
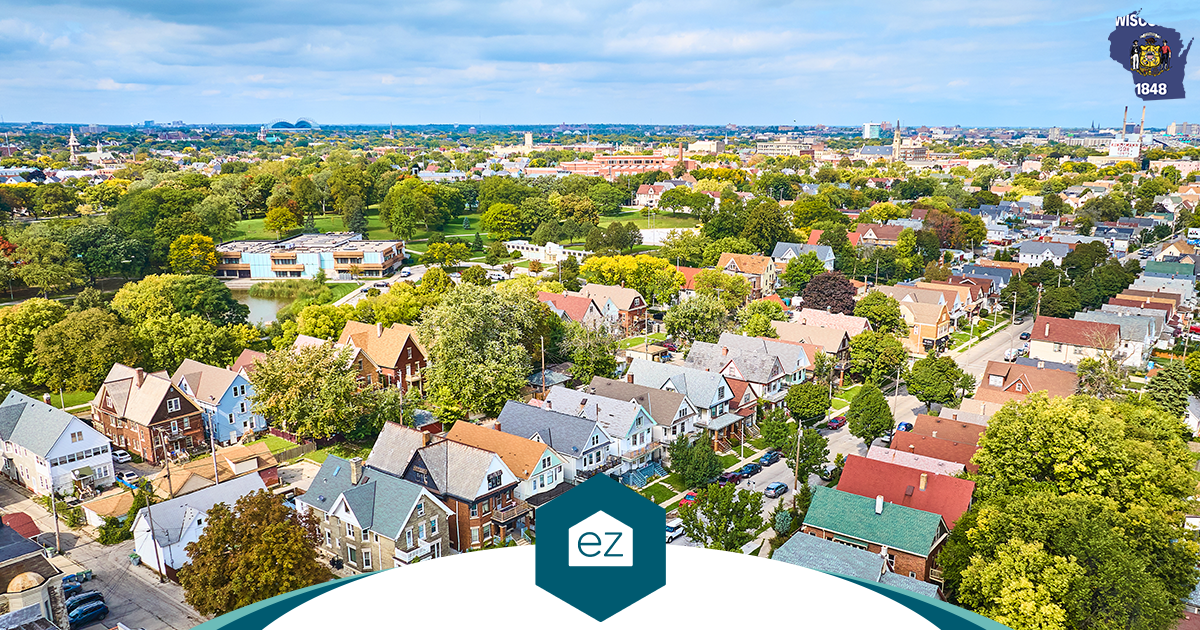
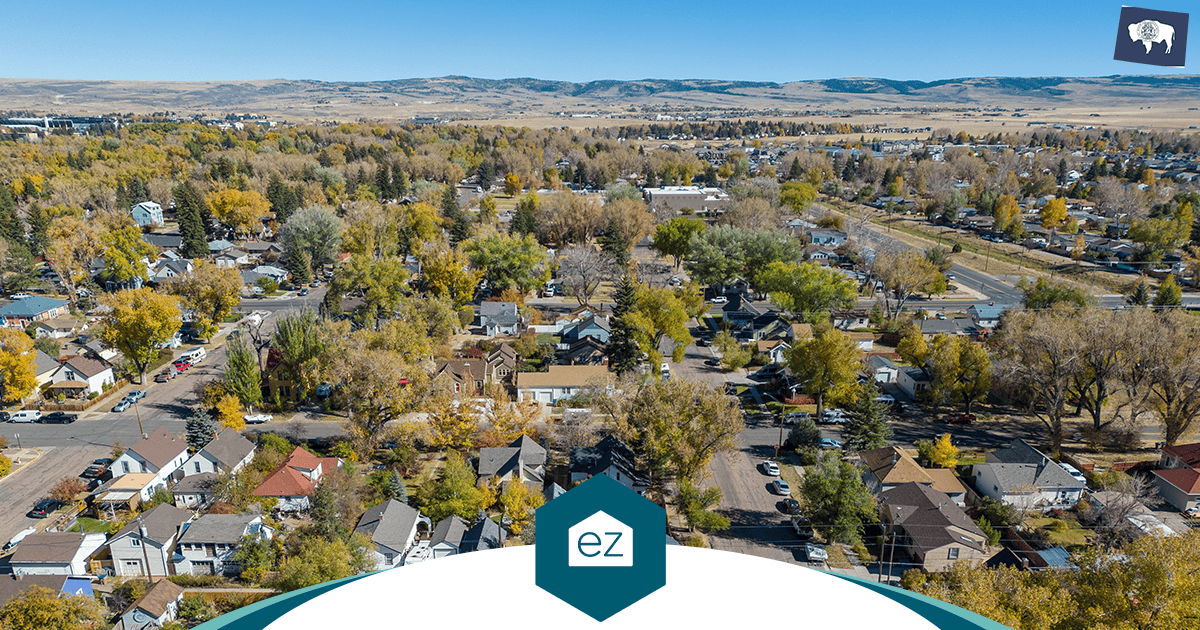
Aerial view of a Milwaukee County residential neighborhood with tree-lined streets and the downtown skyline beyond, the market behind Wisconsin real estate leads in the state's largest county
Milwaukee County holds more residents than any Wisconsin county and permits fewer new single-family homes than several smaller ones.

Wisconsin keeps producing home sales, even in years when few homes are for sale

Wisconsin has closed tens of thousands of existing homes every year for two decades. The recent direction is up. Sales rose in 2024 and again in 2025, finishing that year at 69,132, a 2.0% gain over 2024’s 67,771 and a second consecutive year of growth, according to the Wisconsin Realtors Association. The statewide median finished 2025 at $325,000, up 4.8% from $310,000, which Tom Larson, the association’s president and chief executive, noted in January 2026 was the slowest annual price appreciation Wisconsin had recorded since 2017.

Every region grew. Sales rose 6.7% in the North, 3.7% in the Northeast, 3.0% in the West, 1.6% in the South Central, 0.4% in the Central, and 0.2% in the Southeast, and median prices rose in all six. Amy Curler, the association’s 2026 board chair, said that January: “It’s good to see a second straight year of improved sales in the Wisconsin housing market.”

The longer series matters more than any single year of it. Wisconsin ran above 82,000 closings in both 2018 and 2019, then climbed to roughly 89,000 in 2020 and near 90,000 in 2021, years when the Wisconsin Housing Affordability Index sat above 200. Volume gave back 14.6% in 2022 and another 17.5% in 2023 as mortgage rates climbed, and it has grown in both years since. That is a rate cycle working itself out. Nothing across the decade shows demand leaving the state.

One distinction decides whether an agent reads any of it correctly. Months of supply, which stood at 2.9 statewide in December 2025 against 3.0 a year earlier, counts what is available for sale on one particular day. Closed sales measure deals completed across a whole year. An agent who treats a short list of active listings as proof the business has gone will be wrong about the year.

Volume also concentrates. Across the twelve months ending December 2025, Wisconsin recorded 26,103 sales between $200,000 and $349,999, 17,087 between $350,000 and $499,999, 13,323 at $500,000 and above, 9,512 between $125,000 and $199,999, and 3,107 under $125,000. Homes sold in an average of 76 days that December, against 78 a year earlier. Any farm built without knowing which of those bands a county actually lives in is a farm built on a guess.

Wisconsin has no shortage of people making moves. Most agents are simply nowhere near those closings until the last few weeks of each one.

Roughly four in five Wisconsin buyers are also sellers, so one-sided prospecting leaves most of the market untouched

Most agents split prospecting in half and lose the larger side. The listing half gets mailers, door knocking, and expired calls. The buyer half gets bought leads. That is two campaigns and two budgets aimed at what is usually one person making one move.

The sizing settles it. Nationally, first-time buyers made up 21% of purchases. That figure comes from the 2025 Profile of Home Buyers and Sellers, a National Association of Realtors survey covering July 2024 through June 2025. No reading has been lower since the association started tracking the share in 1981, and the typical first-time buyer in that survey was 40 years old, the oldest the series has recorded. David Clark, economist for the Wisconsin Realtors Association, framed the shift for a Wisconsin audience in June 2026: “It hasn’t been unusual in previous years to find first-time buyers accounting for more than 40 percent of home purchases in a given year.”

Run that forward. If about one buyer in five owns no home yet, about four in five already own one. Those people are buyers and sellers inside a single move, and nearly all of them begin on the buy side, months or years before any listing agreement exists. Whoever proves useful during that stretch earns the listing later by default, because nobody else was there.

Wisconsin makes the math concrete. The Census Bureau’s 2024 American Community Survey puts 67.8% of the state’s occupied homes in owner hands, above the national 65.2%. Against an owner base well over a million households, 69,132 closings works out to roughly 4% turnover in a year. The owner who signs a listing agreement in any given year already owned a Wisconsin home the year before, and the year before that. Demand is stacked behind them too. Forward Analytics reported in May 2026 that about 13% of Wisconsin residents aged 25 to 34 live with a parent or in-law. None of that appears in a lead feed.

That leaves Wisconsin with three groups rather than two. First-time buyers own no home yet and need affordability and education more than equity math. The dual majority is trading up, down, or across, and needs the equity in the home they are leaving and the timing between the two sides handled as one transaction. Seller-only owners are the smallest of the three: an estate settling a house, a landlord getting out, an owner moving in with a son or daughter.

ez Home Search is built for the person who is both. It watches what someone actually does, a second valuation on the same address, an old search reopened, an alert clicked the morning it lands, and it works whichever side of the move is live instead of guessing. Home-value tracking keeps the partner in front of an owner through all the years when nothing is listed, which is how a buyer served in 2026 becomes a listing in 2029.

If that is the half of the market you have been leaving alone, the first thing worth checking is whether your Wisconsin county is still open.

What is actually moving Wisconsin households between homes

No single story explains Wisconsin’s transaction volume, and an agent who bets a year of prospecting on one will be wrong across most of the state’s 72 counties. At least nine forces are in play, and several of them pull against each other.

Money loosened, slowly. The 30-year fixed rate ran 6.72% in December 2024 and 6.19% in December 2025 (Freddie Mac, via the Wisconsin Realtors Association), and the Wisconsin Housing Affordability Index rose 1.5% over that span to 134. Set that against 2020 and 2021, when the index sat above 200, and the shape is clear. The market got much harder, then started to ease. Every tenth of a point decides whether an owner holding a 3% mortgage is willing to trade it.

Inventory has climbed since late 2023. The Wisconsin Realtors Association began tracking annual inventory change in January 2016, and total inventory fell in nearly every month through September 2023 before reversing. Growth averaged 14.8% across 2024 and 9.7% across the first ten months of 2025. Months of supply averaged 2.5 in 2022, 3.0 in 2023, 3.5 in 2024, and 3.9 across the first ten months of 2025. That is a multi-year recovery.

Wisconsin is gaining residents from other states, which it had not done for two decades. Net domestic migration ran 5,828 in 2024 and 6,984 in 2025, per Census Bureau estimates, a fourth consecutive positive year. Mark Sommerhauser of the Wisconsin Policy Forum put it this way in March 2026: “These aren’t huge numbers of people, but it is a shift.” Both directions matter to a book of business. A family leaving is a listing and a referral fee; a family arriving is a buyer who has not chosen anyone yet.

International arrivals fell sharply, which slowed overall growth. Arrivals from abroad dropped from 19,395 in 2024 to 7,260 in 2025, and statewide population growth slowed from 26,818 to 15,619. Milwaukee County’s international arrivals went from 5,688 to 1,973, and Dane County’s from 4,404 to 2,049. Every state moved the same direction over that period.

Manufacturing is shrinking through retirement. Wisconsin’s manufacturing workforce went from 461,100 in January 2025 to 451,600 in January 2026, a loss of roughly 9,500, per Bureau of Labor Statistics figures compiled by the Federal Reserve Bank of St. Louis. Industry leaders attribute most of it to workers aging out rather than to layoffs. A retirement turns into a housing decision far more often than a layoff does.

Health care and hospitality absorbed the shift. Health care employment reached a new high of 324,200 in 2025, and leisure and hospitality finished the year at 285,200 after recovering nearly all of the roughly 50% drop it took during the pandemic, per the Wisconsin Department of Workforce Development.

Data centers landed in the southeast. Microsoft completed its first Mount Pleasant facility in Racine County in May 2026, more than a million square feet, with roughly 550 full-time staff on site and about 800 expected once a second building runs. That first build phase employed nearly 10,000 construction workers across about two years. Meta broke ground in Beaver Dam in Dodge County in November 2025, and Vantage Data Centers is developing a campus at Port Washington in Ozaukee County.

Tourism set a fourth straight record. Wisconsin logged more than 117 million visits and $27 billion in total economic impact in 2025, up $1.2 billion from 2024, per the Department of Tourism. Sauk County passed $2 billion, Brown County set a record at $1.5 billion, and Door County rose 5%.

The working-age population is contracting. Wisconsinites aged 25 to 64 declined by more than 25,000 between 2020 and 2024, per Forward Analytics in May 2026. That pulls demand toward move-up, downsize, and second-home activity and away from first-time household formation.

Nine forces run across six regions and 72 counties. The agent who knows which three are live in their own county holds an advantage no lead vendor sells.
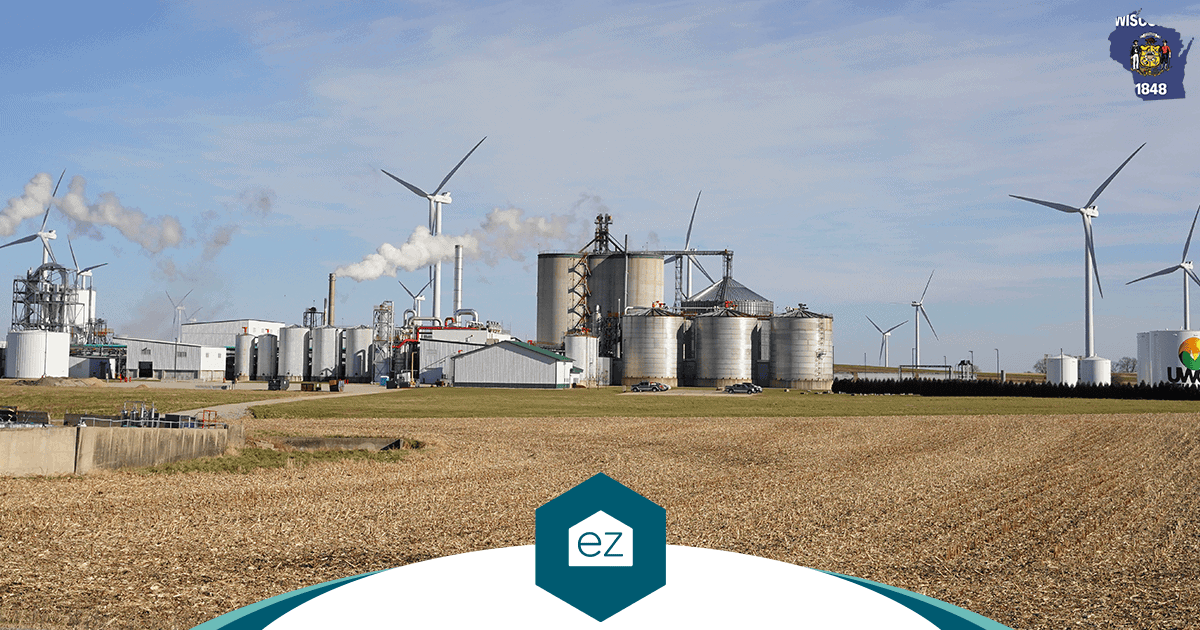
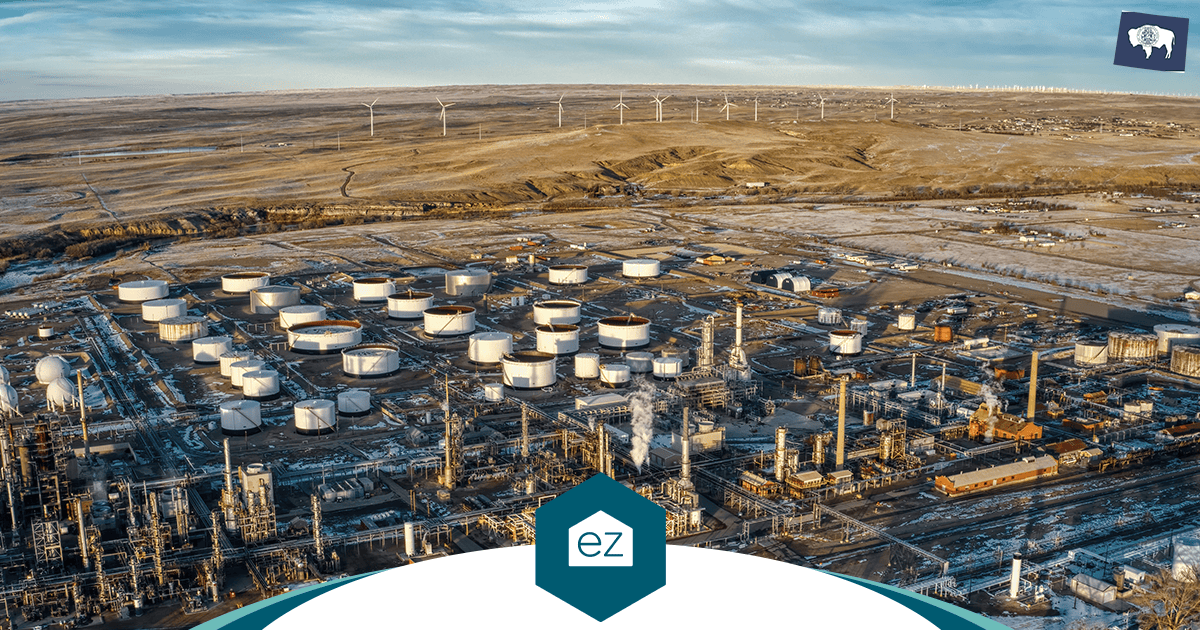
A Wisconsin manufacturing plant with wind turbines and storage tanks set against farmland, part of the employment picture moving Wisconsin households
Wisconsin’s manufacturing workforce fell from 461,100 in January 2025 to 451,600 in January 2026, mostly through retirements.

Wisconsin’s six market regions run on different engines

The Wisconsin Realtors Association divides the state into six regions, and in 2025 the spread between them was wide enough that a lead plan built for one is close to useless in another. The Southeast closed 24,001 homes and grew 0.2%. The North closed 6,793 and grew 6.7%. Median prices ran from $255,000 in the Central region to $380,000 in the South Central. Those regions shared the same year, the same state, and the same mortgage rates.

Region2025 salesSales change2025 medianMedian changeWhat set it apart in 2025
Southeast24,001+0.2%$340,000+6.3%Largest region by volume and the least affordable; the Milwaukee metro’s home price to income ratio ran about 5.2, the highest in the Midwest
South Central13,807+1.6%$380,000+5.6%Highest median in the state; the Madison metro averaged 61.2 housing starts per 1,000 households from 2015 to 2025
Northeast13,318+3.7%$305,000+7.0%Fastest median price growth of the six; Brown County tourism reached a record $1.5 billion
North6,793+6.7%$285,000+5.6%Fastest sales growth in the state, tracking second-home demand across the Upper Midwest lake country
West6,475+3.0%$307,000+2.0%St. Croix County sales rose 10.5% on a $389,900 median, along the Twin Cities commuting edge
Central4,738+0.4%$255,000+4.1%Most affordable region and the flattest sales year

Sources: Wisconsin Realtors Association, December 2025 report; Moody’s Analytics data via a New York Times analysis reported by Wisconsin Public Radio, May 2026; Wisconsin Department of Tourism, June 2026.

Read down the sales column and the point lands. Dane County by itself closed 6,635 homes in 2025, more than the entire Central region. Milwaukee County closed 9,449, more than the North region and more than the West. Yet the North grew faster in 2025 than either the Southeast or the South Central, on the back of counties an agent in Waukesha has probably never worked: Sawyer up 18.6%, Polk up 16.5%, Burnett up 12.3%, Oneida up 11.4%, Bayfield up 10.3%.

Supply behaves differently too. In December 2025 Wisconsin’s metropolitan counties held 2.6 months of inventory, micropolitan counties 3.2, and rural counties 3.9. An agent in Rhinelander and an agent in Brookfield are pricing into two different levels of competition on the same day.

Timing splits as well, and this one is measurable. David Clark, the professor emeritus of economics at Marquette University who consults for the association, applied seasonal adjustment to Wisconsin prices across January 2005 through December 2025. Homes closing between December and February sold at roughly a 5.9% discount. Homes closing in June, July, and August carried roughly a 6.4% premium. That is a 21-year pattern rather than a one-year quirk, and it is worth a real conversation with a seller weighing a February listing against an April one.

The building gap between Milwaukee, Dane and Waukesha counties changes who your next client is

Dane County holds about 62% of Milwaukee County’s population and consistently permits several times as many new single-family homes. The gap is a decade old and it is wide. Across 2015 to 2025 the Madison metro averaged 61.2 annual housing starts per 1,000 households while the Milwaukee metro averaged 17.9, per Moody’s Analytics figures analyzed by the New York Times and reported by Wisconsin Public Radio in May 2026. The 2025 county counts came in at 1,398 against 199.

Kurt Paulsen, professor of urban planning at the University of Wisconsin-Madison, told WPR that production in both regions sits well below its 1990s and early 2000s level, and that the Milwaukee metro still carries a high shortfall in housing production. Waukesha County sits between the two, with 1,003 permits in 2025.

The divergence has a long tail. In 2018, Dane County and the city of Madison passed Milwaukee County and the city of Milwaukee in total equalized property value for the first time in state history. Over the three decades leading to that crossover, Dane County’s equalized value climbed 526% against Milwaukee County’s 178%, per the Wisconsin Policy Forum in August 2018.

Scarcity carries its own price effect. Median home values in the city of Milwaukee rose 138% between 2016 and 2026, second among large US cities, while Wisconsin ranked 13th among states for home-price growth over the decade, per a 2026 Construction Coverage study. Report author Jonathan Jones noted that Milwaukee started from a relatively low price point and that the scale of the appreciation points to sustained demand and growing competitiveness over time.

For a working agent the consequence is concrete. In Dane and Waukesha counties, a real share of the transactions three years out has not been framed yet, so builder relationships and new-construction search behavior belong in the pipeline. In Milwaukee County, nearly every transaction three years out is an existing home whose owner is living in it today. There the owner database is the pipeline, and staying in front of those owners between moves is the whole job.

The same question applies down the list of Wisconsin’s largest counties, each with its own build rate, price level, and principal city.

RankCountyPopulationPrincipal city
1Milwaukee926,331Milwaukee
2Dane572,674Madison
3Waukesha411,762Waukesha
4Brown270,892Green Bay
5Racine197,532Racine
6Outagamie192,826Appleton
7Winnebago171,769Oshkosh
8Kenosha168,438Kenosha
9Rock164,350Janesville
10Marathon138,403Wausau

Population source: US Census Bureau, American Community Survey 5-Year Estimates, 2024.

Brown County permitted 679 single-family homes in 2025 and Outagamie 453, the two Fox Valley and Green Bay engines. Racine County permitted 296, down 20.9% even as data-center construction moved into Mount Pleasant. Rock County permitted 269 and Winnebago 285. No two of those counties are handing an agent the same year.
The Wisconsin State Capitol lit at night in Madison, the center of Dane County's housing growth
Dane County permitted 1,398 single-family homes in 2025, more than any other Wisconsin county.

Wisconsin counties outside the big metros carry more opportunity than most brokers know

Close to half of Wisconsin’s home sales happen outside the Milwaukee and Madison regions. The Northeast, North, West, and Central regions together accounted for about 45% of the statewide total in 2025, or 31,324 homes. That is nearly half the market, spread across the Fox Valley, the Northwoods, the Driftless Area, the Coulee Region, the Chippewa Valley, the Door County peninsula, the Kettle Moraine, and the Lake Superior shore.

The North region grew fastest in 2025, and the growth sat in counties most metro agents have never worked. Sawyer County sales rose 18.6% on a $340,000 median. Polk County rose 16.5%, Burnett County 12.3%, Oneida County 11.4% on a $375,000 median, and Bayfield County 10.3%. Door County permitted 274 single-family homes in 2025, up 66.1% from 165, in a county that closed 763 existing-home sales the same year.

Property values rose fastest in the far north of the state. Wisconsin’s total equalized value rose 8% in 2025, and the two largest county increases were Florence at 17.84% and Iron at 17.77%, per the Wisconsin Department of Revenue in August 2025. Florence County has 4,646 residents and Iron County has 6,210. Two of the smallest counties in Wisconsin saw their total property value climb at more than twice the statewide rate.

Buyers purchasing second homes account for much of that demand. Nationally, mortgaged second-home purchases fell roughly 66% from their 2021 peak, from 257,547 to 88,158 in 2025, while new construction in second-home areas held at an all-time high, which points to buyers paying cash and never appearing in mortgage data at all. That analysis of Home Mortgage Disclosure Act filings and National Association of Home Builders construction data, published in July 2026, names the Upper Midwest lake country anchored by Vilas County among the country’s concentrated second-home geographies, with Chicago the primary feeder market into the Wisconsin Northwoods.

County2025 sales2025 medianCommunities
Door763$447,000Sturgeon Bay, Sister Bay, Fish Creek, Egg Harbor
Vilas534$425,500Eagle River, Boulder Junction, St. Germain, Land O’ Lakes
Oneida723$375,000Rhinelander, Minocqua, Three Lakes, Lake Tomahawk
Sauk825$322,500Baraboo, Reedsburg, Spring Green, Sauk City
St. Croix919$389,900Hudson, New Richmond, Somerset, Roberts
Walworth1,559$389,900Elkhorn, Lake Geneva, Delavan, Whitewater
Barron874$280,000Rice Lake, Barron, Cumberland, Chetek
Bayfield279$328,000Washburn, Bayfield, Cable, Iron River
Vernon260$278,000Viroqua, Westby, La Farge, Hillsboro
Waupaca567$262,500Waupaca, New London, Clintonville, Weyauwega

Source: Wisconsin Realtors Association, December 2025 report.

The western edge runs on a different clock again. St. Croix County permitted 536 single-family homes in 2025, third-most of any Wisconsin county, on a population of 96,033, with Pierce County adding 180. Hudson, River Falls, New Richmond, Prescott, and Ellsworth are absorbing households whose paychecks come from Minnesota. Down the Mississippi, La Crosse County closed 1,333 homes and Eau Claire County 1,219, with Onalaska, Holmen, Chippewa Falls, and Menomonie carrying the surrounding demand. Hayward and Minocqua run on summers.

Every one of those markets is somebody’s whole business. None of them responds to a Milwaukee playbook.
Waterfront homes and boat docks along a Wisconsin lake shore lined with autumn trees, the second-home market behind the North region's growth
The North region led Wisconsin in 2025 sales growth at 6.7%, with Sawyer County up 18.6%.

The real data on remote and hybrid work fundamentally unlocks Wisconsin’s smaller counties

Wisconsin’s share of workers who primarily work from home more than doubled from 2019 to 2024, and it has not gone back. The Census Bureau’s American Community Survey one-year estimates put 5.10% of Wisconsin workers primarily working from home in 2019 and 11.81% in 2024, a gain of 6.71 percentage points that ranks the state 28th nationally. The national figures moved the same direction over the same years, from 5.72% to 13.32%.

Plenty of agents have written this off, because the headlines measure against spring 2020 rather than against 2019. Measured against 2019, the shift holds. A 2026 study in the Bureau of Labor Statistics’ Monthly Labor Review followed a single cohort across four decades of working life. It found telework adoption rising incrementally long before 2020, intermediate levels of telework becoming common around 2018, and the share of workers who reported no telework, or only minimal telework hours, never returning to pre-pandemic levels. BLS reads that as “suggesting a structural shift toward more widespread telework adoption.” Employers say much the same about their own plans. When the Census Bureau surveyed roughly 150,000 firms for its Business Trends and Outlook Survey, those firms projected remote work five years ahead at close to the level they were already running.

For Wisconsin, that lands in specific places. A household that no longer commutes daily can buy in Vilas, Oneida, Sawyer, or Bayfield County and keep the same paycheck. The same holds in Vernon, Crawford, and Richland counties in the Driftless, in Marathon, Portage, and Wood counties through the middle of the state, and across the Chippewa Valley. St. Croix and Pierce counties have run on this logic for years with Minnesota paychecks. The pattern shows up in the sales column too: the North region grew 6.7% in 2025 against the Southeast’s 0.2%, and Wisconsin has now posted four straight years of positive net domestic migration.

It also changes what a buyer asks for at a showing. They want a dedicated room with a door that closes, and enough space that two working adults are not sharing a kitchen table. Many ask about a detached structure, an accessory dwelling unit, or anything with its own entrance, which in a lot of Wisconsin counties already exists as a heated garage loft or a converted outbuilding. Square footage matters more to them than walkability. And they want broadband that holds a video call, which an agent should be able to answer for a specific address rather than for a township.

Wisconsin ranks 28th in the country on this measure, which means that buyer is still arriving in most of its counties rather than already competing there. That is an opening.

Rising Wisconsin property tax bills are a listing conversation most agents skip

A Wisconsin homeowner with no plans to move still opens the December tax bill, and that is a conversation an agent can own without paying anyone for it. Gross property taxes levied in 2024 for collection in 2025 came to $13.65 billion statewide, against $10.45 billion in state income tax collections and $7.83 billion in sales tax collections in fiscal 2025, per the Wisconsin Department of Revenue. Property tax is the largest tax most Wisconsin families pay.

It is also climbing. The Wisconsin Policy Forum reported in December 2025 that gross statewide levies were on pace to rise roughly 5% in 2026, after 4.4% the year before, the largest increase in 18 years. Gross K-12 school levies rose 7.8% on December bills, adding about $476.1 million to reach roughly $6.58 billion, the biggest jump since 1992. County levies rose 2.9% to about $2.63 billion.

The part most owners get wrong is the rate. Wisconsin’s average gross property tax rate fell from 2.3067% in 2000 to 1.5029% in 2024. Bills rose anyway, because the base underneath them more than tripled over those years, from $286.3 billion in total statewide equalized value in 2000 to $982.8 billion as of January 1, 2025. Of the $75.4 billion added in the most recent year, $60.5 billion came from market value increases and $15.2 billion from new construction. The residential class alone rose $57.1 billion to $724.4 billion.

The machinery is unusually local, which is why a statewide answer never satisfies anybody. The Wisconsin Department of Revenue counted 3,202 units levying property tax out of 3,404 total in its October 2025 property tax overview, covering 421 school districts, 16 technical college districts, 72 counties, 1,913 municipalities, and 537 special districts. Most of the state pays in two installments, due January 31 and July 31. Some municipalities allow three to seven, and in the City of Milwaukee an owner can pay in as many as ten. The same report puts the Lottery and Gaming Credit at an average of $241 per primary residence in the 2024-25 tax year and the First Dollar Credit at $64.

An agent who can walk an owner through their own number is the agent that owner calls when the move finally arrives. That is part of what ez Home Search hands a county exclusivity partner. Property taxes can be looked up and compared by state, county, city, and ZIP. An automated valuation model (AVM) tracks the home’s value month to month, so an owner can see what their assessment is being set against. The Single Local Expert behind the experience turns both into a comparative market analysis, plus a straight answer on whether the tax picture is holding the price down, which it can, because a buyer has to carry that bill on top of the mortgage and the insurance.

Every one of those conversations happens years before a listing exists. That is the point of them. If you would rather be having them in your county than watching someone else have them, check whether your Wisconsin county is still open.

The eight places Wisconsin real estate leads come from, and where each one runs out

Each of the eight works, which is exactly why picking among them by feel goes wrong so often.

Start with the denominator. The Wisconsin Realtors Association represented more than 15,000 members statewide as of January 2026, and Wisconsin closed 69,132 homes in 2025. Spread evenly, that comes to fewer than five closings per member for the year, and it is never spread evenly.

Then look at how people choose. National Association of Realtors research on buyers and sellers puts the numbers plainly: 81% of sellers talk to a single agent before they pick one, and 77% of repeat buyers interview exactly one. Reputation decides it for 35% of sellers, and referral brings buyers and sellers to an agent more often than any other source. Most Wisconsin listings are never won in a competition. They are won before one starts, by whoever was already the name in that household’s head.

The standard menu runs like this.

Shared portal leads deliver real volume and the fastest way into a new market. The same contact also goes to several agents at once, the consumer chose none of them, and the race is to dial first. An agent buying those is buying a starting gun. The relationship is still ahead of them.

A self-built IDX site creates a genuinely owned asset, and the instinct behind it is correct. It is also slow to rank, expensive to keep current against county-level data, and unable to bring anyone back next month on its own.

The phone plays, circle prospecting, expired listings, and for-sale-by-owner work, produce listings in Wisconsin every week. They are also where consent exposure lives. Under the Telephone Consumer Protection Act, prospecting by phone or text makes an agent a telemarketer, and when the person on the receiving end later says they never agreed to the call, proving otherwise falls to the caller, number by number.

Predictive seller scoring helps order a call list. What a high score gives you is a guess attached to a name, and the agent still has to go build the relationship the score predicted.

Monthly home-value emails give an agent one good thread into an owner’s year. They also know nothing about what else that household is doing.

Generic all-in-one platforms put everything behind one login after months of configuration. Then the agent spends their week administering software instead of talking to clients.

Do-it-yourself content and newsletters are the right idea. They require a steady supply of material people actually want to open, produced while the agent is also running showings, negotiating, and managing a team. Almost nobody sustains that past the first quarter.

Paid ads switch on instantly and switch off just as fast. The flow stops the same week the spend does.

They share one limit. Every approach on that list reaches a Wisconsin household at the raised-hand moment, and raised hands run about 4% of the state’s owner base in a given year. Nothing on the list is present during the other 96%, which is precisely where the next three years of listings are sitting.

The metro Milwaukee numbers make the same point from the other direction. Listings across Milwaukee, Waukesha, Ozaukee, and Washington counties rose in 24 of the 32 months ending February 2026. Even so, the Greater Milwaukee Association of Realtors wrote in April 2026 that “the current market has no shortage of buyers and buyers are competing for too few listings.” The association added that the extra March listings “were absorbed almost immediately so there is no downward pressure on prices.” Buyers are there in numbers. What decides the outcome is whether a household already knows your name on the day the decision starts.

What an exclusive county partnership does that a stack of tools cannot

One agent, one team, or one brokerage takes a whole Wisconsin county under the Exclusive County Partnership. Their brand runs across the consumer experience there, and no other partner works inside that line. The fee is flat and predictable, with no charge attached to any single lead and no slice taken from the commission at closing, so a big month lands in the partner’s pocket rather than on their invoice.

The connection itself is built differently, which is why it converts. By the time someone asks to be introduced to a partner, they have usually been on ez Home Search for months. They show up carrying a record the agent can read: which streets they kept returning to, where their price kept settling, the valuation they pulled twice, the tour they eventually booked. That first call opens on what the person is actually after, so weeks of trust-building are already done before anyone speaks. Opportunities generally take 30 to 60 days to convert.

Underneath all of it sits the promise that makes people willing to engage at all. The Only Confidential Home Search is that promise. A person’s budget and the details for reaching them do not get sold, resold, recycled, or handed to a list of businesses they never picked. Instead the person gets one Single Local Expert who knows the area, picked as the right fit for what that person needs, not for outbidding anyone. ez Home Search calls that A Better Way To Discover Real Estate. Wisconsin households respond to it by saying what is actually going on in their lives instead of typing in a throwaway email address. Legacy real estate portals are built the other way around, and consumers have worked that out.

Four beats map straight onto how Wisconsin actually behaves.

Start with the database a partner already owns. With roughly 4% of Wisconsin’s owner base transacting in a given year, the biggest opportunity in the state is the past clients and sphere a partner earned years ago. ez Home Search brings that database onto the co-branded platform, keeps it warm with home-value updates, listing alerts, and local market reports the partner never has to write, and fires outreach on real activity rather than on a cold score. Partners reactivate past clients, by repeat business and by referral. Our own data puts the multiple somewhere no other channel reaches, 2.5 to 5 times the market rate, routinely higher than that. The database also stops leaking. Email addresses stop working at a rate of 15% to 22% every year, and one homeowner in ten changes their phone number. Because a partner’s people keep using the search, the current details keep coming back in.

Relocation runs in both directions. Census figures put annual moves past a typical service area on the order of one in twenty people. Wisconsin runs that hard both ways, with four straight years of net domestic in-migration, a Twin Cities commuter shed in St. Croix and Pierce counties, and a Chicago feeder market reaching Walworth County and the Northwoods. Because coverage is national, a past client who starts shopping another state does it on the partner’s own co-branded experience, and the partner sees that activity early. The local listing stays where it was earned, and a referral fee comes back from the far end of the move.

Every opportunity arrives with proof of consent. ezVerify.ai captures the opt-in, stores the recording behind it, runs the number against a known-litigator database, and strips out Do Not Call numbers before anyone dials. It fills in the rest of the contact detail too, and it reads where that person sits in their move, so a Milwaukee County browser and a ready-to-list Waukesha County seller get approached differently.

The conversion tools are already running. A partner can stand up a home-value page, an AVM widget, an instant cash offer, and a QR-code sign-in sheet for open houses, and each one works the moment it is made, since ez Home Search is what runs underneath. Nothing needs configuring and nothing needs administering.

All of it reports into whatever system a partner already runs, because ez Home Search is CRM and martech agnostic. Follow Up Boss gets the fullest version, with a contact’s searches and saved homes showing up in the agent’s dashboard and ezNurture running the automated follow-up. Sure Send™ goes deepest of all. Every other platform carries as much as its integration supports. None of this lands on the partner alone either: there are sales enablement playbooks, Shut Up and Dial events, and weekly coaching sessions, with real people working on the partner’s numbers alongside the technology.

One partner holds a Wisconsin county, and the open list keeps getting shorter

Wisconsin has 72 counties, and the Exclusive County Partnership places exactly one partner in each of them. Many are already claimed. More get taken every month, and after a county is spoken for, that co-branded position is off the market at any price.

The model does not care how large the county is. Milwaukee County closed 9,449 homes in 2025 and Menominee County closed 38, and the same thing decides the outcome in both. Buyers and sellers in a county start attaching one name to real estate there long before anybody picks up a phone. In a county the size of Florence, with 4,646 residents, that recognition is easier to build and worth every bit as much per transaction to whoever holds it.

Wisconsin’s fastest sales growth in 2025 did not happen in the metros. The North region grew 6.7%, led by counties like Sawyer at 18.6% and Polk at 16.5%, while the Southeast grew 0.2% on more than three times the volume. Counties that look small on a map are rarely small opportunities, and they tend to be exactly the ones an agent assumes will still be open next year.

A partner steps onto something that is already running. The search experience, the home valuations, the school and property-tax research, the listing alerts, the co-branding, and the automated follow-up all operate on a national platform, and the partner’s name goes on it. There is no build phase and no launch quarter. A Wisconsin county either has a partner or it does not, and that is worth finding out about yours before someone else does.

What building this yourself costs, against having it built for you

A Wisconsin agent who wants a bigger pipeline is choosing among three answers, whether or not they ever name them.

The default answer is to keep the current mix. Buy the shared leads, run the ads, work the phone, and stay one of more than 15,000 Wisconsin Realtors Association members competing for the same 4% of the state’s owner base that raises a hand in any given year. That produces business every year, and it never accumulates into a position.

The ambitious answer is to build the whole thing in house. That means a home search people come back to on their own, home valuations accurate enough that owners trust them, and school and property-tax research at the county and district level. It also means listing alerts fast enough to matter in a state that has held under four months of supply every year since 2022, co-branded content worth opening every month, consent proof and litigator screening before every dial, and follow-up that fires on real behavior rather than on a calendar. Each piece is buildable. Together they run into millions of dollars and years of engineering, and the data sourcing underneath them is beyond what any single team or brokerage in the state can buy. Most agents who start assemble a fraction of it, then spend their weeks keeping that fraction alive.

The third answer is to take the county position and put your name on a platform that is already running every piece of it.

The trade-off is worth stating plainly. County exclusivity does not fill a calendar next week. Opportunities generally take 30 to 60 days to convert, and the model rewards a partner willing to work an owner database over years rather than one who only wants the households raising a hand this month. An agent looking for a fast transactional lead buy is looking at the wrong thing.

One number carries more weight than the rest. Reactivation of past clients, by repeat business or referral, lands where our own data has always had it: 2.5 to 5 times the market rate. Neither of the other two answers compounds like that.

Go back to where this started. Milwaukee County permitted 199 single-family homes in 2025 and Dane County permitted 1,398. Those two counties will hand an agent completely different years, and neither of them will hand that year to somebody the household has never heard of. There is room for exactly one partner in each of Wisconsin’s 72 counties.

Find out whether yours still has room.

Frequently asked questions

New listings in Wisconsin fell in December 2025 while full-year sales rose. Where are agents finding sellers?

New listings dropped 5.9% in December 2025 while full-year sales rose 2.0% to 69,132. That combination means the sellers came off the existing owner base rather than out of a fresh listing wave.

Wisconsin holds well over a million owner-occupied households and turns roughly 4% of them in a year. Those sellers were already Wisconsin homeowners, and the agents who won them were the ones already in front of them with a home value, a property-tax answer, or a straight read on their local market.

Why does Milwaukee County build so few new homes compared with Dane County, and what does that mean for my business?

Milwaukee County permitted 199 single-family homes in 2025 against Dane County’s 1,398, and the pattern runs back a decade. The Milwaukee metro averaged 17.9 annual housing starts per 1,000 households from 2015 to 2025 while the Madison metro averaged 61.2. The divergence is decades old: Dane County and the city of Madison passed Milwaukee County and the city of Milwaukee in total equalized property value in 2018, after thirty years in which Dane’s value rose 526% against Milwaukee County’s 178%, per the Wisconsin Policy Forum in August 2018.

Practically, nearly every Milwaukee County transaction three years out is an existing home whose owner is living in it today, which makes your database the pipeline. In Dane and Waukesha counties, builder relationships and new-construction search behavior belong in the plan alongside it.

How do I work a Northwoods county where much of the demand comes from Chicago and the Twin Cities?

The demand is real and it is measurable. The North region posted Wisconsin’s fastest sales growth in 2025 at 6.7%, Vilas County’s median reached $425,500, and Oneida County’s sales rose 11.4%. National coverage matters more here than anywhere else in the state, because a Chicago household shopping Eagle River or Minocqua is searching from several hundred miles away, months before they call anyone.

On a co-branded ez Home Search experience, that household is searching on your platform and their activity surfaces to you. A shared lead works the opposite way: the same out-of-state name is sold to several agents at once, and none of them has a relationship with the person.

Wisconsin property tax bills jumped again. How do I turn that into listing appointments?

Start by being the person who explains the bill. Gross statewide levies were on pace to rise roughly 5% in 2026 after 4.4% the year before, the largest increase in 18 years, and K-12 levies alone rose 7.8%, the biggest jump since 1992.

Most owners assume the rate went up. Wisconsin’s average gross property tax rate actually fell from 2.3067% in 2000 to 1.5029% in 2024, and the value base underneath it more than tripled. A county exclusivity partner can hand an owner their own tax picture by county, city, and ZIP alongside a monthly home valuation. It gives you something worth saying in a year when nothing is listed, which is where listing appointments three years out actually come from.

My county’s median is under $260,000 and Waukesha County’s is near $490,000. Does one lead strategy work across Wisconsin?

No, and the spread is the reason. Wisconsin’s regional medians ran from $255,000 in the Central region to $380,000 in the South Central in 2025, and county medians stretched from roughly $195,000 in Clark County to $490,000 in Waukesha County. Inventory split the same way, with 2.6 months in metropolitan counties, 3.2 in micropolitan counties, and 3.9 in rural counties in December 2025.

What does travel across all of them is the sequence. Reach the household early, stay useful through the years when nothing is listed, and be the name they already trust when the move starts. County exclusivity is built around that sequence rather than around a price band.

Wisconsin lost about 9,500 manufacturing jobs in a year. Is that going to hurt my listing pipeline in the Fox Valley?

The composition matters more than the total. Wisconsin’s manufacturing workforce fell from 461,100 in January 2025 to 451,600 in January 2026, and industry leaders attribute most of the decline to retirements rather than layoffs. A retirement turns into a housing decision far more often than a layoff does, and it usually arrives with decades of equity behind it.

Health care employment reached a new high of 324,200 over the same period. Outagamie County closed 2,219 homes in 2025 and Winnebago County closed 1,996. Those homes are changing hands, and the Fox Valley pipeline holds.

Wisconsin has had four straight years of people moving in from other states. How do I get in front of them before they choose an agent?

Net domestic migration ran 5,828 in 2024 and 6,984 in 2025, a fourth consecutive positive year after two decades of losses. Those households research the Wisconsin market for months from wherever they live now, and none of them has met an agent yet.

To meet them that early, you have to be the local brand attached to the search experience they are already using, which is exactly what a county position buys. It runs in reverse too. When one of your past clients starts searching another state, that activity surfaces to you, so you keep the local listing and earn a referral instead of finding out once the move is done.

Data centers are going up in Racine, Dodge and Ozaukee counties. When does that turn into home sales?

Part of it already has. Microsoft completed its first Mount Pleasant facility in Racine County in May 2026 with roughly 550 full-time staff on site and about 800 expected once a second building runs, after a first build phase that employed nearly 10,000 construction workers across about two years. Meta broke ground in Beaver Dam in Dodge County in November 2025, and Vantage Data Centers is developing a campus at Port Washington in Ozaukee County.

Permanent staff put down roots in a way a temporary build crew does not, so the households worth tracking are the ones already living in those counties whose equity and plans are moving. Racine County closed 2,361 homes in 2025 and Ozaukee County closed 1,115 on a $479,000 median. An agent watching search and valuation activity across those counties sees the shift well before it becomes a listing.
08.26.2026

How to Find South Dakota Real Estate Leads Before They List

South Dakota’s next buyers already own a home here

The family that will list with you in the next 9 to 18 months already lives in your county. They are not thinking about it. They have a mortgage, a third grader, and a kitchen they keep meaning to redo.

That is not a guess. It changes how you should think about South Dakota real estate leads, because this state ranks fourth in the nation for growth that comes from births rather than arrivals, running about 2.0 children per woman against 1.6 nationally. Nearly seven in ten South Dakota households own their home, better than three points above the national rate. Net migration adds about half a percent a year, so very little of your future business is driving in from out of state.

Most lead products are built on the opposite assumption. However they charge you, per lead, at closing, or out of the commission, they all decide who counts as a lead at the same moment: when somebody raises a hand on a form. That moment is late. By then the household has run their own numbers, argued about school districts with their spouse, and usually decided who they are calling.

That hand raise is also the whole product. A legacy portal lead does not co-market with you, does not build your name across the county, and does not go back to the people already sitting in your database.

The work that pays here is being the name they already know on the Tuesday a job offer lands, a parent gets sick, or a second baby makes the house too small. You cannot buy that from a list. The rest of this page is where it comes from instead.

What is happening across South Dakota, and what it means for your pipeline

Six things are moving in South Dakota at once, and they pull in different directions. Know all six and you can defend next quarter’s budget instead of guessing at it.

Two workers in safety vests operate machinery in a South Dakota manufacturing plant, one of several sectors supporting the state's housing demand
Manufacturing is one of six sectors carrying South Dakota employment, and no single one dominates.

Purchase lending has risen three years running. Federal mortgage disclosure data put home-purchase loans written statewide at 9,289 in 2023, then 9,543 in 2024, then 9,881 in 2025, after a run that peaked at 14,048 in 2021 (Consumer Financial Protection Bureau, HMDA, retrieved August 2026). The 2022 to 2023 fall tracks the jump in mortgage rates rather than anything local. Cash buyers never appear in these numbers at all, so real closings run higher than the series shows. If you cut your marketing in 2023 and never turned it back on, you are budgeting against a market that stopped existing three years ago.

Prices reset, then held. Real median listing prices moved from about $296,000 in 2018 to about $390,000 in 2024, easing to roughly $379,000 in 2025 (Dakota Institute, June 2026). Over that stretch South Dakota passed both Nebraska and North Dakota and now sits second in the region behind Minnesota. It also gave back the least from its peak, 2.3 percent, against Nebraska at 8.6, Minnesota at 6.7, and Iowa at 11.8. When a seller tells you they missed the top of the market, you can show them how little of it this state actually surrendered.

South Dakota builds more housing per person than any neighbor. The state issued 6.49 residential building permits per 1,000 residents in 2024, ahead of Nebraska at 5.22, Iowa at 3.88, Minnesota at 3.61, and North Dakota at 2.92 (Dakota Institute, June 2026, from Census Bureau permit data). Every one of those new builds is a competitor for your buyer and a listing from whoever is vacating an older house to move into it. Most agents chase the first half and let the second walk.

Growth is steady, and more of the arrivals come from further away. The state added 7,984 residents between July 2024 and July 2025, a gain of 0.86 percent, with net migration contributing 0.57 points and births over deaths the other 0.28 (Dakota Institute, June 2026, from Census estimates). For the second year running, more of that net inflow came from outside the country than from other states. Those buyers need escrow, well testing, and winter explained to them, and the agent who does that patiently gets the next three families from the same workplace.

No single industry carries this state. December 2024 nonfarm employment ran 91,000 in trade, transportation and utilities; 83,900 in government; 78,500 in private education and health services; 50,800 in leisure and hospitality; 42,900 in manufacturing; and 31,800 in construction, with statewide unemployment at 2.0 percent on a June 2026 labor force of 488,700 (South Dakota Department of Labor and Regulation, with the Bureau of Labor Statistics). A single plant closing does not take your year with it. It also means no single employer list gets you the county.

Movement runs both directions, and both directions are business. Forty of South Dakota’s 66 counties recorded more people leaving for other states than arriving from them in 2024 to 2025, while Lincoln, Lawrence, and Campbell counties each drew net inflows above two percent of their population (Dakota Institute, June 2026). Read that the right way. A household leaving your county still owns a house in it, which is a listing plus a referral fee from the agent on the other end. A household arriving is a buyer who needs someone who knows which streets flood and which school boundary is about to move. Work one direction and you are working half your county.

Four in five of your buyers are also your sellers

Ask ten South Dakota agents what they want and the answers split two ways: get me listings, or get me buyer leads. Both camps are chasing the same households, and both are paying for them twice.

Start with the arithmetic. The National Association of Realtors put first-time buyers at 21 percent of purchases in its 2025 Profile of Home Buyers and Sellers. No year has come in lower since the association began counting in 1981, and the median first-time buyer reached a record age of 40. Roughly four in five buyers, then, already own a house. Most are selling one to fund the next.

Two different people sit on either side of any one closing table. Follow a single household across a whole move, though, and they play both parts, usually inside the same ninety days. What throws most agents off is the order. They behave like a buyer months before they behave like a seller. They browse at night. They run numbers in a spreadsheet nobody sees. They talk to a lender. The call to an agent lands near the end of that sequence.

South Dakota has more of that household than almost anywhere. Owner-occupancy statewide ran 69.3 percent in 2024, better than three points above the national rate (USAFacts, from Census Bureau data). By county the 2020 Census puts Hanson at 83 percent and Todd just under half, with Minnehaha and Pennington in the mid-60s (Dakota Institute, June 2026). Whatever your county’s number is, that is the share of your market that is a future seller currently living as a neighbor.

An automated valuation model, the tool that estimates a home’s worth from public records and recent sales, is the thread that holds a relationship together between moves. A homeowner checks their value once in a quiet year and thinks nothing of it. Then they check it three times in a month, save two listings in a school district they have never searched before, and reopen a search they abandoned in the spring. Nobody fills out a form during any of that. The household is deciding anyway, months before anyone raises a hand.

Reach them there and the buyer you helped this year becomes the listing you take in four.

See whether your South Dakota county is still open.

Ten counties hold most of South Dakota, and two of them trip up outsiders

Most South Dakotans live in ten of the state’s 66 counties, and the principal city inside each one is where an agent’s name has to be known first. Find yours, then read the two groups below, because they call for two different playbooks.

Tree-lined downtown street in South Dakota with a clock tower and parked cars, in the state's largest metro
Sioux Falls added more than 20,000 residents between 2020 and 2025.
CountyPopulationPrincipal city
Minnehaha206,930Sioux Falls
Pennington115,903Rapid City
Lincoln73,238Harrisburg
Brown37,733Aberdeen
Brookings35,980Brookings
Meade30,954Sturgis
Codington28,971Watertown
Lawrence28,053Spearfish
Yankton23,517Yankton
Davison19,922Mitchell

County populations from the U.S. Census Bureau Population Estimates Program.

Two of those pairings deserve a note, because getting either one wrong marks you as an outsider inside thirty seconds of a listing appointment. Canton is the Lincoln County seat, Harrisburg is the largest city lying wholly within the county, and Sioux Falls itself spills across the line into Lincoln. In Lawrence County the seat is Deadwood while the largest city is Spearfish.

The first group is growing fast, and the fastest movers are small. Between 2020 and 2025, Harrisburg went from 6,845 residents to 10,405 and Tea from 5,698 to 8,019. Box Elder added roughly 2,000 and Spearfish roughly 1,900. Sioux Falls itself climbed past 213,000 and Rapid City past 80,000, while Brookings reached 25,355 and Watertown 23,736. In these markets your competition is a builder, and your listing comes from whoever is leaving an older house behind.

The second group held roughly flat, and the obvious conclusion about it is the wrong one. Aberdeen eased from 28,424 to 27,961. Pierre and Madison each slipped about 1.5 percent, Sturgis 2.5 percent, Dell Rapids 3.2 percent. Vermillion finished flat at 11,720 and Mitchell added 79.

Flat population with high ownership is not a dead market. It is a market where every deal comes from turnover instead of arrivals. Brown County holds roughly 37,700 people and most of them own their homes. Those owners still get married, get promoted, get transferred, inherit a house from a parent, and decide one spring that the yard has become too much. What a flat county takes away is the easy tailwind. What it hands back is a smaller field of competing agents and a database that can realistically cover the whole county, which is a trade plenty of agents in Sioux Falls would make tomorrow.

There are really six South Dakotas, and the demand driver in each

South Dakota is six regional markets wearing one state’s name, and what generates demand differs in every one of them.

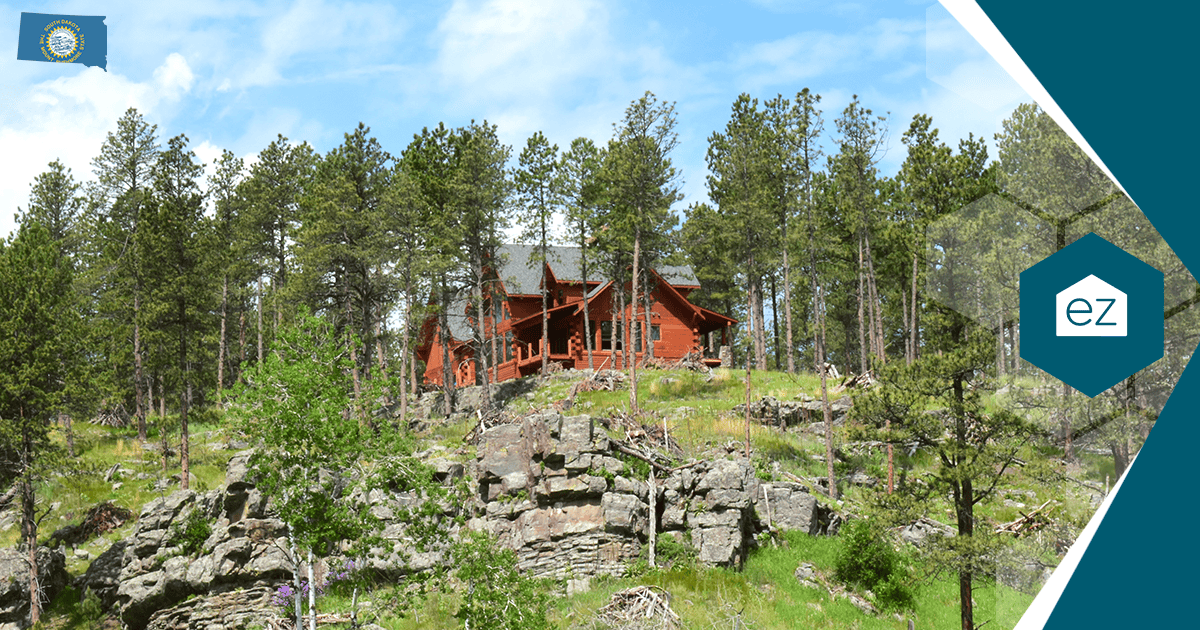
Wooden cabin surrounded by pines and rocky terrain in the Black Hills of South Dakota
The Black Hills market runs on different demand drivers than the Sioux Falls metro.
RegionRepresentative countiesWhat is driving demand
Sioux Falls metroMinnehaha, Lincoln, McCook, TurnerMinnehaha and Lincoln together produced about two-thirds of the state’s entire 2024 to 2025 population increase; Harrisburg grew 52 percent and Tea 40.7 percent from 2020 to 2025
Black Hills and BadlandsLawrence, Custer, Butte, Fall RiverLawrence County added 750 residents with a net inflow above two percent of its population, and Spearfish grew 15.6 percent from 2020 to 2025
Rapid City and the Ellsworth corridorPennington, MeadeElevate Rapid City projects demand for 10,175 homes between 2025 and 2030 tied to the Ellsworth mission
Glacial Lakes and PrairiesCodington, Brown, Day, Roberts, Grant, Marshall, Hamlin, DeuelWatertown grew 4.7 percent from 2020 to 2025 while Aberdeen eased 1.6 percent, the widest split between two regional centers in the state
James River Valley and central eastBeadle, Davison, Hanson, Sanborn, Spink, LakeBeadle County recorded the state’s largest net domestic outflow in 2024 to 2025, nearly offset by one of its largest international inflows
Missouri River and southeastHughes, Stanley, Brule, Charles Mix, Yankton, Clay, Union, Bon HommeUnion County carries one of the two highest median household incomes in South Dakota, above $100,000 in 2024

The Rapid City numbers deserve their own paragraph, because they are the most concrete forecast any agent in this state gets to work with. One of those six comes with a number the others do not have. The Rapid City area is projected to need 10,175 homes between 2025 and 2030, split as 2,410 inside the city and 7,765 across the surrounding region. That figure is public, and almost nobody in the business has read it, because it sits in the minutes of a legislative committee. Tom Johnson, chief executive of Elevate Rapid City, gave it to the South Dakota Legislature’s Select Committee on Ellsworth Air Force Base in October 2024, against a projected gain of 8,137 residents and 3,360 households. The area had already added 7,142 residents and 2,262 households between 2020 and 2024.

The rest of that testimony explains where the demand comes from. Colonel Derek Oakley, commander of the 28th Bomb Wing, told the same committee the base expects to add 4,064 people by fiscal year 2041: 1,664 active military, 915 spouses, and 1,485 children. Box Elder officials put their city at 14,512 residents excluding the base, up 21.9 percent since 2022, with more than $27 million spent on housing and more than 366 family lots and 461 multi-family units built or underway. Johnson also noted Ellsworth is the ninth largest employer in the state, with a 2023 economic impact of $886.8 million and roughly 8,200 jobs created across the region.

Take the ten-thousand-home number into your next listing appointment. A seller in Rapid Valley deciding whether to wait one more year is weighing a hunch against a forecast that runs on a federal construction schedule, and you are the only person in the room who can tell them the difference.

Income sorts the state differently than population does. Lincoln and Union counties both cleared $100,000 in median household income in 2024, the two highest in South Dakota, with Lincoln covering southern Sioux Falls and Union sitting on the suburban Sioux City side (Dakota Institute, June 2026). Among the smaller counties the range runs from roughly $57,000 in Walworth to about $88,000 in Stanley, and every metropolitan-area county sits at or above the state median. Set your farming budget against the county you work, not the state average.

The remote work demand most South Dakota agents are not counting on

Most agents have written off remote work. The numbers say they wrote it off about three years too early, and South Dakota is where that mistake costs the most.

Two people in a small boat on a clear South Dakota lake bordered by forested hills
Lifestyle markets are where remote-capable households look first.

Nationally, 13.3 percent of American workers worked from home in 2024, against 5.7 percent in 2019. That is more than double, five years on. It is also down from 13.8 percent in 2023, and the peak came in 2021, so what you are looking at is a level that rose, overshot, and settled high.

South Dakota’s own number is where this gets interesting for you. Eight percent of South Dakota workers worked from home in 2024, up from 6.1 percent in 2019 (Census Bureau, American Community Survey one-year estimates). That is a third more than before the pandemic, and it still ranks near the bottom of the fifty states. National employers now hire remotely as routine. This state has caught very little of it, which puts most of that hiring in front of South Dakota rather than behind it.

Some of it is already here. When I gave the keynote for R-CALF a few years back, the conversation that stayed with me was not the policy discussion. It was how many ranchers described a son, a daughter, or a spouse already doing knowledge work from the house, and how they had remodeled part of the place to make it work. One had carved an office out of a spare bedroom. Another had wired a corner of the shop for two monitors and a decent connection. Nobody in that room would have described themselves as living in a remote-work household, and a good number of them were.

Ask about it directly. Buyers with remote-capable jobs want a room with a door that closes rather than a corner of the living room. Two careers under one roof turn into a question about what else sits on the lot, an accessory dwelling unit or a building that can be finished. Square footage that used to be a preference has become a requirement. And they will want to know whether the internet delivers what the listing claims, which across much of western South Dakota is worth answering before the showing.

The agent raising those questions in Spearfish or Watertown today is the one who sounds informed when the hiring catches up.

The lead sources South Dakota agents use, and what each one returns

Every lead source in this state works up to a point, and knowing exactly where each one stops is worth more than a subscription to any of them.

Shared leads buy you speed and very little else. A shared lead from a legacy portal puts a name in your database this afternoon, which is the one thing no other channel does on demand. What arrives with it is the other three or four agents who bought the same name, and a person who never chose you and knows it. In Sioux Falls that math sometimes still clears. In a county of nine thousand it rarely does, because the price was set against metro volume and your volume is not metro volume.

Your own front door is the most defensible asset here, and the slowest. An IDX site, a content library, and a paid search budget eventually produce business you own outright, with nobody able to reprice it or resell it to the agent across town. It is also the slowest route on this list. You are funding a two-year runway and administering software the whole time. Partners we work with who tried this route first tend to describe the same experience: it worked, and it took longer and cost more than the pitch suggested.

The phone still converts here, and it carries the most legal exposure. Cold calling, circle prospecting, and outreach to owners selling on their own or coming off an expired listing all still convert here, particularly outside the metros where people answer unknown numbers. The exposure is consent. Pick up the phone to prospect, or send a text, and federal law counts you as a telemarketer. If the person on the other end disputes consent, proving it is the caller’s job, and each unproven contact carries $500, rising to $1,500 where the violation was willful, with no ceiling on the total. Predictive-seller software narrows who you dial, which genuinely helps. A high score is still a guess about a stranger, and you are the one who has to build the relationship the score predicted.

Nothing converts better than owning the ground, and nothing scales worse. Open houses, sphere work, and geographic farming beat every other channel on this list for conversion rate. They also stop scaling at the edge of your drive time, and in West River terms that edge arrives fast.

Four things about South Dakota make all of this harder than a national playbook assumes.

Territory out west is measured in hours, so a lead with no context attached costs you half a day to qualify. In Harrisburg, Tea, and Box Elder, where growth is fastest, the builder reaches the buyer first and you are negotiating for position after the fact. Families relocating for the Ellsworth mission move on a schedule set by orders, and they start researching from three states away. And an acreage or agricultural-status property changes the financing path completely, which is knowledge no lead vendor includes and every one of those sellers assumes you already have.

There is a fifth approach, and it is the one everything above has been circling. Call it activity-based timing. Instead of paying for a name at the moment somebody raises a hand, you watch what households in your county do inside a home search they trust: a search picked back up after four quiet months, a second valuation run in three weeks, a saved home opened again. That behavior shows up months before a form does. Whether you can see it is a separate question, and it is the one the rest of this page answers.

Find out whether your county is still available.

What South Dakota homeowners want to know before they list

Three questions come up before any South Dakota homeowner will talk seriously about listing, and an agent who can answer all three earns the appointment.

Aerial view of a South Dakota suburban neighborhood with houses, streets, and mature trees against rolling hills
Roughly seven in ten South Dakota households own the home they live in.

What is my equity worth today. An automated valuation model gives the number, and the number is only the opening. The follow-up question is what that equity buys in the neighborhood they are considering, which in this state often means comparing a paid-off house in Aberdeen against a mortgage in Sioux Falls. Sellers who run their own valuation monthly for two years are not idly curious. They are building the confidence to move, and when they do, they call whoever’s name has been on that valuation the whole time.

What will my taxes do to me. South Dakota changed this answer in 2025, and the change breaks into three pieces depending on who is asking.

For every owner-occupied home, Senate Bill 216 caps assessment growth at 3 percent countywide for five tax years, covering taxes payable from 2027 through 2031. It was signed March 13, 2025 and took effect that July.

For the owner weighing a kitchen before they sell, improvements worth less than 40 percent of the home’s value no longer push the assessment up. That answers a question you have probably been asked and could not answer cleanly before.

For older and disabled homeowners, the assessment freeze got considerably wider. The income limit for a multi-person household went from $45,000 to $65,000, and the maximum eligible home value from $300,000 to $500,000.

That last one is a call list. Every owner in your county sitting between the old thresholds and the new ones just became eligible for something they almost certainly do not know exists, and the person who tells them is the person they remember.

Am I selling into a market that will hold. The answer is better than most agents assume. Median inflation-adjusted purchase loan amounts in South Dakota rose from about $224,000 in 2018 to about $267,000 in 2021 and roughly $272,000 in 2024, while every neighboring state peaked and then fell back (Dakota Institute, June 2026). Federal disclosure data carry it further: the average purchase loan written in this state reached roughly $328,200 in 2025, the highest in the available series. Those federal figures are approximate, because loan amounts get rounded to midpoints before publication.

Then give them the other half. Those same loan amounts climbed 21 percent between 2018 and 2024 while median homebuyer income rose about 10 percent. Buyers are stretching further than they used to, which is why a well-priced listing moves and an ambitious one sits.

None of these three conversations requires a transaction to be underway. That is the point of having them. A homeowner who hears from you about an assessment freeze in a year they had no plans to move is a homeowner who already has an agent when the plans change.

These 10 counties bring the best ROI

Ten counties outside Minnehaha and Pennington carry enough population and enough named communities to build a business on. If yours is on this list, the communities beside it are your farm.

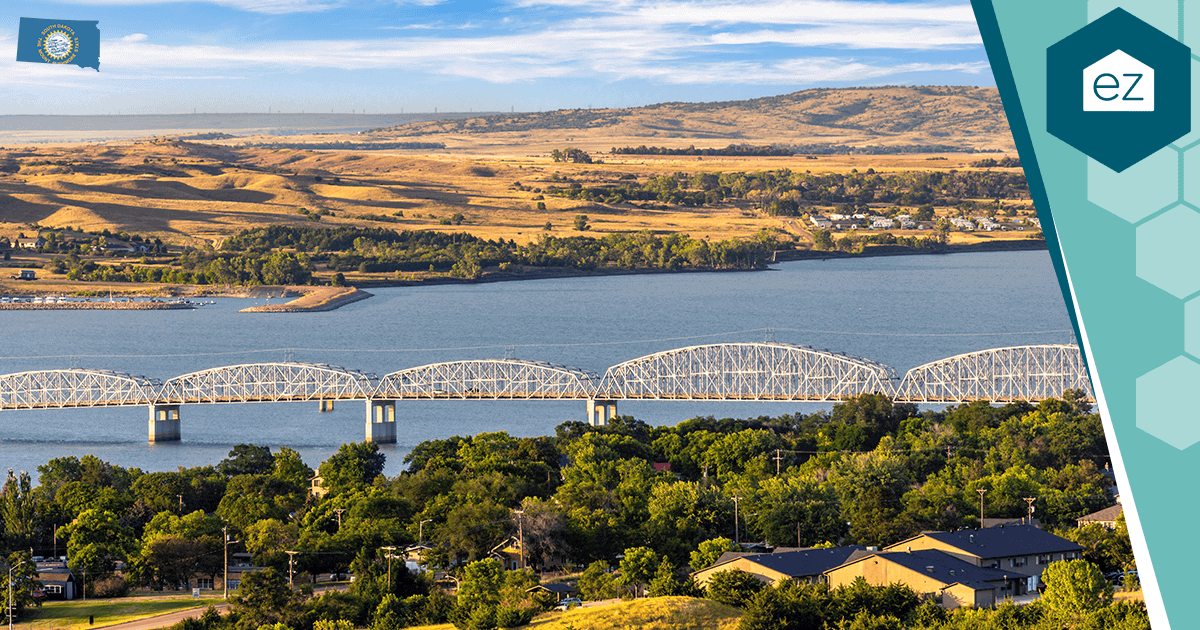
Metal truss bridge spanning the Missouri River in South Dakota with rolling hills beyond
Ten counties outside the two metros carry enough volume to build a business on.
CountyCommunities
LawrenceSpearfish, Deadwood, Lead, Whitewood
CusterCuster, Hermosa, Fairburn, Pringle
ButteBelle Fourche, Newell, Nisland, Vale
UnionNorth Sioux City, Dakota Dunes, Elk Point, Alcester
ClayVermillion, Wakonda, Meckling
HughesPierre, Blunt, Harrold
BeadleHuron, Wolsey, Wessington, Hitchcock
RobertsSisseton, Wilmot, New Effington, Rosholt
HamlinHayti, Estelline, Castlewood, Bryant
LakeMadison, Wentworth, Chester, Ramona

State money is moving into these places, and it is easy to miss because it gets announced through housing agencies rather than through anything an agent reads. In December 2025, South Dakota Housing awarded $59.4 million toward building and rehabilitating rental housing across the state.

Those awards land in specific towns. Fall River Health Services received $1,159,089 for infrastructure supporting 35 single-family lots and 36 multifamily units in Hot Springs. A separate award of $1,016,691 went to infrastructure supporting 236 multifamily units in Vermillion.

Two hundred thirty-six units land hard in a city of 11,720. That is a rental base that turns into first-time buyers inside five years, landlords who will want a second opinion before they buy the next building, and trades workers who need somewhere to live while they put it up. Hot Springs is smaller still, and 35 new lots there will move what comparable sales look like across Fall River County.

An agent watching Vermillion knew about that award the week it was announced. An agent buying leads statewide will find out when the listings appear.

What staying present with every homeowner in your county actually takes

Go back through the last eight sections and add up what they actually ask of you.

You need a home search that pulls past clients back without a reminder. You need a valuation that refreshes every month on every home in your database. Your listing alerts have to be fast enough to matter in a competitive week, your newsletter has to be worth opening, and activity signals have to surface inside the CRM your team already runs. And every number has to carry proof of consent before anyone dials it.

Price the second one by itself. A valuation that updates monthly on every house in your county needs current public records, recent sales, and a model that holds up when a seller challenges the number in front of you. That is a data contract before it is software, and the data contract is where most agents stop reading.

Now add the other five. Then add the person who keeps all six running on the Thursday you are at a closing.

That is the arithmetic, and it is why most agents who try this get three of the six going and maintain those badly. The problem is not effort. It is a full-time technology job sitting on top of a full-time sales job, and one person cannot hold both.

The Exclusive County Partnership from ez Home Search is the other route. One county goes to one agent, team, or brokerage. The consumer experience carries their brand, and nobody else holds that territory. The leads are yours to keep. Nothing is billed per lead, and no share of your commission is taken at closing. A strong month stays entirely yours.

The conversion rate traces back to how the consumer side was built. ez Home Search is The Only Confidential Home Search: nobody sells, recycles, or broadcasts a searcher’s contact details and budget to businesses they never picked, and each of them is paired with a Single Local Expert who knows the area. That pillar is how ez Home Search makes good on A Better Way To Discover Real Estate. Someone who searched in confidence and chose their own expert arrives warm rather than cornered, and our partners typically convert those connections inside 30 to 60 days.

Four pieces of that partnership matter most in this state.

Your database becomes the business. In Aberdeen, Pierre, and every county where growth comes from turnover, the people you already know are the pipeline. Between 88 and 92 percent of buyers say they would hire the same agent again. About 18 percent come back. Repeat and referral work makes up roughly 41 percent of the average agent’s volume. Reactivation for ez Home Search partners runs 2.5 to 5 times the market rate, and the mechanism is dull on purpose: the co-branded search, the monthly values, and the alerts hold the relationship open without the agent needing to think of something to say.

Departures stop being losses. Forty of South Dakota’s 66 counties recorded negative net domestic migration in 2024 to 2025. Every one of those households owns a house in the county they are leaving. Because coverage is national, a client shopping Denver or the Twin Cities does it on your platform, and you see the move coming in time to win the listing rather than hearing about it afterward.

One name wins before the comparison starts. The Profile of Home Buyers and Sellers puts the share of sellers who reach out to a single agent before deciding at 81 percent, with 77 percent of repeat buyers interviewing just one. When a single co-branded name sits on the home search a county already uses, that behavior runs in your favor.

The riskiest call becomes the safest one. ezVerify.ai captures the opt-in, stores the recording that proves it, checks each number against a known-litigator database, drops anyone listed on Do Not Call, and fills in the rest of the contact record. What that produces is a paper trail rather than a lead score, and a consent dispute is decided on the paper trail.

Why the model works the same in Hamlin County as in Minnehaha

The instinct says county exclusivity only pays in a big county. Run the numbers and it often works the other way.

Compare the two positions honestly. A Minnehaha partner has far more transactions within reach. They also have hundreds of competing agents, a database that covers a sliver of the county, and a farming budget that has to stretch across an entire metro.

A Hamlin County partner has fewer transactions available. Hamlin is small enough to miss the state’s ten most populous, covering Hayti, Estelline, Castlewood, and Bryant. That partner can also become known by name to a real share of every household in the county inside two years, for a fraction of the spend, in a market where owner-occupancy runs well above the statewide 69.3 percent, as it does across most of this state’s rural counties.

Recognition is the asset in both places, and the research is the same in both places. Most sellers contact one agent before choosing. Most repeat buyers interview only one. That position is worth as much in a county that size as in one holding 206,000 people, and it costs far less to reach.

One partner holds a county at a time. A good many of South Dakota’s 66 counties have already gone, and the list shortens month by month.

What a partner steps into is already built and already running. Search, monthly valuations, alerts, and the follow-up engine all belong to the national ez Home Search platform, co-branded to them. Nobody has to configure it and nobody has to administer it, so it produces from the first week rather than the first year.

It takes about a minute to check whether your county is open, and it commits you to nothing.

The decision in front of you

Every South Dakota agent solves the same problem, which is how to be known to a household before that household needs you. There are three ways to do it, and they differ mainly in what you own at the end of a year.

The first is to keep buying shared names in whichever metro everyone else is bidding on. It produces something every month, it never compounds, and the cost per closing climbs as more agents buy into the same pool. Plenty of good agents run this way for years and never build an asset they own.

The second is to build the engine yourself. You already priced that a few sections ago. Every piece is achievable alone, and the problem is the assembly and the upkeep, not the ambition.

The third is to hold a single county on a platform that already runs every piece of it, co-branded to you, with nothing charged per lead and no cut of your commission.

Here is the trade-off, because you would find it anyway. County exclusivity asks you to commit to a territory before you have seen a year of what it produces, at a flat fee whether the month is strong or slow. In a state with real seasonality and a Sturgis window that scrambles three counties every August, some months will feel like you are paying for quiet. The partners who do best with this know they are buying a position rather than a monthly lead count, and they judge it across a year.

Sixty-four of South Dakota’s 66 counties sit outside the two metros where most agents are looking. Some are already held. Some are not.

The first step is much smaller than the decision. Nothing gets signed while you find out which one yours is.

South Dakota’s next buyers are already living in your county, paying their mortgages, checking their home values, and waiting for something in their lives to change. One agent gets to be the name they already know when it does.

Find out today whether your county is spoken for.

Frequently asked questions

How do I reach families relocating for the Ellsworth mission before they land in Box Elder or Rapid City?

Families relocating for Ellsworth start house-hunting from wherever they are stationed now, often months before their orders are final, and they search nationally rather than locally. That gap is your window. A family in Georgia researching Box Elder schools and commute times is invisible to any lead source that only watches your local market.

National coverage is what makes them visible. When someone searches Box Elder, Rapid City, or Summerset from three states away on a platform carrying your name, their activity reaches you while they are still deciding. Douglas School District already enrolls 1,041 military-connected students out of 2,816, and district leadership has projected another 1,500 arriving over fifteen years, with roughly three quarters of them at elementary age. Those are families who need four bedrooms and a yard, and they are choosing an agent long before they arrive.

Where do seller leads come from in the Sioux Falls metro when so much of the growth is new construction in Harrisburg and Tea?

Seller leads in the Sioux Falls metro come from the households moving into the new construction. Harrisburg grew 52 percent between 2020 and 2025 and Tea grew 40.7 percent, and the families filling those builds are overwhelmingly leaving an existing home somewhere in Minnehaha or Lincoln County.

Builders capture the buy side. The sale of the home they are vacating is unclaimed, and it usually goes to whoever the household was already talking to. When one of your contacts starts searching new construction in Harrisburg, that tells you a listing is coming in that household two to six months out.

Does South Dakota’s owner-occupied assessment cap change what homeowners want to know before they list?

South Dakota’s owner-occupied assessment cap changes the listing conversation more than most agents have noticed. Senate Bill 216 holds assessment growth to 3 percent countywide for five tax years, covering taxes payable from 2027 through 2031, and it exempts improvements worth under 40 percent of a home’s value from pushing an assessment up.

Two practical consequences follow. An owner weighing a renovation before selling now has a clearer answer about what it does to their tax bill. And the widened assessment freeze for older and disabled homeowners, which raised the multi-person income limit from $45,000 to $65,000 and the eligible home value from $300,000 to $500,000, made a large group of South Dakota owners newly eligible for relief they may not know exists. That is a genuine reason to call people who are not thinking about moving.

How do I build a pipeline in Aberdeen or Pierre when the population there is not growing?

You build a pipeline in Aberdeen or Pierre out of moves that have nothing to do with population. In a market where the household count is flat, roughly the same number of houses change hands every year anyway, and they change hands for reasons that never appear in a growth statistic.

Work the list of reasons instead. Estates come up constantly, and the heirs usually live somewhere else and need someone local they can trust. People marry and divorce. Retirements turn a four-bedroom into a burden. Employers transfer people without anyone leaving the county. Adult children move a parent closer to them. None of that shows up in a census estimate, and all of it is knowable if you are the name those families already have.

The advantage in a flat county is that the list is finite. You can genuinely know most of it. An agent in Sioux Falls cannot say that about their market at any price.

What makes a Black Hills acreage or agricultural-status lead different from a Rapid City city lead?

The financing and the diligence are different, and the buyer usually does not know that yet. A property over roughly ten acres, or one carrying agricultural status, often falls outside conventional lending and needs a portfolio lender. Rural properties on private well and septic add inspection steps, timelines, and costs that a city buyer never encounters.

That gap is an opportunity. A buyer looking at land near Custer, Hermosa, or Whitewood who reaches an agent that already knows which lenders write these loans has found their agent on the first call. No lead vendor supplies that knowledge, and every seller of an acreage property expects you to have it.

How does the Sturgis Rally window change lead timing in Meade, Lawrence, and Pennington counties?

The Sturgis Rally compresses and distorts a full month of activity across Meade, Lawrence, and Pennington counties, and national tools do not model it at all. Showings get difficult across Meade and northern Pennington counties during the rally, inventory that would otherwise list waits, and short-term rental economics pull some owners out of the selling decision entirely for the season.

Plan around it rather than through it. The weeks before and after the rally carry unusual attention on the region from people who visited and started imagining living there, which is a genuine buyer source in Spearfish, Belle Fourche, and Sturgis itself. Activity signals matter more here than in any other South Dakota market, because a visitor who saved three homes in August and comes back to them in November is telling you something a seasonal listing count never will.

08.25.2026

How to Get More Real Estate Leads in Utah, County by County

Most people who will buy and sell homes in Utah already live there. Utah’s growth in 2025 ran 57% from natural change, births minus deaths, and 43% from net migration, arrivals minus departures. That added 44,351 residents to reach 3,551,150 (Utah Population Committee, Kem C. Gardner Policy Institute, December 2025). Births carried the majority for the first time this decade.

That decides where the budget for Utah real estate leads goes. Your county’s next listing belongs to a current owner. Presence with those owners compounds. Ads aimed at newcomers cost more per conversation.

Where those owners sit changes by county, and so does the lead source that reaches them. Tooele County and Salt Lake County reward different campaigns. The name those owners already know gets the call.

The listing drought Utah’s own housing data says never happened

Utah agents widely believe the state has too few homes for sale. Utah’s own Kem C. Gardner Policy Institute documented that belief twice, in 2018 and in 2025, and the data contradicted it both times. In 2018, 72.9% of residential listings sold statewide against a historic average of 55%, and the institute wrote that “Realtors, almost universally, complain of a scarcity of listings, but the data show relatively high levels of listings in recent years” (The Year in Charts: Utah’s Housing Market 2018). The same institute reviewed 2024 and found the recovery in listings “runs counter to the expectation of a listing drought” (Kem C. Gardner Policy Institute, July 2025). Both times, agents read fast sales as a sign that sellers had stopped coming.

The prediction made sense at the time. More than 70% of Utah mortgage borrowers hold a rate below 5% (Kem C. Gardner Policy Institute, July 2025), so the accepted view held that owners would keep those cheap loans, stay put, and cost agents the seller side. The average number of homes for sale in a month ran 8,871 in 2016, fell to a record low of 2,978 in 2021, then climbed to 8,800 in 2024, the highest since 2016 and back inside the pre-2020 range of roughly 8,000 to 9,000 (UtahRealEstate.com via Kem C. Gardner Policy Institute, July 2025). The 2021 low was one year out of nine.

Homes in Utah do sell fast. Median days on market, the typical time between listing and going under contract, was 34 in 2024 against a long-term average of 44, after bottoming at 7 days in 2021 (Kem C. Gardner Policy Institute, July 2025).

Active listings are a stock, meaning the homes sitting on the market on a given day. Closed sales are a flow, meaning the homes that change hands over time. When buyers absorb homes quickly, the count on any one day stays well below the number of sellers who came to market across the year. Utah agents have been reading that gap as a shortage.

The number of homes actually sold each year has moved through a normal cycle. Statewide sales of existing homes sat near 45,000 a year across 2016 to 2018, spiked to 53,401 in 2020, contracted to 35,007 in 2023, then rose 7.6% to 37,660 in 2024 (UtahRealEstate.com via Kem C. Gardner Policy Institute, July 2025). Salt Lake County sales climbed again in the second quarter of 2026. A campaign built on the idea that owners have stopped selling aims at a problem the data does not show. Owners in your county are already buying and selling. Build the campaign that makes you the name they already know on the day they decide to list.

What is actually happening across Utah’s housing market

Downtown Salt Lake City with the Wasatch Range behind it, the centre of Utah's largest county market
Salt Lake County holds about 1.24 million of Utah’s 3.55 million residents.

No single trend describes Utah.

Population, jobs, prices, construction and county sales counts each move on their own clock, and several of them moved in different directions at once in 2025 and 2026. An agent who picks a farm area or buys leads off one statewide number pays for activity that is happening in some other part of the state.

Utah’s growth slowed, and almost every county still gained

Utah’s population rose 1.26% in the year to July 1, 2025, after 1.46% in 2024 and 1.65% in 2023, and 24 of 29 counties grew (Utah Population Committee, Kem C. Gardner Policy Institute, December 2025). Tooele and Iron led at 3.0% each, while five ended the year with fewer residents: Daggett, Piute, Garfield, Wayne and San Juan. Summit County gained two people. Growth slowed for a second straight year while almost every county still added residents.

Net migration accounted for 19,233 of that gain, about 0.54% of Utah’s 3,551,150 residents. It cuts both ways for an agent’s pipeline. Departing households are listings and relocation business. Arriving households are buyers who need someone local.

Utah’s job growth is spread across industries, and some are shrinking

Utah employers added 26,300 jobs in the year to June 2026, up 1.5%, and unemployment sat at 3.6% once normal seasonal swings are stripped out (Utah Department of Workforce Services, June 2026). Professional and business services took 11,800 of those jobs, education and health services 5,800 and construction 3,400, while information shed 1,100 positions, manufacturing 400 and natural resources 300. Silicon Slopes, the tech corridor running south from Salt Lake City through Utah County, is not carrying this alone. The gains and the losses sit in different counties, so two Utah markets inside that one statewide figure can feel nothing alike. Utah ranked first among states in job growth from 2010 to 2024, up 47.5%, and second in population growth, up 26.8% (US Bureau of Labor Statistics and US Census Bureau).

Prices sit near their 2022 peak, and price growth has slowed

Utah’s median sales price across all housing types, the midpoint with half of sales closing above it and half below, was $506,500 in 2024, up 3.6% and just under the 2022 high of $510,000 (Kem C. Gardner Policy Institute, July 2025). That run from $355,000 in 2020 was 44%. Utah ranked ninth most expensive state for single-family homes in 2024, and the Federal Housing Finance Agency, which tracks prices by following repeat sales of the same houses, put Utah’s 1991 to 2024 increase at 651.1%, the largest of any state (NAR and FHFA, via Kem C. Gardner Policy Institute, July 2025).

Statewide price growth settled near 1% by early 2025. Salt Lake County’s median single-family price reached $645,000 in the second quarter of 2026, up 4.88%, with homes typically closing 2% to 3% below the asking price (Salt Lake Board of Realtors, 2026). Prices are holding near the 2022 peak, statewide growth is close to flat, and a Salt Lake County buyer still has room to negotiate.

Condos and townhomes are a record share of Utah sales and construction

Condominiums, townhomes and twin homes were 28% of Utah homes sold in 2024 and 28.5% of permitted units, both records through 2024, while single-family housing fell to 48.5% of permits against roughly three-quarters twenty years earlier (Kem C. Gardner Policy Institute, July 2025). Permitted units are the approvals builders pull from a city or county before construction starts, which is how the state counts the new housing on its way.

Construction moved through a full cycle. Total permits ran 40,144 units in 2021 and 21,966 in 2024, and apartments alone accounted for 9,683 permitted units in 2025, a total only 2021 and 2022 have beaten (2026 Economic Report to the Governor). A first-time buyer who cannot afford a detached house buys a condo or a townhome, then lists it and buys up five to eight years later.

The biggest sales gains came in Utah’s more affordable counties

The three largest 2024 sales increases among Utah’s larger counties came in affordable places next to expensive ones: Iron up 45.9%, Tooele up 20.5% and Box Elder up 14.8% (Kem C. Gardner Policy Institute, July 2025). The institute reads that as buyers willing to “drive till they qualify,” industry shorthand for moving further from the job center until the monthly payment fits what a lender will approve. Tooele and Iron sit on both lists, fastest population growth and biggest sales gains. Builders went the same way, pulling a rising share of their permits outside the metro counties.

Ten counties hold most of Utah’s population, and these are the places inside them.

CountyPopulation (July 1, 2025)Principal cities and communities
Salt Lake1,240,937Salt Lake City, West Valley City, West Jordan, Sandy, South Jordan
Utah765,515Provo, Orem, Lehi, Eagle Mountain, Saratoga Springs, American Fork
Davis381,339Layton, Bountiful, Clearfield, Kaysville, Syracuse, Farmington
Weber272,929Ogden, Roy, North Ogden, South Ogden, Riverdale
Washington209,129St. George, Washington, Hurricane, Ivins, Santa Clara
Cache145,865Logan, North Logan, Smithfield, Hyrum, Providence
Tooele84,320Tooele, Grantsville, Stansbury Park, Erda
Iron69,939Cedar City, Enoch, Parowan, Brian Head
Box Elder62,911Brigham City, Tremonton, Perry, Willard
Summit43,303Park City, Coalville, Kamas, Oakley

Table 1. Utah’s ten most populous counties and the principal cities and communities inside them. Population estimates as of July 1, 2025 (Utah Population Committee, Kem C. Gardner Policy Institute, December 2025).

Salt Lake County’s median kept climbing through 2026 while Daggett and Piute counties ended 2025 with fewer residents, and both describe the same state. A campaign built for Iron County, where sales rose by nearly half in 2024, and one built for Summit County, which added two residents, are not the same campaign. Check your county before you buy the lead.

ez Home Search works with a single partner in each Utah county. Before next year’s budget is set, find out whether yours is still unclaimed.

Most Utah buyers have a home to sell first

Most people buying a home in Utah are also selling one. The sale pays for the purchase, so they start shopping for the next house long before they list the one they own. Two common agent habits ignore that. One agent asks a vendor for listings. Another buys buyer leads. Each habit pays for half of one customer.

First-time buyers have fallen to 21% of purchases in the 2025 Profile of Home Buyers and Sellers from the National Association of Realtors, the lowest reading in a national series tracked since 1981, and the typical first-time buyer is 40. Roughly four in five buyers already own a home they must sell to buy the next one. The distinction matters. Look at one house in Sandy or Spanish Fork and you see two separate people, one selling and one buying. Across one household’s own move, that household does both jobs, selling the home it lives in and buying the next one within a few months.

Utah homeownership stands at 70.2% against a national 65.2% (US Census Bureau, 2024), so more Utah buyers come to a purchase with a home to sell. Younger renters keep the pipeline full. Utah’s population is 14.8% aged 25 to 34 against 13.5% nationally (US Census Bureau via the Kem C. Gardner Policy Institute, 2023), and one in three Utah renting households is headed by someone in that band (2026 Economic Report to the Governor).

Every Utah county holds three kinds of clients. First-timers need help with affordability and with how the process works. The largest group is buying and selling at the same time, and those clients need equity and timing handled as one move, because the sale funds the purchase and the closings have to line up. A small seller-only group covers estates and owners moving in with family.

An agent can watch for behavior that shows which side is live. A valuation check, an equity question, or a visit to a home-value page starts the seller conversation, because each one shows an owner pricing the house they already have. Saved searches, opened alerts, or a booked tour show the buyer side is active. Both signals come from the same person. For most households the two sides appear months apart, and ez Home Search reads that shift so the partner starts the right conversation on time.

The early stage of a move stays private. A Utah owner holding a mortgage under 5% thinks about the move for months or years before any agent hears about it. The agent who watches their own database catches that valuation check months earlier and earns both halves of the move from one client.

A statewide Utah average describes almost no local market

Two-story homes along the water in a Utah suburb, the kind of attached and detached stock driving county price gaps
Utah’s county medians ran from $250,000 to $1,635,000 in 2024.

Utah’s counties post very different prices, growth rates and sales results, so one statewide figure misleads almost every client who hears it. Summit County’s 2024 median single-family price was $1,635,000, with Wasatch County next behind it. Carbon County‘s median was $250,000. Across all housing types, the state came in at $506,500 (Kem C. Gardner Policy Institute, July 2025). A seller in Park City and a seller in Price both hear that state number as wrong about their own house. They are right.

Population splits just as widely across the state. Utah County added 15,914 residents in 2025, about 36% of everything Utah gained, and 60% of that came from births rather than from people moving in. Southwest Utah grew fastest at 2.38%, and 85% of that gain came from net migration rather than from births (Utah Population Committee, Kem C. Gardner Policy Institute, December 2025). Twenty-four of 29 counties added people. Five did not.

Two of those county figures deserve caution. Grand County’s 2024 median single-family price came in 13.9% below 2023, and Summit County’s population held flat in 2025 (Kem C. Gardner Policy Institute, July 2025; Utah Population Committee, December 2025). Both are single-year readings in small markets, where a handful of sales or one new building can swing the number. Neither is a trend. Neither belongs in a client conversation as one.

Those numbers change who an agent’s next client is. Each region’s next transaction starts with a different kind of person. Southwest Utah fills with people who have just arrived and know no local agent, so the first agent they meet carries unusual weight. Utah County’s growth comes from births, so the households who will list there already live there and can be reached today. Counties growing more slowly turn over inside an owner base that is already in place, so past clients and neighbors carry the pipeline.

The six regions below each run on a trend of their own.

RegionCountiesSourced trend
Wasatch FrontSalt Lake, Utah, Davis, WeberUtah County added the most residents of any county in 2025, 15,914, about 36% of all statewide growth, and 60% of that was natural change (Utah Population Committee, Kem C. Gardner Policy Institute, December 2025). Salt Lake County’s Q2 2026 median single-family price reached a record $645,000 on sales up 4.62% year over year (Salt Lake Board of Realtors, 2026).
Wasatch BackSummit, WasatchSummit and Wasatch are the state’s two most expensive markets. Summit County’s 2024 median single-family price was $1,635,000 and Wasatch County’s was $992,750. Summit’s population was flat in 2025, up two residents, while Wasatch grew 2.0% (Kem C. Gardner Policy Institute, July 2025; Utah Population Committee, Kem C. Gardner Policy Institute, December 2025).
Northern Utah and Cache ValleyCache, Box Elder, RichBox Elder existing home sales rose 14.8% in 2024, among the state’s largest increases, on a median single-family price of $449,900. Cache County grew 1.66% in 2025 to 145,865 residents (Kem C. Gardner Policy Institute, July 2025; Utah Population Committee, Kem C. Gardner Policy Institute, December 2025).
Southwest UtahWashington, Iron, Kane, Garfield, BeaverSouthwest Utah was the state’s fastest-growing region in 2025, up 2.38%, with 85% of that growth from net migration. Iron County posted the largest sales increase of any large county in 2024, up 45.9% (Utah Population Committee, Kem C. Gardner Policy Institute, December 2025; Kem C. Gardner Policy Institute, July 2025).
Uintah Basin and Castle CountryDuchesne, Uintah, Daggett, Carbon, EmeryThis region holds Utah’s most affordable housing. Carbon County’s 2024 median single-family price of $250,000 was the lowest in the state, and Uintah’s $330,000 changed least of any county, up 0.3%. Carbon added 160 permitted units in 2024, one of only seven counties with an increase over 100 (Kem C. Gardner Policy Institute, July 2025).
Central and Southeastern UtahSanpete, Sevier, Millard, Juab, Piute, Wayne, Grand, San JuanGrand County grew 2.11% in 2025 and posted the second-largest permit increase in the state, up 274 units on a single 184-unit apartment project, while its 2024 median single-family price came in 13.9% lower than 2023 at $525,000, the largest one-year price decline of any county in Utah (Utah Population Committee, Kem C. Gardner Policy Institute, December 2025; Kem C. Gardner Policy Institute, July 2025).

Table 2 lists Utah’s six regions and one sourced trend for each.

A Utah client wants their own region’s number. They can tell within a sentence whether you know it. The agent who has it wins the appointment against the one reciting the state median.

Two changes are reshaping the Salt Lake and Utah county line, and both have deadlines

Two changes are landing at once between southern Salt Lake County and northern Utah County. The school district that serves the fastest-building county in Utah is splitting into three separate districts, and a development on more than 600 acres of old state prison land is adding thousands of homes beside it. Both deadlines are fixed. An agent who starts these conversations in 2028 is late.

The corridor between the two counties is called Point of the Mountain. The development on the old prison land inside it carries a separate name, The Point.

The Point broke ground on Phase I on June 29, 2026, a $2.3 billion project on the former Utah State Prison site in Draper. Phase I carries more than 3,300 multifamily units, roughly 400 of them affordable, and the River District adds 800 to 900 owner-occupied homes, per the Point of the Mountain State Land Authority, the state agency that oversees the site. The first buildings are expected to open in 2028. Those homes become resale business for whoever is already the recognized name there.

Utah County voters chose at the November 2024 general election to break up Alpine School District, the largest in the state, and the three districts replacing it become operational July 1, 2027. A district split changes which schools a family’s children attend and which local tax rate pays for them, and two similar homes on opposite sides of a new line can sell for different prices because of it. One new district covers Eagle Mountain and Saratoga Springs, another covers Lehi, American Fork, Highland and Alpine, and a third covers the south end of the county. Boards were seated in November 2025 and the boundary maps were approved in March 2026, per KSL, KUER and the Salt Lake Tribune. The three districts still go by working names.

Both changes land on the same cities. Eagle Mountain, Saratoga Springs and Lehi permitted 3,946 residential units in 2024, 18% of every residential unit permitted in Utah that year and the highest share on record, with Eagle Mountain first in the state at 1,556 units, per the Kem C. Gardner Policy Institute (July 2025).

Every family buying in these cities faces that school question on a deadline. ez Home Search publishes school and real estate reports from the state down through the county, the district and the individual school, with an ez rating on every school and prices by ZIP and neighborhood inside a district. Those dates are public. The agent who has been answering the question for years before July 1, 2027 is the one these families call.

Utah taxes the same house two different ways, and most agents never bring it up

Utah taxes a house its owner lives in on 55% of market value and a second home on 100%, at the same rate, because the primary residential exemption in Utah Code 59-2-103 removes 45% of the home’s fair market value from the taxable base. Occupancy decides which applies. The Utah State Tax Commission sets the test at 183 consecutive days as a primary domicile, one exemption per household statewide. Second homes, cabins, vacation properties and short-term rentals do not qualify. A long-term rental qualifies when the tenant lives there as their primary residence.

The Utah State Tax Commission calls the system Truth in Taxation: each taxing entity’s certified tax rate, the rate that funds its budget, is recalculated annually to collect the prior year’s revenue plus revenue from new construction. Rates fall as values rise.

Dejan Eskic and Moira Dillow of the Kem C. Gardner Policy Institute measured short-term rentals at 1.9% of Utah’s residential units in 2023. The October 2024 study broke shares by place. Park City stood at 41.7% of housing units, unincorporated Summit County at 25.7%, Grand County at 18.7%, Washington County at 4.3% and Salt Lake County at 1.1%. Summit, Salt Lake and Washington counties together held over 60% of every short-term rental listing in the state. Eskic cautioned that short-term rentals are “a piece of it, but it’s not the main piece” of affordability, and that most Summit County units were likely second homes already.

Second homes are common in Summit, Wasatch, Washington, Grand, Kane and Rich counties, where a real share of the stock belongs to owners who live elsewhere. No local agent is farming them. Exemption status sits on the parcel record at the county assessor’s office, beside the mailing address the tax notice goes to. An agent can pull it without buying anything. One question opens the conversation: whether the house carries the exemption, and what the bill does if its use changes. ez Home Search publishes property-tax data by state, county, city and ZIP, and a rising tax bill holds down the sale price because the buyer carries it on top of the mortgage. Those owner names are public, and the agent who pulls the list gets the first conversation with people nobody else is calling.

Remote work still drives demand in Utah’s smaller counties

The Welcome to Utah highway sign against red rock, marking the state line remote buyers cross
Rural Utah counties took 17.1% of the state’s permitted homes in 2024.

Remote and hybrid work did not go away. The share of Americans who telework, meaning they work from home at least part of the week, has not fallen back. That holds buyer demand in place in the Utah counties people move to for space and price. The US Bureau of Labor Statistics counted 36.7 million teleworkers in the fourth quarter of 2024, 23.4% of everyone employed, up from 32.5 million and 20.7% a year earlier. Employers at roughly 150,000 businesses told the US Census Bureau they expect as much work from home five years out as they have now. Both figures are national.

Utah’s building permits mark the destination. Rural counties, meaning everything outside Utah’s nine metro counties, took 17.1% of the state’s permitted residential units in 2024, up from 11.8% in 2021 (Kem C. Gardner Policy Institute, July 2025). Builders put the housing where the buyers went. Tooele, Iron, Washington, Grand, Wasatch and Cache counties all grew faster than Utah as a whole in 2025 (Utah Population Committee, December 2025).

One Utah law makes those markets easier to work. An internal accessory dwelling unit is a self-contained apartment built inside an existing house, usually in the basement. Utah Code 10-9a-530, created by HB 82 in 2021, requires cities to allow at least one inside a detached single-family home in most residential zones. It fits inside the walls the house already has, and it rents to tenants staying 30 consecutive days or more. Cities keep limits. They may require the owner to live in the house, add one off-street parking stall, and exclude up to 25% of their residential land (Utah Legislature; Utah League of Cities and Towns).

Remote buyers in these counties shop a short list: an office with a door that closes, more space than the same money buys along the Wasatch Front, the Ogden to Provo corridor where most Utahns live, and internet fast enough for video calls all day. Two seller conversations follow. Ask any owner in Tooele, Iron or Box Elder County what a basement unit, legal in most Utah cities under HB 82, adds to their appraisal. Then ask every seller with a spare bedroom whether it is staged as an office, because in these counties the office sells the house.

What Utah agents do for listings now, and what each approach costs to keep running

Most Utah agents run four or five of the approaches below. Each produces business, and each carries a bill.

Shared leads from legacy real estate portals produce real volume. One name reaches several agents at once. The consumer chose none of them. An IDX website, the feed that puts live MLS listings on an agent’s own site, is genuinely useful, and it pays off slowly. It needs traffic the agent buys or earns, it competes for the same Utah keywords as national platforms spending far more, and upkeep lands on the agent’s week.

Cold calls work for operators who run them relentlessly. Lists of homes for sale by owner, the FSBO lists, work the same way, and so do expired listings and circle prospecting, where an agent calls every homeowner around a recent sale. Each carries consent-proof exposure that few agents price. Predictive-seller scoring, software that ranks a database by who it guesses will sell, narrows the list. A high score is not a relationship.

Generic all-in-one CRMs are capable. The agent administers them, and the upkeep sits on the team’s calendar. A past client does not return to a CRM on their own. DIY content and paid ads produce while they stay funded and staffed. Geographic farming comes closest to what Utah’s structure rewards, and it is capped at what one person can mail and doorknock, a neighborhood rather than a county.

Utah adds its own friction. Agents here often prospect against a scarcity story the state’s data does not support. The relationship that wins a listing starts long before the owner decides to sell, because more than seven in ten Utah borrowers hold a mortgage under 5% and will weigh that rate before they move. Affordability moves clients from Salt Lake into Tooele and Washington into Iron. St. George, Park City and Heber leak second-home and relocation business to agents in other states.

ez Home Search runs a different structure. One partner holds a county, nothing is billed per lead, and no commission is split. The connection exists because the consumer chose a single vetted local expert rather than because an agent outbid someone, and those opportunities convert in 30 to 60 days.

Consent is where prospecting gets expensive. Under federal law an agent prospecting by phone or by text counts as a telemarketer. If the person called later disputes ever having agreed to hear from anyone, a private suit puts the burden on the caller to show proof for every number dialed. Do Not Call complaints to the FTC passed 2.6 million in fiscal year 2025. A call or text without that proof is worth $500 to the person on the other end, $1,500 if a court finds the violation willful, and there is no ceiling on the total. Those are national numbers. On an ez Home Search opportunity that work is already done. ezVerify.ai establishes the opt-in and keeps the proof of it on record. It runs each number against a known-litigator database, drops anything sitting on the Do Not Call registry, then completes the contact record before the agent dials. The agent makes the call with that exposure already removed.

None of it is complicated. Every item on that list has an owner, and for most Utah agents it is you: the traffic, the weekly content, the site, the data, the proof of consent, and all of it again next month.

ez Home Search runs that entire stack for one partner per Utah county, and you can check whether yours is still open.

The Utah counties most agents never work

Aerial view of a small Utah lakeside community with waterfront homes and boat moorings
In a county closing a few hundred homes a year, one name can own the market.

Utah has 29 counties, and agent marketing concentrates on six or seven. The rest run real housing markets a business can be built on. The state’s own research institute publishes the numbers. Most agents never look.

An agent builds the recognized name with one platform and one weekly follow-up routine, and that cost holds whether a market closes a few hundred homes a year or several thousand. What changes is the denominator. The same routine covers a small county and only a sliver of the Wasatch Front, and that share is what shows up in revenue.

Carbon County posted Utah’s lowest median single-family price in 2024, $250,000, and permits there went from 57 units in 2023 to 217 the next year. Uintah County closed 283 single-family transactions at $330,000, the smallest one-year price change in the state (Kem C. Gardner Policy Institute, July 2025). Steadiness like that can be planned against.

Sanpete, Sevier, Millard and Juab run their own corridor through central Utah. Moab anchors Grand County to the south.

Every one of these holds named towns where Utah households live and eventually list. None of it is guesswork. An agent can check their own against the table below.

CountyPopulation (2025)Communities
Sanpete31,454Ephraim, Manti, Mount Pleasant, Gunnison
Sevier22,118Richfield, Salina, Monroe, Aurora
Carbon20,539Price, Helper, Wellington, East Carbon
Duchesne20,266Roosevelt, Duchesne, Myton, Altamont
Uintah36,634Vernal, Naples, Ballard, Jensen
San Juan14,998Blanding, Monticello, Bluff, Mexican Hat
Grand10,105Moab, Castle Valley, Spanish Valley, Thompson Springs
Millard13,715Delta, Fillmore, Hinckley, Oak City
Juab13,364Nephi, Mona, Levan, Eureka
Kane8,481Kanab, Orderville, Glendale, Big Water
Wasatch39,588Heber City, Midway, Charleston, Hideout
Morgan13,341Morgan, Mountain Green, Croydon, Peterson

Utah counties beyond the largest metro markets, with communities in each. Population estimates are for July 1, 2025 (Utah Population Committee, Kem C. Gardner Policy Institute, December 2025).

Salt Lake County recorded 8,339 single-family sales in 2024. Carbon County recorded 225 (Kem C. Gardner Policy Institute, July 2025). Recognition costs the same in both places and returns a far larger share of the smaller one. Each of these markets is still open to whoever decides to be its known name.

What an Exclusive County Partnership gives a Utah agent

One agent, team or brokerage becomes the only ez Home Search partner in an entire Utah county, and no second partner ever operates inside that territory. That county’s residents already use the home search, the listing alerts, the home value updates, the local market reports, and every one of them carries the agent’s name alongside ez Home Search’s. The partner pays one predictable fee, with nothing per lead and no share of a closing, so a heavy month lands in their income rather than on their invoice.

The person who reaches that partner already trusts the platform, and their activity there has shown real intent. The partner opens the first conversation knowing the neighborhoods that person searched, the price range they kept landing on, and the homes they kept reopening. Two promises earn that trust, the Single Local Expert and The Only Confidential Home Search, and through them ez Home Search delivers on A Better Way To Discover Real Estate. ez Home Search does not sell, resell, recycle or broadcast that person’s contact details and budget across a list of businesses they never asked to hear from. Their information does go somewhere, and they know where: to the one vetted local expert serving their county.

The bigger return is already sitting in the partner’s own database. Reactivation means getting past clients and sphere back into contact and back into transactions, and most agents leave it alone. Under an ez Home Search partner, reactivation hits 2.5 to 5 times the market rate. Multiply that against the base an agent already has. Repeat and referral run roughly 41% of an agent’s business across all agents, and more leaks away: 88% to 92% of buyers would hire their agent a second time, and about 18% actually do.

Utah gives that asset a long shelf life. The Kem C. Gardner Policy Institute puts more than 70% of Utah mortgage borrowers below 5%, and an owner sitting on a rate like that is years away from listing. Contact details decay in the meantime. Email addresses go stale at 15% to 22% a year, and up to one in ten people swap a phone number. The search carrying the partner’s name captures each new address and number as those clients return.

A past client who moves away takes a local listing with them unless the partner sees it coming. Census figures put interstate moves at about 2.1% of Americans a year, with roughly another 3% relocating to a different county without leaving the state. In Utah that math has addresses. The Salt Lake County client priced into Tooele searches that market long before anyone hears about it, and so does the Park City owner shopping a second home. Those searches surface on the partner’s platform as an early signal, and the local listing stays with the agent who earned it.

One partner becomes the county’s recognized name, and recognition settles more listings than agents expect. National Association of Realtors research finds 81% of sellers contact a single agent and 77% of repeat buyers interview a single one, with reputation ranking first for 35% of sellers. Most Utah sellers decide before they compare.

Every conversion tool behind this is built and running under the partner’s name, including the automated follow-up that fires when a contact picks a search back up. The partner builds none of it and runs none of it. Their hours go where only their hours can go, across the table from a Utah family making the biggest financial decision of their lives.

Only one agent can hold each Utah county

ez Home Search partners with one agent, team, or brokerage in each Utah county, and that partner is the only one the platform works with inside those county lines. The position holds for as long as the partnership runs. No second partner is added later, and no competing partner is placed alongside the first. Demand for county exclusivity runs ahead of the 29 counties Utah has, so many are held and more are taken as time passes.

Salt Lake County and Sanpete County sit at opposite ends of Utah’s transaction volume, and one partner holds each of them on the same terms. The known local name does the same work in a small county that it does in a large one. On the Wasatch Front, a single county covers a market deep enough to build a team around. In a rural county, that same position reaches a large share of the households who will move there.

The platform is built and running before any partner signs, and millions of people already use it. A new partner launches nothing. The partner’s brand goes onto a home search that works on day one, and the county position starts producing from there. ez Home Search runs the search itself, the listing alerts, the valuation updates, and the follow-up beneath that partner’s name.

One agent holds each Utah county, and the day that agent signs, the county is off the table for every other agent in the state.

Choosing how to spend the next twelve months in Utah

Three ways to spend the next twelve months sit in front of a Utah agent. Each carries a different bill.

You can keep buying shared leads. The name you pay for lands in several inboxes at once, and the consumer chose none of you.

You can build the whole thing yourself. That means the search experience, the valuation data, the listing alerts, the market reports and the weekly follow-up that has to keep running for years, a stack that costs millions to assemble and keep alive; in the marketing technology rollouts I have specified for organizations that serve real estate professionals, the valuation data is where the budget breaks.

You can hold one Utah county on ez Home Search, where one agent, team or brokerage carries the county co-branded through the consumer experience and no competing partner works the same households. The consumer traffic and the relationships are already in place, the fee is flat rather than billed by the lead or taken out of the closing, and reactivation of past clients through repeat business and referral clears 2.5 to 5 times the market rate on that database.

The cost is time. Relationships set the pace here, and nothing arrives on demand. An opportunity converts in 30 to 60 days rather than the week it lands, and a reactivated database pays out across years rather than inside one quarter. An agent who needs closings this week should buy something faster.

Check whether your Utah county is still open.

The people who will list in Utah already live here. The only question is whose name is on the search they already use.

Frequently asked questions

Does Utah really have too few homes for sale?

No. A single day’s count misses most of the year’s sellers, because homes sell and get replaced faster than the screen refreshes. Average monthly active listings reached 8,800 in 2024, the highest level since 2016 (UtahRealEstate.com via the Kem C. Gardner Policy Institute, July 2025). Median days on market ran 34 against a 44-day long-term average, so homes clear fast and new ones replace them. Gardner described the same gap in 2018, so treat it as the standing Utah pattern. Prospect the owners who are transacting.

Utah’s growth now comes more from births than from people moving in. What does that change about how I generate leads?

It moves your spend toward the households already in your market instead of newcomers. Utah added 44,351 residents in the year to July 1, 2025, and 57% of that came from natural change rather than net migration, the first time this decade (Utah Population Committee, Kem C. Gardner Policy Institute, December 2025). Babies do not buy houses, but the families raising them outgrow their house and move up later. Work your database, your past clients and the neighborhoods you already serve.

How do I keep a Salt Lake County client who is getting priced out into Tooele County?

You follow that client into Tooele County instead of handing them to another agent. Tooele County posted 20.5% sales growth in 2024 (Kem C. Gardner Policy Institute, July 2025) and 3.0% population growth in 2025 (Utah Population Committee, December 2025), so learn Tooele City, Grantsville and Stansbury Park well enough to price a house in each. The larger risk sits at the other end of the move: whoever sells the Salt Lake County home they are leaving takes the listing side of the same deal. ez Home Search covers the whole country on your co-branded search, so a client searching Tooele addresses still reaches you first.

Are Iron and Tooele counties worth working, or is the volume still in Salt Lake and Utah counties?

Both are worth working, for different reasons. Salt Lake County closed 2,334 single-family sales in the second quarter of 2026 at a record $645,000 median (Salt Lake Board of Realtors, July 2026), so the volume still sits on the Wasatch Front. Iron County sales rose 45.9% in 2024 and Tooele 20.5%, the two largest increases in the state (Kem C. Gardner Policy Institute, July 2025). You can become a known name in Cedar City for a fraction of what the same recognition costs you in Sandy.

How does Utah’s primary residential exemption change the conversation with an owner thinking about turning a house into a rental or a second home?

The tax rate on the house does not change, but the share of its value that gets taxed does. Utah Code 59-2-103 removes 45% of fair market value from the taxable base on a qualifying primary residence, so that home is taxed on 55% of its value. A second home or a short-term rental gets no exemption and is taxed on 100% at the same rate (Utah State Tax Commission). A long-term rental still qualifies when the tenant lives there as their primary residence. Run the bill both ways before the owner decides.

Eagle Mountain, Saratoga Springs and Lehi are building faster than anywhere else in Utah. How does an established agent compete in a city that is mostly new construction?

The builder captures the first sale on a new house, so your business is the resale and everything after it. Those three cities permitted 3,946 residential units in 2024, 18% of every unit permitted in the state that year and the highest share on record, led by Eagle Mountain at 1,556 (Kem C. Gardner Policy Institute, July 2025). Utah County voters also split Alpine School District in November 2024, and it dissolves into three districts on July 1, 2027. Every family there will ask which district covers their address, and the agent who can answer gets the appointment.

With more than seven in ten Utah owners holding a mortgage under 5%, how do I start a listing conversation that does not die on the rate?

Open on their equity and on what the next house costs, because the owner is deciding whether to move rather than whether to refinance. Life events set the timing. Utah sales rose 7.6% in 2024 with those low rates already in place (Kem C. Gardner Policy Institute, July 2025), which is the state’s own evidence that a cheap mortgage does not stop a move. ez Home Search puts home-value updates and market reports in front of them under your name for that stretch.

Nearly three in ten Utah homes sold are condos, townhomes or twin homes. How do I turn that first-time attached-housing buyer into a move-up listing later?

The equity that buyer builds in a condo or townhome becomes the down payment on their next house, so stay in front of them until they are ready to spend it. Condominiums, townhomes and twin homes were 28% of Utah sales in 2024, the highest share on record (Kem C. Gardner Policy Institute, July 2025), and that buyer becomes a move-up seller in five to eight years. Send them their home value every month. ez Home Search shows you, under your own brand, the moment a past client reopens a search or runs a second valuation.

08.21.2026

Puerto Rico Real Estate Leads: Reaching Owners Who Rarely Move

Puerto Rico has averaged about 10,700 home sales a year since 2014, according to the Office of the Commissioner of Financial Institutions. Census figures for 2020 to 2024 put the island at 1,290,866 households with 67.9% of them owner-occupied, which works out to roughly 876,000 owner households. Divide one into the other and fewer than two owners in a hundred sell in a given year.

Every agent on the island is competing for those two. Almost nobody is working the other ninety-eight. That is why most sources of Puerto Rico real estate leads underperform here: they find people who are already shopping, and on this island almost nobody is.

Rising prices in Puerto Rico have not produced more sales

Volume has not followed price at any point in the last decade. The Office of the Commissioner of Financial Institutions, or OCIF, recorded 11,259 units in 2022, 10,811 in 2023, and 9,995 in 2024, a three-year step down of 17%, 4%, and 7.5% off the stimulus-era peak, then a 2.5% recovery to 10,247 units worth $2.44 billion in 2025. The Federal Housing Finance Agency’s purchase-only index, over that same stretch, rose 14.95% year over year in the fourth quarter of 2025 and 13.41% in that quarter alone. The price line is steep. The volume line is nearly flat.

Residential foreclosures fell 41.6% to 684 units in 2025, after falling 49.4% across 2024. Existing homes made up 92.0% of all transactions in 2025. No single industry carries the payrolls underneath any of it: BLS nonfarm figures for November 2025 put Government at 198,500 jobs, Trade, Transportation and Utilities at 192,900, and Professional and Business Services at 135,900, against a labor force near 1.239 million. DDEC’s 2025 profiles credit pharmaceuticals with 76.6% of exports and tourism with more than 68,000 jobs.

Most market commentary misses that steadiness because it runs two different measures together. Volume is a flow, the count of deals closed over a period. Inventory is a stock, the homes listed at one moment. A tight inventory number says nothing about how many homes changed hands, and the two get read as the same signal constantly.

Why a rate cut will not shake a single listing loose in Puerto Rico

A chart with a message saying no specific statistical data or charts can be generated from the article about Puerto Rico real estate leads due to lack of precise numerical data or structured tables.

Half of Puerto Rico’s mortgage-free homeowners carry $180 a month or less in owner costs, counting property taxes, insurance, utilities, and any association fees, per the Census Bureau’s 2020 to 2024 American Community Survey. The national median on the same measure is $638. That figure is the most important number on this page for anyone trying to generate seller leads. An owner at $180 a month has no payment to escape, no refinance to chase, and no rate headline that means anything to them.

OCIF puts commercial bank loans secured by family residential property at $11.20 billion at the end of 2025, against $14.39 billion in 2015. Mortgage debt has been draining out of Puerto Rico homeownership for a decade, leaving an owner base with deep equity and almost no carrying cost.

The same Census survey puts owner-occupancy at 67.9% against 65.2% nationally, 94.1% of residents in the same home as a year earlier against roughly 87% nationally, and 26.0% of the population aged 65 and over against roughly 18% nationally. Older, settled, and paid off is a profile that does not respond to market timing.

These owners still move, and the trigger is never the rate. A parent dies and the house passes to three siblings. A couple in their seventies decides the stairs have become a problem. A child gets to a down payment and the parents help. A second property in Cabo Rojo turns from a pleasure into an errand. ez Home Search puts the share of people actively buying or selling at 5% to 10% at any moment, and Puerto Rico sits at the low end of that range. The agent who shows up when the life event lands is the agent who was already there for years.

That is a multi-year position, and it becomes available one municipio at a time. Check whether yours is still open.

The agent who works listings only is forfeiting four clients in five

The National Association of Realtors put first-time buyers at 21% of purchases in the 2025 edition of its Profile of Home Buyers and Sellers, and that is the lowest share since the survey began tracking in 1981. It is a national figure and no clean Puerto Rico equivalent exists, so read it as the anchor it is. Roughly four out of five people buying a home are selling one as part of the same move.

Most agents run those two halves as separate campaigns anyway. One markets “list with me” to owners. The other buys buyer leads. Both are talking to the same person at different points in one move, and the agent who only farms for listings meets that person eighteen months late, after some buyer’s agent has already earned the listing.

Puerto Rico’s own numbers push the point harder than the national ones do. An owner base at 67.9% ownership that stays in place at 94.1% a year does not produce many pure sellers. When someone here finally moves, they are almost always selling and buying in a single act, which means the listing and the purchase were decided together, months before either one showed up as activity.

On any one home the buyer and the seller are different people. Across a move, they are usually the same person, and the sequence runs buy-side first: dreaming, gathering numbers, then planning, long before anything looks like a transaction. ez Home Search reads which side is live from real behavior. A valuation checked twice means the seller conversation is open. Saved searches and opened alerts mean the buy side is moving. The automated valuation model, an AVM, keeps a current number in front of an owner every month, so a quiet browser becomes a listing two years out with the same partner holding both ends.

Which municipio you hold decides whether you work one market or five

Puerto Rico has 78 municipios, the Census Bureau treats each one as a county equivalent, and some of them sit against five neighbors while others stand alone. ez Home Search covers 3,144 counties and county equivalents, so the Exclusive County Partnership here assigns one partner per municipio. One more thing trips up mainland readers: a municipio and its seat almost always share a name, so Ponce the city sits inside Ponce the municipio.

MunicipioPopulation, US Census Bureau estimateSeatCommunities
San Juan332,454San JuanOld San Juan, Condado, Santurce, Hato Rey, Río Piedras
Bayamón181,152BayamónSanta Juanita, Hermanas Dávila
Carolina150,679CarolinaIsla Verde, Country Club, Villa Carolina
Ponce129,659PoncePonce Playa, La Guancha, Villa Flores
Caguas124,628CaguasTurabo, Bairoa, Borinquen
Guaynabo89,405GuaynaboGarden Hills, Torrimar, Frailes
Arecibo85,971AreciboHato Arriba, Islote, Sabana Hoyos
Toa Baja71,332Toa BajaLevittown, Sabana Seca, Candelaria
Mayagüez69,044MayagüezSultana, Guanajibo, Algarrobos
Trujillo Alto66,816Trujillo AltoLa Gloria, Carraízo

San Juan, Bayamón, Carolina, Caguas, Guaynabo, and Trujillo Alto sit inside one continuous metropolitan area. A partner holding any one of them works a dense position with the next municipio a few minutes away, and buyers cross those lines all day for work and schools without thinking about it. Ponce, Arecibo, and Mayagüez are the opposite case. Each anchors its own region with no comparable market next door, which makes the recognized name there harder to challenge and slower to lose.

Brightly colored hillside houses above the surf in La Perla, San Juan, Puerto Rico
San Juan and its neighboring municipios hold the densest concentration of households on the island.

One island, six markets that do not share a playbook

The Puerto Rico Tourism Company sorts all 78 municipios into six regions, and the Census numbers behind them describe six different demand pictures. Porta Capital is the San Juan metro. Porta Atlántico runs the north coast, Porta del Sol the west in a north and a south group, Porta Caribe the south, Porta del Mar the east and the offshore municipios, and Porta Cordillera the central mountains.

RegionMunicipiosWhat the Census data shows
Porta Capital (metro)10, including San Juan, Bayamón, Carolina, Caguas, Guaynabo, Trujillo Alto, CatañoSix of the ten most populous municipios sit here
Porta Atlántico (north coast)11, including Arecibo, Toa Baja, Vega Baja, Dorado, Manatí, Toa AltaArecibo at 85,971 and Toa Baja at 71,332 rank in the ten largest; Vega Baja at 53,709 and Dorado at 35,867 carry the rest of the corridor
Porta del Sol (west)19, including Mayagüez, Aguadilla, Rincón, Isabela, Cabo Rojo, Aguada, Moca, San GermánRincón grew from 15,187 residents in the 2020 Census to 15,625 by July 2024, with smaller gains in Isabela and Moca
Porta Caribe (south)11, including Ponce, Juana Díaz, Guayama, Salinas, Coamo, Santa IsabelPonce at 129,659 is the largest municipio outside the metro
Porta del Mar (east and offshore)15, including Humacao, Fajardo, Río Grande, Luquillo, Naguabo, Vieques, CulebraNo municipio in the ten largest; Humacao at 49,616 leads it, and Vieques and Culebra are reached by ferry or air
Porta Cordillera (central mountains)12, including Utuado, Jayuya, Adjuntas, Orocovis, Barranquitas, Aibonito, ComeríoNo municipio in the ten largest, and three of the island’s few gainers sit here: Barranquitas, Naranjito, Aibonito

Six of the ten most populous municipios are in Porta Capital, while every municipio that added residents between the 2020 Census and the July 2024 estimates sits in the west or the mountains. The volume is in the metro and the movement is not. Puerto Rico’s population fell over that period, driven mainly by natural decrease: Census components of change for 2024 to 2025 show deaths outnumbering births by roughly 14,900, several times the size of the net migration figure.

A partner in Guaynabo and a partner in Aibonito are running two different businesses. One works a market where buyers arrive from three adjacent municipios and price levels sit far above the island’s $131,500 median owner-occupied value. The other works a market of under 25,000 residents where an arriving household is a meaningful event and the settled owner of thirty years is the listing. Neither is served by the same prospecting calendar or the same script.

A reservoir winding between forested hills in Puerto Rico's central mountain municipios
Porta Cordillera, the central mountain region, behaves nothing like the San Juan metro.

A small municipio takes less to own and gives it back longer

Sixty-eight of Puerto Rico’s 78 municipios sit outside the ten largest, and an exclusive position pays back faster in those than anywhere on the island. Utuado and Aibonito each hold fewer residents than one large mainland suburb, so the number of households a partner has to reach before they are the name people think of runs to a few tens of thousands, not a few hundred thousand.

MunicipioPopulation, US Census Bureau estimateRegionCommunities
Vega Baja53,709Porta AtlánticoPuerto Nuevo, Cabo Caribe, Almirante Norte
Humacao49,616Porta del MarPalmas del Mar, Punta Santiago, Buena Vista
Cabo Rojo46,820Porta del SolBoquerón, Joyuda, Puerto Real
Juana Díaz46,045Porta CaribeSabana Llana, Guayabal, Collores
Isabela43,033Porta del SolJobos, Bajura, Guerrero
Dorado35,867Porta AtlánticoDorado Beach, Higuillar, Mameyal
Fajardo31,043Porta del MarPuerto Real, Sardinera, Las Croabas
Utuado27,155Porta CordilleraCaguana, Don Alonso, Ángeles
Aibonito24,751Porta CordilleraAsomante, Llanos, Robles
Rincón15,625Porta del SolPuntas, Córcega, Ensenada

ez Home Search built the Exclusive County Partnership to work the same way in large metros, mid-sized markets, and rural areas, because the name an owner already knows decides the listing at any scale. What changes is the cost of earning it. In San Juan an agent competes for attention against everyone else on the island. In Aibonito the position belongs to whoever holds it and does the work.

Six municipios recorded population gains between the 2020 Census and the July 2024 estimates: Rincón, up 2.9% from 15,187 to 15,625, with smaller gains in Isabela, Moca, Barranquitas, Naranjito, and Aibonito. Three of the six are in the table above. Those are small numbers, and they land differently at small scale, because an arriving household in a municipio of 20,000 changes the local market in a way the same household never would in Bayamón.

The mistake is reading a small municipio as a small opportunity. Where fewer than two owners in a hundred sell in a given year, a territory earns its value across a decade of the same name reaching the same owners. Twelve months of transactions is the wrong measuring stick.

Homes set along a green hillside above a calm lake in Puerto Rico, typical of the island's smaller municipios
In a municipio of 25,000 residents, becoming the recognized local name costs a fraction of what it costs in a metro.

Remote work did not die, and it is buying homes in Rincón

In the fourth quarter of 2024, 36.7 million Americans worked at least partly from home, per the Bureau of Labor Statistics, against 32.5 million in the same quarter a year before, and the national telework rate climbed from 20.7% to 23.4% over those twelve months. A Census Bureau survey covering about 150,000 US firms, fielded from November 2024 through January 2025, found 31.2% had someone working a full day from home, and those employers projected the same level five years out. Both figures are national. Headlines calling remote work finished are measuring against spring 2020 instead of against the years before it.

Puerto Rico converts that trend into buyers for a reason that is legal rather than promotional. Puerto Rico is a US jurisdiction, so someone employed by a mainland company can move there and stay on US payroll, keep US banking, and hold professional licenses that still apply. Census figures for 2020 to 2024 put 80.6% of Puerto Rico households on a broadband subscription.

Porta del Sol holds the west coast municipios this buyer looks at first, including Rincón, Isabela, Cabo Rojo, and Aguadilla. Porta del Mar holds the east, including Humacao and Palmas del Mar, Fajardo, and the offshore municipios of Vieques and Culebra. Porta Cordillera holds the mountain municipios, where the same buyer trades ocean access for land. Rincón is where the pattern already shows up in Census data rather than in anecdote.

An agent who knows what this buyer needs can qualify one on a single call. The office comes first, either a room that closes or an accessory dwelling unit, meaning a small second structure on the same lot. Square footage matters next, because a mainland salary buys more of it here. Generator and solar backup come up early, since the work does not pause when the power does. Broadband is the question that ends showings, so bring a tested answer to the tour rather than the number on the listing sheet.

Most agents on the island are not working this buyer at all, which is exactly why the position is available. It takes one conversation to find out whether your municipio is still open.

Umbrellas and lounge chairs on a palm-lined Puerto Rico beach in the Porta del Sol region
The west coast municipios of Porta del Sol are where remote and hybrid buyers look first.

Mainland arrivals come for the tax treatment and stay for something else

Pew Research Center’s analysis of Census American Community Survey and Puerto Rico Community Survey data found 38,486 people moving from the mainland to Puerto Rico in 2024, against 25,151 moving the other way, a net gain of 13,335. Set the arrivals against roughly 10,700 homes sold in an average year and the inbound flow runs more than three and a half times the island’s entire annual transaction count. The caveats matter: that counts people rather than households, many arrivals rent for a year or more, and a meaningful share are Puerto Ricans coming home. Across the twenty years from 2005 to 2024 the series runs the other direction, toward the mainland, so 2024 is one year inside a long trend and the 25,151 departures are listings in somebody’s market.

Section 933 of the Internal Revenue Code is the federal mechanism, and it is broader than most agents realize. A bona fide resident of Puerto Rico excludes Puerto Rico-source income from US federal gross income, and that applies to bona fide residents generally, not only to people holding a tax decree. The Section 937(a) tests are 183 days of physical presence in the tax year, no tax home outside Puerto Rico, and no closer connection to the United States or a foreign country. Whether a remote worker’s services income counts as Puerto Rico-source is the piece the IRS examines most closely, per Holland & Knight’s November 2025 analysis, and IRS Publication 1321 covers the exclusion itself.

Act 60 is the narrower instrument, a Puerto Rico decree layered on top. It sets 0% on passive income for existing decree holders and 4% for new applicants, and the legislature extended it through December 31, 2055. The requirement an agent should know: a decree holder has to show evidence of buying Puerto Rico real estate as a primary residence within two years of receiving the decree. More than 4,000 grandfathered holders against an owner base near 876,000 households is half a percent, concentrated in Dorado, Guaynabo, Condado, Palmas del Mar, and Rincón. Residency and income-sourcing questions belong with a Puerto Rico tax attorney or CPA.

Every competing page stops at the tax math, and that is where it gets the buyer wrong. Cody Hilbun, a friend of mine from CEO Netweavers, moved his family to Puerto Rico for the tax treatment and still runs Bespoke Capital from there. What he brings up is the community around him and the life his family has built there. I have watched more than dozen friends and colleagues make this same move, and the story repeats every time.

An arriving buyer treated as a transaction closes once and disappears. Treated as a new long-term resident, the same person becomes a repeat client, a second-property buyer, the name their colleagues call when they weigh the same move, and eventually a seller and a buyer again. The commission on the first purchase is the smallest piece of that relationship.

High-rise condominium buildings beside the water in Puerto Rico
Arriving buyers concentrate in a handful of municipios, including Dorado, Guaynabo, and Condado.

Three things stall Puerto Rico closings that no mainland agent has handled

The Financial Oversight and Management Board for Puerto Rico reported in May 2023 that CRIM, the Centro de Recaudación de Ingresos Municipales, had notified roughly 240,000 properties that were not properly registered, a step it projected would add about $90 million a year in municipal revenue. The same Board recorded about $217 million in past-due property taxes collected under CRIM’s fiscal 2022 relief program. As of that 2023 reporting, a large share of the island’s housing stock carried a registry problem, and at the listing appointment that means an unrecorded addition, a second structure, or a pool can surface mid-sale and put the closing date in question.

Puerto Rico tax practitioners consistently describe assessed values as anchored to a 1957 valuation baseline, with structures built after 1957 assessed as though built then. That is practitioner consensus and it is presented here as consensus, because no single government publication states it outright. The consequence is what an agent can use: on the mainland, a reassessment notice landing in a homeowner’s mail is one of the most dependable listing conversations of the year, and in Puerto Rico that trigger does not exist. Nothing in the tax system tells a Puerto Rico owner what their home is worth.

A Puerto Rico government estimate reported in 2018 put more than half of the island’s houses in the informal category, meaning built without permits and lacking clear title, and the Puerto Rico Department of Housing runs a federally funded Title Clearance Program that registers rightful owners in the Property Registry. Treat that as workflow. A seller may need succession filings and title work finished before the home can transfer, and the agent who raises it at the listing appointment looks like a professional while the agent who finds it during escrow looks like a problem.

The Federal Housing Finance Agency publishes one house price index for all of Puerto Rico rather than a series per metro, which San Juan, Ponce, and Mayagüez all share. An owner in Isabela who asks what homes in Isabela have done over five years cannot be answered from a federal figure, because no federal figure for Isabela exists. That answer comes from local transaction data and a valuation built on it, which is the part an individual agent cannot assemble alone.

What Puerto Rico agents do for leads, and what each approach leaves on the table

Man in a button-down shirt types on a laptop, generating Puerto Rico real estate leads, and writes in a notebook at a shared desk with two others working in the background.

Six approaches cover most of the island: shared leads from legacy portals, an IDX site of the agent’s own, cold calling and door knocking, predictive-seller software, an all-in-one CRM the agent configures, and paid social ads. Plenty of agents also farm a single barrio or urbanización by hand, which on this island is often the most productive of the lot. Each of these closes business for someone. Each also has a limit worth naming before an agent spends another year on it.

Shared portal leads deliver volume, and volume matters when an agent needs at-bats. The catch sits in the word shared: the same person’s contact details and budget go to several agents at once. With roughly 10,700 homes changing hands in an average year across a small island, winning on dial speed against three agents who bought the same name is an expensive way to earn a client. An IDX site avoids that entirely and builds an asset the agent owns, which is why so many build one, and it is slow. Search traffic has to be earned in a small island search universe, and the site produces little for a year or two while the bill arrives monthly.

Predictive-seller software does one thing well, which is rank a database by who looks likeliest to list, and what it returns is a name and a score. In Puerto Rico that gap is wider than anywhere on the mainland, because the relationship has to survive years in which the owner does nothing. A score does not survive that. An all-in-one CRM organizes the contacts an agent already has and produces none, and DIY social and paid ads run while the spend holds and stop the week it does not.

An agent prospecting by phone or text falls under the Telephone Consumer Protection Act as a telemarketer from the first dial, and almost nobody prices that exposure. Do Not Call complaints to the FTC ran past 2.6 million in fiscal 2025. When a recipient disputes consent, proof is the caller’s to produce. Each unproven call or text carries $500, a willful violation carries $1,500, and no ceiling caps what the total can reach. ezVerify.ai handles that on every opportunity ez Home Search sends. It captures the opt-in and the recording behind it, checks each number against a known-litigator database, fills in contact detail an agent would otherwise chase down, and screens out every number listed on the Do Not Call registry. All of it happens before the agent dials.

A partner’s contacts search on a co-branded ez Home Search experience, and their behavior shows who is close: an old search picked back up, a valuation run a second time, a saved home revisited, alerts opened the day they arrive. That activity lands in the CRM the team already runs, fullest in Follow Up Boss, where ezNurture handles the automated follow-up. The agent calls the contact whose own behavior says now. A list worked in order is guesswork with better formatting.

One partner per municipio, and what that partner actually gets

The Exclusive County Partnership gives a whole municipio to one agent, one team, or one brokerage, co-branded through the consumer experience, with no second partner working inside it. The terms are one predictable fee, no per-lead charge, and no cut of the commission. A strong month of opportunities is a strong month for the partner and not a bigger invoice.

Between 88% and 92% of buyers, asked directly, say they would hire their agent again or refer them. About 18% follow through. That gap is the biggest piece of the partnership on this island, because reactivating a database is the direct answer to the 98%. Roughly 41% of an agent’s business comes from repeat clients and referrals, and among the most experienced it is the majority, while ez Home Search partners reactivate past clients, through repeat business or referral, hitting 2.5 to 5 times the market rate. What makes that possible is a database that stops decaying. Each year 15% to 22% of email addresses go dead and up to one person in ten changes their phone number, and because a partner’s past clients keep using the co-branded search and the value updates, current details keep coming back in.

Valuation carries more weight in Puerto Rico than it does on the mainland. An assessment anchored to 1957 tells an owner nothing, and the federal price index has no municipio-level series to point them to. A co-branded home-value page that gives an owner an accurate number month after month is the one place they can get an honest answer, and it is the strongest reactivation thread a partner has, because owners check their value long before they call an agent.

About 2.1% of Americans move to a different state in a year, per Census figures, and roughly another 3% move to a different county inside their own. That is on the order of one in twenty people relocating past the area one agent serves, and in Puerto Rico the move is usually to the mainland. The purchase goes to an agent there. The home being left behind is a listing in the partner’s own municipio, and because the client searches the mainland on the partner’s platform, the partner sees the move coming and has the seller conversation before the listing is in play.

Recognition converts because most people never comparison-shop an agent. The National Association of Realtors, in its Profile of Home Buyers and Sellers, finds 81% of sellers contacting only one agent before choosing, 77% of repeat buyers interviewing only one, and reputation as the single most important factor for 35% of sellers. In a municipio of 25,000 people, being the name that comes to mind wins the client before any comparison happens.

Underneath all of it sits The Only Confidential Home Search, ez Home Search’s way of delivering A Better Way To Discover Real Estate. Nobody sells, resells, recycles, or broadcasts a person’s budget or their contact details to businesses they never chose. Their information goes to one vetted local expert, the Single Local Expert behind their experience, and they know who that is. Most people work through the biggest financial decision of their lives without telling anyone, often for months, and they will not do that work on a platform where one search becomes weeks of phone calls. On an island where owners stay put for years, the partner who stays present across that wait is the partner who gets the call when it ends.

Deciding whether a Puerto Rico municipio partnership fits

An agent on this island has three real paths. The first is the one almost everyone is on: keep competing for the roughly 10,700 homes that change hands in a year against every other agent doing the same, and watch the cost of each client climb as more of them bid for the same active shopper. The second is to hold one municipio and spend several years becoming the name its owners already know, so that when they move, and most eventually do, the call comes to one place. The third is to build the equivalent alone: a consumer platform, the data behind it, a valuation engine, a compliance layer, and content that keeps a database warm. That path costs millions and the data sourcing behind the valuations sits out of reach of any single team or brokerage, which is why almost nobody finishes it.

Opportunities from ez Home Search convert in 30 to 60 days, so business starts moving inside a quarter. The compounding takes years, and the value is in how many owners know one agent’s name ten years out. An agent who needs closings in the next 60 days and has no interest in the decade after that should not sign for that reason alone.

ez Home Search partners reactivate past clients, through repeat business or referral, hitting 2.5 to 5 times the market rate. Everything else on this page describes the opportunity. That number describes what a partner does with it.

If your municipio is still open, that is worth finding out before someone else asks. One partner holds a territory, and the position is claimed municipio by municipio.

Fewer than two owners in a hundred sell in a given year. Whoever is known to the other ninety-eight owns the decade.

Frequently asked questions

How do I generate listings in a municipio where roughly 94% of homeowners stay put in a given year?

Stop working the 6% and start owning the relationship with everyone else. Census data for 2020 to 2024 puts 94.1% of Puerto Rico residents at the same address a year earlier. Listings here come from life events instead of market timing: a death in the family, a downsizing, a child buying a first home, a second property that has become a burden. The agent who is already the source of an owner’s home value hears about those first, because that owner has been checking the value for years.

What does an exclusive county partnership mean in Puerto Rico, where there are municipios instead of counties?

The Census Bureau treats Puerto Rico’s 78 municipios as county-equivalents, and ez Home Search coverage runs across 3,144 counties and county equivalents, so the Exclusive County Partnership assigns one partner per municipio. One agent, team, or brokerage holds that territory, co-branded through the consumer experience, with no second partner inside it. The terms are one predictable fee, no per-lead charge, and no cut of the commission.

How should I handle a seller whose home is still recorded in a deceased parent’s name?

Raise it at the listing appointment and get documents moving before you talk about price, because succession filings and title work take calendar time no closing date will wait for. This is common enough here to plan for. A Puerto Rico government estimate reported in 2018 put more than half the island’s houses in the informal category, built without permits and lacking clear title, and the Puerto Rico Department of Housing runs a federally funded Title Clearance Program that registers rightful owners in the Property Registry. The partner who has held the relationship for years starts that conversation before a buyer is waiting on it.

Where can I get municipio-level price data when FHFA publishes only one index for all of Puerto Rico?

The Federal Housing Finance Agency publishes a single territory-wide index that San Juan, Ponce, and Mayagüez all share, so a municipio-level answer has to be built from local transaction data and a valuation model running on it. That is what an ez Home Search partner puts in front of an owner: an accurate AVM figure for that specific property, refreshed month to month, plus a full comparative market analysis from the Single Local Expert when the owner wants the reasoning behind the number.

How do I work Act 60 relocation buyers without building my whole business on them?

Treat them as one lane. More than 4,000 existing decree holders is roughly half a percent of an owner base near 876,000 households, concentrated in Dorado, Guaynabo, Condado, Palmas del Mar, and Rincón. What makes the lane worth staffing is the clock: a decree holder has to show evidence of buying Puerto Rico real estate as a primary residence within two years of receiving the decree. Send residency and income-sourcing questions to a Puerto Rico tax attorney or CPA and keep your side on the transaction and the local knowledge.

Should I run my listings and follow-up in Spanish, English, or both?

Both, split by who you are talking to. Census figures for 2020 to 2024 show 95.5% of Puerto Rico residents speaking a language other than English at home, while mainland relocation buyers and decree holders largely operate in English. Local seller outreach and neighborhood material should be Spanish-first; relocation and remote-work buyers need English. The activity signals coming off a co-branded platform tell you which side of a person’s move is live regardless of the language the conversation happens in.

What do I say to an owner whose housing cost is $180 a month and who sees no reason to move?

Nothing about moving. Census data for 2020 to 2024 puts the median monthly owner cost without a mortgage at $180 here, and an owner carrying that number will not be moved by a rate headline. Be useful about the asset instead: what the home is worth, how much equity has built up, what the tax picture looks like, and what that equity would buy in another municipio or on the mainland. Then be the name on file when the reason to move arrives.

Which municipios outside the San Juan metro are actually gaining residents?

Six municipios recorded gains between the 2020 Census and the July 2024 estimates. Rincón led them, up 2.9% from 15,187 to 15,625, with smaller gains in Isabela, Moca, Barranquitas, Naranjito, and Aibonito. Nearly every other municipio recorded a decrease. The gains are small in absolute terms, and in a municipio of 20,000 people a steady trickle of arriving households changes the local market in a way the same number never would in Bayamón.

08.20.2026

Rhode Island Real Estate Leads: Reaching Buyers and Sellers Early

Rhode Island closed between 7,400 and 7,800 single-family homes in each of 2023, 2024, and 2025, according to year-end data from the Rhode Island Association of Realtors and State-Wide MLS. The state holds roughly 280,800 owner households, from Census Bureau counts of 441,570 households at a 63.6% owner-occupied rate. Under 3% of owners sold in any of those three years. Add condominiums and multifamily and the picture barely moves.

Almost nobody sold.

That gap is what most approaches to Rhode Island real estate leads get wrong. Nearly 6,000 Realtors in a state of 39 cities and towns compete for the small share of owners who have already raised a hand, bidding against each other for expireds, for shared portal names, and for the same neighborhoods. The owners who will move next are not in that fight. They are checking what their house is worth, watching one street, and telling nobody.

The agent who reaches them first is doing a different job than the one bidding for the hands already in the air.

The Rhode Island seller you want is out shopping for a house right now

Roughly four in five Rhode Island buyers already own a home they will have to sell, so the listing an agent takes next year usually belongs to somebody touring houses today. Most agents never work that person until the second half of the move.

Look at how the two campaigns are usually run. “List with me” goes out to sellers, bought buyer leads get handed to someone junior, and the same household ends up chased twice by the same office under two different pretexts.

Here is where that ratio comes from. The National Association of Realtors, in its 2025 Profile of Home Buyers and Sellers, puts first-time buyers at 21% of purchases, the smallest share the association has recorded since it started tracking in 1981. The median first-time buyer is now 40 years old, a record, and the median seller is 64, also a record. Everyone outside that 21% owns something they have to unload first.

Be precise about the claim, because the loose version of it is wrong. Any single house has one person buying it and a different person selling it. Across a move, though, both halves belong to the same household, and that household almost always starts on the buy side long before a listing agreement exists. Somebody spends the better part of a year looking at what their money buys in Barrington or East Greenwich, then calls an agent about the house they already own.

Rhode Island’s own numbers show the entry side plainly. RIHousing financed 1,465 first-time buyers in 2025 at an average age of 38, according to its 2025 Impact Report, though that is a program count and not a market share. Those buyers are the one in five. The other four in five are sitting on equity in a house nobody has listed yet.

ez Home Search reads behavior instead of picking a lane. A valuation run twice, a home-value page opened, a question about equity, and the seller conversation is live. A saved search, an alert opened within the hour, a tour on the calendar, and the buyer side is moving. Most Rhode Islanders produce both patterns in sequence, and the platform follows the shift rather than guessing which campaign a person belongs in. The automated valuation model, an estimate of what a home is worth built from public records and market data, keeps the partner present through the years in between, so the buyer an agent helps in one decade is the listing they take in the next.

Rhode Island has roughly 280,800 owner households. Nearly every one of them is a future seller, and most of them will start out shopping.

One partner holds each Rhode Island county, and the state only has five. Find out whether yours is still available.

What is actually happening across the Rhode Island market

Rhode Island is a fast, competitive, expensive market where homes trade hands less often than they used to. Both halves of that sentence matter, and most market summaries only carry the first.

Aerial view of downtown Providence, Rhode Island, showing office buildings, the river and bridges in autumn
Providence County holds 678,179 of Rhode Island’s 1,114,521 residents and produces roughly half the state’s single-family sales.

Start with price and speed. The statewide median single-family price climbed in each of the last three years on record, from $425,000 in 2023 to $474,700 in 2024 to $499,900 in 2025, per year-end data from the Rhode Island Association of Realtors and State-Wide MLS. Houses move fast here and have for years. Average days on market has sat between 31 and 33 every year since 2022, down from 61 in 2019. Supply is the binding constraint behind both numbers. Rhode Island has run under a two-month supply of single-family homes and condominiums across 2024 and 2025, against 3.3 months nationally per NAR figures the association cited, and five to six months is what the association names as balanced. Its president calls the shortage a problem that predates the pandemic, since made worse by owners holding older mortgage rates.

Condominiums are where affordability went. Condo sales grew 5.8% in 2025, the largest gain of any housing type that year, on a $390,000 median. Set that against a single-family median that rose from $425,000 to $499,900 across the same three years and the condo becomes the entry point a local buyer can still reach. Multifamily ran the other way on price, with the median up 8.2% while sales stayed essentially flat at half a percent of growth. An agent working Pawtucket or Woonsocket is working a fundamentally different product mix than one working Jamestown.

Buyers are arriving from outside the state in numbers worth planning around. Out-of-state buyers accounted for 22.5% of all Rhode Island residential sales in the most recent year the association reported, and 41.1% of sales at $1 million or more. More than 12% of all sales came from Massachusetts alone, where single-family prices sit well above Rhode Island’s $499,900 median. A Rhode Island house at half a million dollars reads as a discount from Attleboro or Fall River, and that math is not going away. Institutional buyers moved harder here than nationally as well: NAR research reported by the state association puts Rhode Island’s institutional share at 22.5% of sales in 2024, up from 10.9% in 2019, while the national share barely moved from 15.1% to 15.7%.

Migration deserves its actual size rather than its usual headline. In the most recent year Census Bureau estimates cover, Rhode Island lost 1,551 residents to other states, gained 5,923 from abroad, recorded 304 more deaths than births, and finished up 4,106 people at 1,114,521. The longer series carries the same message. The state’s population has risen in every year since 2021, from 1,097,381 to 1,114,521. Against 441,570 households, net domestic outflow is a fraction of one percent. It also cuts both ways for an agent: people leaving are listings and referral fees, people arriving are buyers.

Construction picked up from a low base. Rhode Island municipalities issued 3,778 building permits in 2025, the highest count since the 1980s, and 2,162 certificates of occupancy across all 39 cities and towns, according to the Executive Office of Housing’s 2025 Integrated Housing Report. The governor’s office characterizes the gain as consistent progress year after year rather than one strong season. Providence alone opened 727 new units and West Warwick 183.

Employment is spread across sectors rather than resting on one anchor, and the two clearest growth stories both run over years rather than quarters. Defense manufacturing leads. Quonset Point in North Kingstown supports 15,309 direct on-site jobs across more than 250 companies, plus another 14,146 indirect and induced, which together account for 5.8% of all Rhode Island jobs. That comes from an independent Bryant University study published by the Quonset Development Corporation, which also puts the total employment impact up 32% since 2018 and Quonset’s 9,881 manufacturing positions at 25% of the state’s manufacturing workforce, against 20% in 2023. General Dynamics Electric Boat is adding roughly 3,000 to 3,500 more jobs there, on top of the more than 8,000 it already employs, per the office of US Senator Jack Reed.

Life sciences is the second story. Providence’s 195 District has drawn 17 completed or planned projects and more than $890 million across 26 acres. Behind it sit a state Life Science Hub funded at $45 million in 2023 and Ocean State Labs, the state’s first commercial incubator, which opened in 2026. Those are paychecks landing in a county that closes over 1,200 single-family sales a year and a capital city that opened 727 new units in 2025.

The other half rarely makes the summary. Statewide closed single-family sales ran 11,066 in 2016, 11,282 in 2017, 10,687 in 2018, 11,013 in 2019, 11,650 in 2020, and 11,500 in 2021, then 9,565, 7,409, 7,708, and 7,811 in the four years that followed. The ten-year average is 9,969. Over that same decade the median price rose 108%, days on market fell from 61 to 33, and distressed sales fell from 869 to 63. Demand held. What changed is how often the same houses come up for sale. Rhode Islanders are staying put longer, which pushes the transaction an agent wants further out in time.

Table 1: Rhode Island’s five counties

CountyPopulation (Jul 2025)Principal cities and towns2025 single-family sales2025 median price
Providence678,179Providence, Cranston, Pawtucket, Woonsocket, East Providence, Cumberland, North Providence, Johnston3,726$450,000
Kent173,495Warwick, West Warwick, Coventry, East Greenwich, West Greenwich1,780$443,000
Washington129,795South Kingstown, North Kingstown, Westerly, Narragansett, Charlestown, New Shoreham1,222$675,000
Newport83,051Newport, Portsmouth, Middletown, Tiverton, Jamestown, Little Compton676$789,500
Bristol50,001Bristol, Barrington, Warren407$685,000

Population: US Census Bureau estimates via the Rhode Island Department of Labor and Training, March 2026. Sales and median price: Rhode Island Association of Realtors and State-Wide MLS, year-end 2025, the most recent full year in a series that has held statewide volume between 7,400 and 7,800 sales since 2023 while the statewide median rose in each of those years.

How Rhode Island’s five counties and seven regions diverge

Aerial view of a Rhode Island coastal neighborhood with houses, trees and open water under a partly cloudy sky
Seven regions inside a state you can drive across in 45 minutes, each running on different math.

Rhode Island’s growth has concentrated in one county while its highest prices sit in another that is getting smaller. Providence County went from 660,723 residents at the 2020 census base to 678,179 by July 2025, per Census Bureau estimates published by the state Department of Labor and Training. The state as a whole grew by about the same number of people. Providence County absorbed essentially all of it.

Newport County moved the other way, down 3.0% to 83,051. It also carries the highest county median in the state at $789,500 and the longest average marketing time at 50 days. Both facts are true at once, and neither is a verdict on whether the market is healthy. Fewer people live in Newport County than did five years ago, and the houses there cost more than anywhere else in Rhode Island. That is a supply story and a desirability story sitting on top of each other.

Kent County is the volume engine. It closes roughly 1,780 single-family sales a year, and Warwick alone accounts for 961 of them, more than any other municipality in the state. An agent who wants transaction count works Kent. An agent who wants transaction size works Newport or Bristol, where Bristol County‘s median reached $685,000, second highest of the five counties, carried by Barrington at a $750,000 median.

Washington County is the one that rewards patience. It holds the newest housing stock in the state, the Quonset employment base in North Kingstown, and the widest internal price range in Rhode Island, from Hopkinton at $500,000 to Block Island at $1,870,000 on 19 sales.

Table 2: Rhode Island regions

RegionTownsSourced trend
Providence metroProvidence, Cranston, East Providence, Johnston, North ProvidenceProvidence opened 727 new units for occupancy in 2025, the most of any Rhode Island municipality, inside a statewide permit count that reached its highest level since the 1980s (RI Executive Office of Housing, 2026)
Blackstone ValleyPawtucket, Central Falls, Woonsocket, Cumberland, Lincoln, Smithfield, North SmithfieldCarries the state’s lowest entry prices, with Pawtucket and Woonsocket medians near $390,000 to $400,000, while statewide residential property values rose 47% between FY2023 and FY2026 (RIAR, 2026; RIPEC, 2026)
Northwest Rhode IslandBurrillville, Glocester, Foster, ScituateStatewide accessory dwelling unit permits rose from 11 in 2021 to 163 in 2024, and these are the low-density towns where the added space is most usable (HousingWorks RI, 2025)
East BayBarrington, Bristol, WarrenBristol County’s median reached $685,000, second highest of the five counties, while its population slipped from 50,789 in 2020 to 50,001 in 2025 (RIAR, 2026; Census via RI DLT, 2026)
Aquidneck Island and SakonnetNewport, Middletown, Portsmouth, Jamestown, Tiverton, Little ComptonNewport County’s population fell 3.0% between 2020 and 2025 while its median reached $789,500, the highest of the five counties (Census via RI DLT, 2026; RIAR, 2026)
South CountySouth Kingstown, North Kingstown, Narragansett, Westerly, Charlestown, Exeter, Hopkinton, Richmond, New ShorehamCharlestown, Exeter, Richmond, South Kingstown, and West Greenwich are the only Rhode Island municipalities whose housing averages a build year of 1978 or later (RI Executive Office of Housing, 2026)

The seventh region, West Bay, covers Kent County’s Warwick, West Warwick, Coventry, East Greenwich, and West Greenwich, and it behaves less like a region than like the state’s clearing house: mid-priced, high-volume, and the place where buyers priced out of Barrington and Wickford end up instead.

Seven regions in a state you can drive across in 45 minutes, each running on different math. That is the argument against treating Rhode Island as one market, and it is the argument for holding a county rather than farming a few streets inside one.

The Rhode Island towns most agents drive past

Boats docked at a small Rhode Island marina with houses and trees along the shoreline on a clear day
Towns closing 50 to 90 sales a year are thin markets rather than leftover ones, and thin markets reward the agent who was already there.

The newest housing stock in Rhode Island sits in small South County towns, while the most new units go up in the urban core, and those are two different facts that send an agent in two different directions.

Take the stock first. Rhode Island’s housing has a median construction year of 1964, third-oldest in the country behind only New York and Washington DC, according to the Executive Office of Housing’s 2025 Integrated Housing Report. Providence’s median is 1939. Only five municipalities in the entire state have housing that averages a build year of 1978 or later: Charlestown, Exeter, Richmond, South Kingstown, and West Greenwich. Four of the five sit in Washington County. That is a statement about the typical house already standing in those towns, not about how much gets built there.

New construction runs the opposite way. Providence opened 727 new units for occupancy in 2025 and West Warwick 183, the two highest counts in the state, per the same report. A city can lead the state in new units and still carry the oldest median in it, because 727 new units barely move a housing stock built mostly before the war.

For an agent, both halves are a working condition rather than a piece of trivia. Pre-1978 housing means lead paint disclosure on nearly every transaction in the state, buyers who need renovation financing more often than buyers in newer markets do, and inspection findings that unsettle first-time buyers expecting a house built in this century. A buyer who wants a newer existing home is shopping South County. A buyer who wants something nobody has lived in is shopping Providence or West Warwick. Knowing which conversation to have saves everyone a month.

The volume is smaller out there. Exeter closes about 61 single-family sales a year, Foster about 51, West Greenwich 46, Little Compton 31, and New Shoreham 19. A team that needs 200 transactions a year cannot live on those towns. A partner who holds Washington County gets all nine of its towns at once, Block Island and Exeter alongside South Kingstown‘s 243 sales and North Kingstown’s 235, which is a different proposition entirely.

Table 3: Rhode Island municipalities beyond the Providence metro

Town (county)2025 single-family sales2025 medianVillages and neighborhoods
Coventry (Kent)448$438,950Anthony, Washington, Greene, Quidnick
South Kingstown (Washington)243$694,500Wakefield, Peace Dale, Kingston, Matunuck
North Kingstown (Washington)235$650,000Wickford, Davisville, Saunderstown, Hamilton
Westerly (Washington)209$610,000Watch Hill, Misquamicut, Weekapaug, Bradford
Narragansett (Washington)178$932,500Point Judith, Galilee, Bonnet Shores, Narragansett Pier
Portsmouth (Newport)169$745,000Common Fence Point, Island Park, Prudence Island
Tiverton (Newport)160$499,500Tiverton Four Corners, Nanaquaket, Stone Bridge
Burrillville (Providence)127$475,000Harrisville, Pascoag, Oakland, Mapleville
Charlestown (Washington)113$715,000Quonochontaug, Cross Mills, Kenyon
Glocester (Providence)99$519,900Chepachet, Harmony, West Glocester
Hopkinton (Washington)94$500,000Ashaway, Hope Valley, Rockville, Canonchet
Scituate (Providence)88$518,050North Scituate, Hope, Rockland
Richmond (Washington)70$545,000Wyoming, Arcadia, Wood River Junction
Exeter (Washington)61$650,000Fisherville, Liberty
Foster (Providence)51$500,000Foster Center, Moosup Valley
West Greenwich (Kent)46$591,000Nooseneck, Escoheag
Little Compton (Newport)31$985,000Adamsville, Sakonnet Point
New Shoreham, Block Island (Washington)19$1,870,000Old Harbor, New Harbor, Corn Neck

Rhode Island Association of Realtors and State-Wide MLS, year-end 2025, the most recent full year available. Statewide single-family volume has run between 7,400 and 7,800 in every year since 2023, so these town-level counts are representative rather than a one-year spike.

Look at what the small numbers are attached to. Foster‘s 51 sales carried a $500,000 median and Exeter’s 61 came in at $650,000, both above the $450,000 median across Providence County’s 3,726 sales. Call these markets thin rather than leftover. A thin market rewards the agent whose name is already on the search a buyer has been running for two years, because there are fewer chances and each one counts for more.

Remote and hybrid work is still a Rhode Island buying signal

Remote work did not go away, and the agents who believed the headlines have been mispricing a lasting source of Rhode Island demand for years. The confusion comes from a measurement choice. Coverage of the subject compares today against the emergency peak of spring 2020, when roughly 61% of paid workdays happened at home. Nobody ever treated that as a steady state. Measured against the pre-pandemic baseline of about 5% to 8% of paid workdays, the level today represents a structural tripling that has held since 2023.

Two federal numbers are worth carrying into client conversations. The Census Bureau put its Business Trends and Outlook Survey to roughly 150,000 US firms, and 31.2% of them had at least one employee putting in a full workday from home, a level those same employers expect to hold five years out. The worker-side count runs the same way: 36.7 million Americans teleworking in the fourth quarter of 2024 by the Bureau of Labor Statistics tally, against 32.5 million twelve months before. Both figures are national, and neither one gets to be restated as a Rhode Island statistic.

A calm Rhode Island lake with lily pads and surrounding trees at sunset
The low-density towns of Washington County and northwest Providence County were priced by commute distance and are now priced by something else.

What is specifically Rhode Island is the geography positioned to absorb it. Washington County towns like Exeter, Richmond, Hopkinton, and Charlestown, the northwest quadrant of Providence County across Burrillville, Glocester, Foster, and Scituate, plus West Greenwich, Coventry, Tiverton, and Little Compton, are exactly the markets that were priced by commute distance and are now priced by something else. Rhode Island’s mean travel time to work is 25.5 minutes and 91.7% of households hold a broadband subscription, per Census figures. In a state this compact, a two-day-a-week office schedule erases the penalty that used to make Hopkinton a compromise.

The practical version is the part an agent can use on a showing. Remote and hybrid buyers want a work space with a door they can shut, an accessory dwelling unit, a separate structure on the lot, more square footage than their household size suggests, and internet that holds a video call. Rhode Island just made one of those far easier to deliver. Statewide accessory dwelling unit permits went from 11 in 2021 to 163 in 2024, per the HousingWorks RI 2025 Housing Fact Book, after the state loosened the rules.

Most Rhode Island agents still sell these towns on price. The buyers moving there are shopping for a floor plan that supports a job nobody drives to.

Three Rhode Island tax changes landed inside twelve months

Rhode Island changed the tax treatment of selling a home, renting one short term, and owning a second one, all between October 2025 and July 2026. Clients are asking about all three, and an agent who cannot answer plainly loses authority in precisely the conversations that produce listings.

The conveyance tax went up. The residential conveyance tax, which is the tax paid on the transfer of a property at closing, rose from $2.30 per $500 of the price to $3.75 per $500 as of October 1, 2025. On top of that, any portion of a sale price above $800,000 carries an additional $3.75 per $500. The Rhode Island Association of Realtors opposed the increase and published the Division of Taxation’s worked examples for members. For a seller in Barrington or Narragansett, this is now a line item large enough to affect a net-proceeds conversation.

Short-term rentals got taxed. Whole homes and whole condominiums rented for fewer than 30 days took a 5% state whole-home tax on January 1, 2026, and the local hotel tax doubled from 1% to 2%. Any Westerly, Narragansett, Block Island, or Newport client running a summer rental is doing new arithmetic on whether the property still works.

Second homes over $1 million now carry an annual state tax. Non-owner-occupied properties assessed at $1 million or more, and occupied by neither the owner nor a tenant for at least 183 days in the year, are taxed $2.50 per $500 of assessed value above $1 million starting July 1, 2026. A property assessed at $1.5 million owes roughly $2,500 a year.

A sailboat passing a large waterfront home with lawn and trees on the Newport, Rhode Island shoreline
The new tax on non-owner-occupied homes above $1 million lands hardest in the coastal and island markets that carry the state’s highest medians.

That last one is the one to build outreach around, because it comes with a count. The Rhode Island Public Expenditure Council estimates the tax will reach 9,000 to 10,000 properties and raise about $25.0 million annually. Those are 9,000 to 10,000 identifiable Rhode Island owners receiving a new recurring bill, concentrated in the coastal and island markets that carry the state’s highest medians. Some will absorb it. Some will convert to a rental. Some will decide the math stopped working, and those conversations happen with whoever is already in front of them.

The wider picture supports the same point. RIPEC ranks Rhode Island 10th highest in the nation for property taxes per capita, 22% above the US per capita total in FY2023, and reports that seven municipalities exceeded the state’s 4.0% levy cap in FY2026, the most in a decade, while the statewide levy grew $98.3 million. Property taxes are a live topic at almost every kitchen table in this state.

An ez Home Search partner can pull property tax comparisons by state, county, city, and ZIP inside the platform, so a question about what Little Compton costs to hold against Tiverton gets answered in the conversation rather than in a follow-up email three days later.

How Rhode Island agents try to win listings today, and where each approach runs out

Every lead-generation method Rhode Island agents use works to some degree, and every one of them hits the same wall: they all fish in the small pool of people who have already decided to move.

Shared leads from legacy real estate portals do produce contacts, and a disciplined agent with a fast dialer converts some of them. The structural problem is that the same name goes to several agents at once, the person did not choose any of them, and the contact arrives cold at the moment it arrives. An agent who buys more of them raises the bill without changing the odds.

An IDX website is a real asset that an agent owns outright. It is also slow. It takes months to rank, it needs content added constantly to stay ranked, and the great majority of the traffic it earns never identifies itself. An agent who builds and runs one has taken on a marketing job on top of a real estate job.

Cold calling expireds and for-sale-by-owner listings still works, and plenty of Rhode Island’s top producers were built on it. In a one-MLS state, the catch is that everyone else is looking at the same expired list the same morning. That is also where the compliance exposure lives, which the next section covers.

Predictive-seller software scores a database and tells an agent who might list. The score is a guess about a person the agent still has to build a relationship with. A name flagged as likely to sell is not a warm introduction, and the software does not make the introduction.

Generic all-in-one platforms and do-it-yourself content both trade money for time and then take the time anyway. Paid ads spike with the spend and go quiet the week it stops. Geographic farming is the traditional differentiator, and in Rhode Island it barely differentiates: 1,061 people per square mile across 1,033.89 square miles means a competitor’s farm is a fifteen-minute drive away, and farm boundaries overlap everywhere.

Then there is the arithmetic underneath all of it. The Rhode Island Association of Realtors reports nearly 6,000 members across nearly 1,000 offices. The state has closed between 7,400 and 7,800 single-family sales in each of the last three years on record. Out-of-state buyers took 22.5% of all residential sales in the most recent of those years, and NAR research reported by the association puts the institutional share of 2024 sales at 22.5%, up from 10.9% in 2019. A local first-time buyer is bidding against both, and the agent representing that buyer absorbs every lost offer as unpaid work.

The mechanism ez Home Search runs is different in kind. Instead of competing for people at the active stage, it reaches them through the three stages that come first: dreaming, then gathering numbers on their own home’s value and on what other homes cost, then planning around financing, timing, and the school calendar. Those stages are long and they are private, which is why they stay invisible to anything that only counts hand-raisers. The platform then reads real activity to say which side is live right now. Someone runs a valuation a second time. Someone revisits a home they saved months ago. Someone picks an old search back up after eight months away. That signal routes to one partner in the county rather than to whoever paid most for the name.

Set expectations honestly, because a Rhode Island agent has heard oversized promises before. Partners typically convert these connections over 30 to 60 days, not inside a week, and the relationships that start this way tend to run for years. The trade is patience at the front for a pipeline that compounds instead of resetting every campaign.

If you want the mechanics rather than the sales pitch, see how the county partnership works.

What an Exclusive County Partnership does for a Rhode Island agent or team

One whole Rhode Island county goes to a single agent, team, or brokerage under an Exclusive County Partnership, co-branded through the consumer experience, with no rival partner allowed inside those lines. The commercial terms are worth stating up front because they are unusual: one predictable fee, nothing charged per lead, and no cut of the commission on a closing. A strong month is a strong month, not a bigger invoice.

The reason those connections convert has less to do with volume than with how the person arrives. People come to ez Home Search because nobody sells, resells, recycles, or broadcasts their contact details and their budget to businesses they did not choose. Each person is matched with a Single Local Expert who knows their area, chosen as the right fit rather than as the highest bidder. The Only Confidential Home Search is the name ez Home Search gives that promise, and it is the shape A Better Way To Discover Real Estate takes for a person who is still only looking. A partner meeting someone through that experience opens with a person who already trusts the platform and whose intent is on the record as behavior, which is a very different first conversation than a call to a purchased name.

Confidentiality carries particular weight in a state this size. Rhode Island has 1.1 million residents, one statewide MLS, and 88.9% of people living in the same house they lived in a year earlier, per Census figures. A couple in Cumberland thinking about a move knows their agent’s kids go to school with theirs. One spouse often explores a move for months before raising it with the other. Someone heading toward a divorce may spend six to twelve months planning before a word of it reaches anyone else. People research the biggest financial decision of their lives in private, and they will not run that research through a platform that answers one search with a week of phone calls.

The scale of that invisible population shows up in an unexpected place. RIHousing reported that more than 3,400 Rhode Islanders completed a homebuyer education class in 2025, in a state that closes between 7,400 and 7,800 single-family homes a year. Those are self-identified future buyers, most of them months or years from a transaction, and almost none of them sit in any agent’s pipeline today.

What a partner receives is already built and already running, because it is ez Home Search’s own national platform wearing their brand. A partner gets the search itself, listing alerts, home-value updates, market reports, the automated valuation model widget for their own site, an open-house page behind a QR code, and an instant cash offer for the owner who wants to know what a fast sale would bring. Nothing needs configuring and nothing needs administering. It all runs on one record of activity, so a visitor any of those tools captures becomes a tracked contact the platform keeps drawing back.

National coverage matters more in Rhode Island than the state’s size suggests. Census figures put annual relocation at roughly 2.1% of Americans changing states and about another 3% crossing into a different county inside their own state, and in a state 45 minutes across, a move to Massachusetts or Connecticut is a routine commute decision. When a past client starts searching Fall River or Mystic, they do it on the partner’s co-branded platform rather than leaving for a legacy portal, and that search shows up as a signal. The agent reaches out before the listing is in play, works the sale of the Rhode Island house, and hands the purchase off to a vetted agent on the other end, earning a referral fee. That silent loss is the one our long-time county partners say they never used to see coming.

The Rhode Island database you already own is the biggest opportunity you have

In a state where under 3% of owners have transacted in any of the last three years on record, the past clients and sphere an agent has already earned are the highest-probability pipeline available to them, and they are almost always the least worked.

The gap between how people feel about their agent and what they actually do is wide. Research reports put the share of buyers who say they would use their agent again or recommend them at between 88% and 92%. About 18% end up buying through an agent they already worked with once. That difference is repeat and referral business an agent earned and then let go. Across all agents, repeat clients and referrals account for roughly 41% of business, and for the most experienced agents it is the majority of what they do.

Meanwhile the list itself decays without anyone touching it. Somewhere between 15% and 22% of email addresses stop working in a given year, and as many as one household in ten changes its phone number. A Rhode Island database that looked complete three years ago is partly unreachable today, and the contacts who slip away first tend to be the ones who moved, which is to say the ones who were transacting.

Most agents know the database matters. The follow-up is where it falls apart, because doing it properly takes a steady stream of content people open and a search experience past clients come back to without being asked. Almost nobody can produce that while also serving clients and running a team.

An Exclusive County Partner does not produce it. Because their past clients keep using the co-branded search, the home value updates, and the listing alerts, ez Home Search captures their current email and phone as those details change, so the list stays reachable without a scrub. Outreach then fires on real activity from people who already know the agent by name rather than on a cold score for someone showing no sign of moving, and it runs inside whatever CRM the partner already uses, with ezNurture handling the automated follow-up in Follow Up Boss. The first-party result is specific: partners win past clients back, by repeat business or by referral, 2.5 to 5 times the market rate, sometimes better.

Other tools each solve one piece of this honestly. Predictive scoring identifies who might list. A monthly automated value estimate gives a client one reason to open an email. A done-for-you content service fills an inbox. None of them is a place a past client goes back to on their own, month after month, which is what keeps a relationship warm across the years Rhode Islanders now stay in their houses.

Proof of consent on every Rhode Island opportunity

The Telephone Consumer Protection Act counts a real estate agent as a telemarketer from the first prospecting call or text, and most agents working expireds in this state have never been told that. The part that catches people is where the burden falls. A recipient who disputes consent owes no proof that they never agreed. Proof runs the other way, and the agent who dialed has to produce it, number by number.

The arithmetic gets serious quickly. Every undocumented call or text is worth $500 on its own, $1,500 where the violation was willful, with no ceiling on what the total can reach. Take a 10-agent team that runs 3,000 calls through a dialer in a single campaign. If it cannot document consent for 2,000 of them, exposure starts near $1 million and reaches $3 million, before anyone counts a second campaign. These suits are usually filed as class actions, and discovery requires the team to hand over its call logs and contact database, at which point every unaccounted number can be added to the case.

Rhode Island makes this sharper than most states for a plain reason. One statewide MLS means every expired listing appears to every agent at the same moment, so the same homeowner fields calls from several agents the same morning. Call volume goes up, and documentation rarely keeps pace with it.

Opportunities reach an ez Home Search partner with that problem already handled. ezVerify.ai captures the opt-in and holds a recording of it, puts the number through a known-litigator database check before the first dial, screens out any number on the Do Not Call registry, then closes gaps in the contact record that would otherwise cost an afternoon of digging. A dispute over consent then meets documentation instead of an argument.

It also changes how the call feels. The riskiest part of the job is the outreach, and here the person on the other end is real, opted in, and expecting to hear from someone. An agent can make that call from a footing the rest of their prospecting list never provides.

Five counties, five partners

Rhode Island has five counties, which means the Exclusive County Partnership map for the entire state is five positions: Providence, Kent, Washington, Newport, and Bristol. There is no sixth, and there is no way to make one.

Aerial view of a lighthouse and buildings on a rocky Rhode Island peninsula bordered by ocean and a lagoon
Five counties, five Exclusive County Partnerships, and no way to make a sixth.

Look at what each position holds, on the most recent full year of record. Providence County carries 678,179 of the state’s 1,114,521 residents and produces 3,726 single-family sales. Kent County produces 1,780, with Warwick’s 961 inside it. Washington County produces 1,222 across nine towns from Westerly to Block Island. Newport County produces 676 on the highest median in the state. Bristol County produces 407 on the second highest. In most states a county is a slice of a market. In Rhode Island a county is a third of one.

Recognition is what makes that position worth holding, and the research on how people choose an agent is blunt about it. In the NAR Profile of Home Buyers and Sellers, 81% of sellers reach out to a single agent and choose from that one conversation, and 77% of repeat buyers interview only one. Reputation is the factor sellers weigh most heavily in the same research, the top reason for 35% of them. For most Rhode Islanders there is no comparison shopping at all. One name is already attached to real estate where they live, and it gets the call.

An agent who builds that kind of county-wide recognition alone spends years at it and more money than a single team can afford, because even a strong local brand cannot reach a whole county by itself. A partner’s name sitting on the home search that county already uses accelerates something they have been working on for a decade.

Counties are held by one partner at a time, and more of them get claimed every month. Whether a particular Rhode Island county is open right now is a question with an answer, and asking is the only way to get it.

Deciding whether an Exclusive County Partnership fits your Rhode Island business

Three paths are open to a Rhode Island agent who wants more listings, and they are worth laying side by side honestly.

The first is to keep working the declared flow. Buy shared leads, call the expireds, farm a few streets, and compete with nearly 6,000 other Rhode Island Realtors for the under 3% of owners who transact in a given year. Plenty of good agents make a living this way. The cost is that every year starts at zero and the pool never gets bigger.

The second is to hold one of Rhode Island’s five counties. Reach people through the private stages of a move, let their own activity tell you which side is live, and own the recognition inside a territory no competing partner can enter.

The third path is building the whole thing in-house. Assemble the data, the valuations, the alerts, the search experience, the follow-up automation, and the consent documentation. That is a technology and marketing stack costing millions to build and run, and the data sourcing by itself is beyond what any single Rhode Island team or brokerage can reach.

One honest trade-off belongs in the decision. This is not a next-week pipeline. Partners typically convert these connections over 30 to 60 days, and the parts that compound, the reactivated database, the county-wide recognition, the relocation listings that stop leaking to strangers, build across the years a partner holds the territory rather than inside the first quarter. An agent who needs a closing in three weeks should go call expireds. An agent building a business that still produces in 2032 is looking at a different instrument.

The proof point worth carrying out of this article is one number. Past clients come back to an ez Home Search partner, buying again or sending a referral, 2.5 to 5 times the market rate. Across a state where more than 97 of every 100 owners stay put in any given year, that multiple applies to the largest and cheapest pool of business any Rhode Island agent already owns.

Those 97 are not a dead market. They are the pipeline, and the agent whose name is already on the search they have been running without telling anyone is the one who gets the call when they finally move.

Rhode Island counties get claimed one at a time, and there are only five to claim. Check whether your county is open.

Frequently asked questions

Rhode Island has only five counties. How much territory does one Exclusive County Partnership actually cover?

More than in almost any other state, which is the point. Providence County alone holds 678,179 of Rhode Island’s 1,114,521 residents and produces about 3,726 single-family sales a year. Kent County covers Warwick, West Warwick, Coventry, and both Greenwiches, and produces about 1,780 of them. Washington County stretches across nine towns from Westerly to Block Island.

A county partnership in a large state gives an agent one piece of a metro. In Rhode Island it gives them a recognizable region that residents name when they describe where they live.

Rhode Island closes under 8,000 single-family sales a year against roughly 280,000 owner households. Where do the next listings come from?

From the owners who did not sell, which is nearly all of them. That is the whole argument for reaching people earlier.

Rhode Islanders move less often than they used to, so the same house comes up for sale on a longer cycle. The owner who lists in 2031 is already checking what their home is worth, already looking at Barrington or Wakefield on weekends, and already telling nobody. Every one of those behaviors is observable if a partner is the one whose platform they are using.

Out-of-state buyers took 22.5% of Rhode Island sales. How do I reach them before they land somewhere else?

Out-of-state buyers accounted for 22.5% of all Rhode Island residential sales in the most recent year the Rhode Island Association of Realtors reported, and 41.1% of sales at $1 million or more. Most of them started searching from another state months earlier.

An agent working only local channels never sees that search. National coverage means a buyer in Massachusetts or Connecticut researching Tiverton or South Kingstown does it on the county partner’s co-branded platform, and their activity surfaces to that partner instead of routing to whoever bought the ZIP code that week.

More than one in eight Rhode Island sales came from Massachusetts buyers. How do I work that cross-border flow?

More than 12% of all Rhode Island sales went to Massachusetts buyers in the most recent year the Rhode Island Association of Realtors reported. They were crossing into a market whose single-family median rose from $425,000 to $499,900 over the last three years on record and still sits well below Massachusetts pricing. That price gap is structural rather than seasonal.

The practical move is to be present in the research phase, which happens on the Massachusetts side of the line. A Rhode Island partner cannot list in Attleboro, but they can be the local expert attached to the search a Bristol County buyer is already running, and they can take the referral fee on the Massachusetts home that buyer needs to sell.

Newport County’s population is falling while its median price is the state’s highest. Is that market worth my time?

Newport County’s population dropped 3.0% between 2020 and 2025 to 83,051, and its single-family median stands at $789,500, the highest of the five counties. Both numbers are real and they do not contradict each other. The county has fewer households than it did in 2020 and still has more buyers than it has listings.

It is also the county most exposed to the new state tax on non-owner-occupied homes assessed above $1 million, which RIPEC estimates will reach 9,000 to 10,000 properties statewide. Newport County averages about 50 days on market, the longest in Rhode Island, which means listings there need an agent who can market a home rather than one who relies on speed.

How should I talk to Rhode Island clients about the new tax on non-owner-occupied homes over $1 million?

Plainly, and with the mechanics right. From July 1, 2026, a non-owner-occupied Rhode Island property assessed at $1 million or more, and occupied by neither the owner nor a tenant for at least 183 days a year, owes $2.50 per $500 of assessed value above $1 million. A $1.5 million property owes roughly $2,500 annually.

The conversation that follows is the useful one. Some owners will absorb it, some will start renting the property past the 183-day threshold, and some will decide the carrying cost stopped making sense. Agents who can model all three outcomes with real property tax data get asked first.

Rhode Island’s housing stock has a median build year of 1964. How does that change how I work buyers here?

Rhode Island’s housing is the third-oldest in the country behind New York and Washington DC, per the state’s 2025 Integrated Housing Report, and Providence’s median build year is 1939. Lead paint disclosure touches nearly every transaction. Renovation financing comes up more often than it does in newer markets. Inspection reports surprise first-time buyers who expected a house from this century.

Only Charlestown, Exeter, Richmond, South Kingstown, and West Greenwich have housing that averages a build year of 1978 or later, and four of the five sit in Washington County. Keep that separate from new construction, which runs the other way: Providence opened 727 new units in 2025 and West Warwick 183, the two highest counts in the state. Send a buyer who wants a newer existing house to South County, and a buyer who wants something brand new to the urban core.

Every Rhode Island agent works off one statewide MLS. What is left to compete on?

Access to listings stopped being an advantage the moment every agent in the state saw the same feed at the same second. What is left is timing and relationship.

On timing, an agent needs to know which contacts are close to acting before they announce it, and that comes from watching real behavior rather than guessing at a list. On relationship, the agent who has already become the name a county associates with real estate wins before any comparison happens. NAR’s research is blunt about this: 81% of sellers contact only one agent, and 77% of repeat buyers interview only one.

08.19.2026

Oregon Real Estate Leads: A County-by-County Guide

Oregon has 1,084,977 owner-occupied households and took in about 17,000 net new residents in the year to June 2025. Those two numbers say more about where Oregon real estate leads come from than any market forecast will.

The migration figure comes from Portland State University’s Population Research Center, the state’s official estimator. Set it against more than a million Oregon households that already own their home, holding $539 billion in value, on 2022 Census figures tabulated by the National Association of Realtors. The arithmetic points one direction. The business sits in the owner base.

That changes what a lead source has to do. It has to reach people who are not moving this year, stay useful while they wait, and surface them the month they start. Most lead sources are built for the opposite job.

Oregon hands an agent something no other state does. Its property tax system has drifted so far from market value that the taxable share runs from 41 cents on the dollar in one county to 63 cents in another, and almost no owner can work theirs out. That is a reason to be in touch every year with people who have no plans to sell.

What Oregon’s housing market is actually doing

Oregon’s market is steady, and what constrains it is supply rather than demand.

Aerial view of downtown Portland, Oregon at sunset with the Willamette River and its bridges
The six-county Portland region recorded 17,083 detached single-family closings in 2025.

Start with closings, because transaction counts are what an agent gets paid on. In the six-county Portland region, detached single-family sales rose to 17,083 in 2025 from 16,872 the year before, on dollar volume of $11.7 billion against $11.4 billion. Median price moved from $595,000 to $599,990. Those figures come from RMLS data compiled by a certified residential appraiser who publishes annual reviews of the region with off-market entries stripped out. Statewide, the median sat at $484,700 in October 2025, up just under 1% from a year earlier, per Oregon REALTORS.

Homes took longer to sell. Average cumulative days on market in the Portland region stretched from 53 to 59, and months of supply averaged 2.9. Both things were true at once: buyers deliberated more, and there still was not much to deliberate over.

Those two measures get conflated constantly, so separate them. Months of supply counts the stock sitting on the market at a moment. Closed sales count the flow of deals over a period. Oregon’s stock is thin. Its flow is holding.

The supply side is where Oregon differs most from the rest of the country, and measured figures carry that point better than any projection does. Between 2013 and 2022 the state produced 0.84 housing units for every household that formed, according to analysis ECONorthwest presented to the Oregon Legislature in January 2025 using Census data. Permits over a rolling 12-month window fell 35% between January 2023 and 2024, from 21,676 to 14,074, with single-family down 7% and multifamily down 58%. Portland metro apartments under construction dropped from 4,400 at the end of 2023 to roughly 1,000 by late 2025, the fewest since 2011. Oregon’s vacant share of housing stock was 5.6% in the 2022 Census count. Nationally it was 9.7%.

Prices have outrun incomes, though by less than the coverage suggests. Since 1984, Oregon home prices are up 204% while median household income is up 196%, per FHFA and Census figures. Since 1980, prices have climbed faster in 11 other states than in Oregon. Oregon is expensive against local incomes and still sits mid-pack nationally on how fast prices have climbed.

The last piece is rate lock, and it explains why a lot of Oregon owners who would like to move have not. Work by Liebersohn and Rothstein for the National Bureau of Economic Research found that each percentage point the prevailing rate sits above a borrower’s original rate is associated with a 5.5% drop in the chance that household moves in a given quarter. Freddie Mac’s weekly average on the 30-year fixed ran from about 7.0% early in 2025 down to roughly 6.1% by that December, close to double what the same series recorded in 2020 and 2021. Oregon owners who financed in those years are the ones staying put.

Every one of those figures points at the same person. The Oregonian who transacts next is already living in the house.

Where Oregon’s economy is adding jobs and where it is shedding them

Oregon’s job base is rotating between sectors and between regions, and every rotation is somebody’s move.

Rolling Willamette Valley vineyards and a red barn under spring light in Oregon wine country
The Willamette Valley holds 69% of Oregon’s planted vineyard acreage and 81% of its Pinot noir production.

Health care carries the growth. From January 2025 to January 2026, health care and social assistance added 9,800 jobs, a gain of 3.2%, while total nonfarm payrolls fell by 18,600. In the fourth quarter of 2025, private health care and social services accounted for nearly 14,500 job openings, close to a third of every opening in the state. Both figures come from the Oregon Employment Department. Manufacturing moved the other way and shed 4,000 jobs over the same twelve months. Construction added 1,000 in January 2026.

The semiconductor story sits almost entirely inside Washington County. Intel cut more than 3,000 Oregon positions during 2025: 1,521 at Ronler Acres, 519 at Jones Farm, 192 at Aloha and 160 at Hawthorn Farm, as reported by OPB and the Hillsboro News Times. Headcount at the company’s Oregon sites has come down from a peak near 23,000 to roughly 18,000. Pay in those roles averages around $110,000, which is why the effect reaches past the campus gates and into Hillsboro, Aloha and Beaverton. Some of those households will relocate for the next role. Some will stay and trade down. Both are people who need an agent months before they call one.

Head east and the direction reverses. Data centers employed about 7,800 Oregonians in 2025, with about as many again working construction and contracting for the industry, and communities around the state have designated something on the order of 9,100 acres for more, per OPB and the Lincoln Chronicle. Most of that build sits in Umatilla and Morrow counties, where Hermiston cleared the way for further development in September 2025. Housing has followed. The Hermiston Herald reported a 270-home subdivision going up on East Theater Lane, a 202-unit apartment building in Pendleton that filled faster than its developer expected, and new infrastructure opening 250 acres near Interstate 84.

The Willamette Valley runs on something else again. Oregon’s wine and wine grape industries generated $8.49 billion in economic impact in 2024, a gain of 3.8%, and supported more than 38,000 jobs, according to the Oregon Wine Board study released in February 2026. The valley holds 69% of the state’s planted vineyard acreage and 81% of its Pinot noir production. That puts a working agricultural economy inside an hour of Portland and puts Yamhill, Polk and Marion counties in a category of their own.

Underneath all of it, Oregonians keep starting things. The state recorded more new business registrations than any other in 2023. Establishment openings in 2025 ran roughly 30% above the 2015 level, and openings have outnumbered closings in each of the last ten years, per the Oregon Capital Chronicle and the Oregon Employment Department. Labor force participation has held near 63%.

Every one of those sectors produces the same thing from an agent’s side of the desk. Someone takes a job in Hermiston and needs a house. Someone takes a package in Hillsboro and decides to move closer to family in Bend. A cellar hand in McMinnville finally buys instead of renting. None of it reaches a lead feed until the person raises a hand, and by then they have usually already chosen somebody.

Oregon households are changing shape, and it shows up in the schools

Oregon is getting older and its households are getting smaller, and the school data reads that shift more clearly than anything else the state publishes.

Downtown Salem, Oregon at dusk with the state capital's skyline and tree-lined streets
Salem sits at the center of a Willamette Valley school-age population that keeps shifting between districts.

Deaths outnumbered births in 27 of Oregon’s 36 counties, according to Portland State University’s Population Research Center in its 2025 annual report. Net in-migration is what kept many of those counties growing at all. Statewide, migration is now the only thing adding to Oregon’s population, because births keep falling.

The schools register the same shift earlier and in sharper detail. Public school enrollment has dropped by more than 37,000 students since 2020, after climbing every year from 2012 through 2019. The steepest year was 2020 to 2021, when 21,744 students left, followed by another decline of nearly 8,000. The Oregon Department of Education reports the counts, and OPB compiled the trend in November 2025.

Where those students went is the part nobody can fully answer. A Brookings Institution analysis found 12% of Oregon’s school-aged children unaccounted for, living in the state but appearing on neither public nor private enrollment rolls, the highest share of any state in the country. The number of families homeschooling rose 72% in the pandemic’s first two years, per the state education department.

For an agent, that shift has an address. Oregon has 197 school districts, and demand inside them keeps redistributing. A family weighing Lake Oswego against West Linn, or Bend-La Pine against Redmond, or Corvallis against Philomath, asks a school question first and a house question second. That has always been true here. What changed is that the answer keeps moving, and the sources most families reach for have not kept up with it.

The same shift is rearranging who owns what. Fewer children per household across much of Oregon leaves more owners in their fifties and sixties holding four-bedroom houses they bought for a family that has since scattered. Statewide, 76% of Oregon householders aged 55 and over own their home, on 2022 Census figures compiled by the National Association of Realtors. That is the largest and least-worked seller pool in the state, and it will not announce itself.

The agent who can answer the district question with real numbers instead of an opinion is the one who gets the second phone call.

Oregon taxes homes on about half of what they are worth, and the half varies by county

Statewide, Oregon’s taxable assessed value came to 52.6% of real market value in fiscal year 2024-25, up from 51.5% the year before. That figure belongs to the Oregon Department of Revenue, published in its annual property tax statistics report, and it may be the most useful number an Oregon agent can carry into a listing appointment.

Two ballot measures produced it. Measure 5, passed in 1990, caps the tax rate. Measure 50, passed in 1997, did something stranger. It reset every property’s assessed value, the figure tax is calculated on, to what the property was worth in 1995-96 minus 10%, then capped growth in that assessed value at 3% a year regardless of what the market did. Real market value has climbed at market speed ever since. Assessed value has crawled at 3%. The two have been pulling apart for close to thirty years.

The League of Oregon Cities states the consequence plainly in its most recent property tax report. Tax bills, it notes, “will differ by thousands of dollars for properties that have the same real market value.” Take two houses on one street: same size, same condition, same sale price. Their owners write very different checks in November. The difference traces back to when each house last changed hands or was substantially improved.

The gap is uneven across Oregon, which is where it becomes useful. Deschutes County taxes property on 40.7% of its market value. Douglas County taxes on 63.0%. Hood River sits at 41.8%, Jefferson at 42.8%, Multnomah at 49.7%, Josephine at 62.0% and Malheur at 63.7%. Those shares come from dividing each county’s assessed value by its Measure 5 value in the Department of Revenue’s fiscal 2024-25 tables.

Effective rates spread just as far. Per $1,000 of market value, Curry County averages $5.02 and Wallowa $5.08, while Multnomah averages $11.71. Statewide the figure is $9.18. On a $600,000 house that works out to roughly $3,000 a year in Curry County against roughly $7,000 in Multnomah, on identical market value.

CountyPopulationCounty seat and principal citiesAssessed value as a share of market valueEffective rate per $1,000 of market value
Multnomah801,477Portland; Gresham, Troutdale, Fairview49.7%$11.71
Washington603,947Hillsboro; Beaverton, Tigard, Tualatin, Forest Grove, Sherwood56.0%$10.06
Clackamas423,975Oregon City; Lake Oswego, Milwaukie, West Linn, Happy Valley, Wilsonville55.6%$9.82
Lane384,207Eugene; Springfield, Cottage Grove, Florence, Junction City50.1%$8.32
Marion349,244Salem; Keizer, Woodburn, Silverton, Stayton55.1%$9.41
Jackson222,645Medford; Ashland, Central Point, Eagle Point, Jacksonville59.9%$8.49
Deschutes206,334Bend; Redmond, Sisters, La Pine40.7%$6.76
Linn130,706Albany; Lebanon, Sweet Home, Harrisburg, Brownsville55.1%$9.39
Douglas112,072Roseburg; Sutherlin, Winston, Myrtle Creek, Reedsport63.0%$6.98
Yamhill108,734McMinnville; Newberg, Dundee, Carlton, Amity51.7%$7.70

County population from US Census Bureau American Community Survey 2024 five-year estimates. Value share and effective rate computed from Oregon Department of Revenue property tax statistics, fiscal year 2024-25.

Some scale for why this carries weight. Residential property makes up 51% of all assessed value in Oregon, or 60% counting land held for residential development. Clackamas, Multnomah and Washington counties together hold 54% of the state’s residential value and pay 54% of the tax. Property taxes imposed statewide reached $9.54 billion in fiscal 2024-25 and have grown an average of 5.1% a year since Measure 50 took effect.

Two older findings deserve naming, both attributed and both dated. Research by The Oregonian in 2015 found that 57% of Portland-area homeowners would pay less under a system based on market value. A 2014 study from the Northwest Economic Research Center at Portland State University concluded that Oregon’s property tax system affects what single-family homes sell for. That second one is the finding agents feel without naming. A buyer carries the tax bill on top of principal, interest and insurance, so the bill shapes the offer.

This is where the ez Home Search property-tax capability earns its keep. The platform pulls tax figures at the state, county, city and ZIP code level and sets them side by side, then runs them against an automated valuation model, an AVM, which is a computed estimate of what a property is worth today. An owner sees what the home costs to hold, beyond the sticker price. In Oregon that combination answers a question almost no owner can answer alone.

Oregon has 36 counties and room for one ez Home Search partner in each. Check whether yours is still open.

The buyer you are chasing is usually the seller you want

Most Oregon agents run two campaigns for what is usually one person.

One campaign says list with me and goes out to homeowners. The other buys buyer leads. They run on separate budgets and separate scripts, sometimes with separate people on the team. Meanwhile the household on the receiving end is doing both things at once.

The Profile of Home Buyers and Sellers, the annual survey the National Association of Realtors runs, puts first-timers at about one in five purchases nationally, close to the lowest share it has recorded. Oregon publishes no clean equivalent, so the national figure is the anchor here and stays labeled national. Turn it over and the other four in five are people with a home to sell before they can close on the next one.

Be precise about what that says. Any one address has two parties, and they are not the same household. What repeats is the individual: across a single move, most people occupy both roles in turn. The buy side comes first for nearly all of them. An owner prices the next house before deciding to list the current one, which is why the agent who shows them what their money buys is so often the agent who ends up taking the listing. The agent who markets for listings and nothing else hands that whole sequence to somebody else.

Now size the seller pool, because a shortage of Oregon sellers is the most common and least accurate thing said about this state. Oregon has 1,084,977 owner-occupied households holding $539 billion in owner-occupied value. Those owners are in unusually good shape. In the first quarter of 2024, 2.2% of Oregon mortgages were past due against 3.6% nationally, and 0.3% were in foreclosure against 0.5%, per Mortgage Bankers Association data compiled by the National Association of Realtors. Oregon sellers list on their own timetable.

Three groups sit inside that pool, and each needs something different.

  • First-time buyers, about one in five purchases, have no home to sell. They need affordability math, plain-language education, and confidence.
  • The dual majority, the other four in five, are trading up, down or sideways. What they need is the equity they are sitting on, a clear read on how the two closings line up, and one agent running both halves as a single move.
  • Seller-only owners are the smallest group. Think of an estate, a landlord winding down a rental, a parent moving in with adult children.

What ez Home Search does with that is read behavior instead of guessing. Someone who runs a valuation, then runs it again four weeks later, or lands on a home-value page, has opened the seller conversation whether they say so or not. Someone who reopens a saved search, reads every alert the morning it arrives, and books a tour is moving on the buy side. Most households run both sequences in turn, and the platform follows the handoff without filing the person as a buyer or a seller up front.

The early part of that sequence is private, and it is often long. A person dreams, then gathers information, then plans, then acts. One spouse will watch the house’s value and browse listings for half a year before the subject ever comes up at dinner. A homeowner facing a major change at home may work the numbers for the better part of a year before telling a soul. Nobody does that research somewhere that converts a single search into a week of phone calls. That confidentiality is why the partner behind the platform is already the trusted name when the person is finally ready to act, on both sides of the move.

What Oregon agents use to find business now, and where each of those runs out

Every method below works. Each one also has a ceiling, and the ceilings are structural, so no amount of effort moves them.

Shared leads. Vendors sell Oregon seller and buyer leads by county and by individual ZIP code, down to 97045 in Oregon City. The volume is real and it arrives fast. The ceiling shows up in three places: your competitors bought the identical record, the household picked nobody, and no one anywhere in the chain holds documentation that the household agreed to a call. What you bought was a race.

Your own IDX website. An internet data exchange feed puts live listings on an agent’s own website, which is a reasonable thing to own. The ceiling is that it compounds slowly and needs constant attention, and the pieces consumers actually return for, accurate valuations and deep school and tax detail, sit behind data and engineering costs no single team or brokerage can carry.

Cold calls and dialers. Few agents realize that a prospecting call or text puts them under the Telephone Consumer Protection Act, which treats them as telemarketers from the first dial. Dispute a call and the person disputing it proves nothing; the agent has to produce documented consent for the number, one number at a time. A single undocumented text is worth $500 to whoever received it, or $1,500 where a court finds the violation willful, and nothing caps the total. Suits of this kind more than doubled in 2025 and most arrived as class actions. A ten-agent team that pushes 3,000 calls through a dialer and cannot document consent on 2,000 of them starts its exposure near $1 million.

Predictive seller scores. Software ranks the names in a database and predicts which owners will list next. Those predictions are often directionally right. The ceiling is that scoring somebody highly does not make them know you. Someone still has to earn the trust that turns a probability into a signature, and that someone is the agent.

Generic all-in-one platforms. They promise every tool in one login. The ceiling is that somebody has to configure and administer them, and that somebody is usually the agent who was supposed to be with clients.

Paid search, social retargeting and direct mail. All three put a name in front of people who might be looking. The ceiling is that nobody bookmarks a postcard. Outbound is all any of them can do, and a past client has nowhere in them to return to.

The mechanism ez Home Search runs on differs in one specific way. It serves the whole lifecycle of owning a home rather than the sliver of people transacting this month. At any moment the share of people inside a transaction tops out around 5% to 10%. Everyone else is living in a home, paying for it, maintaining it, watching what it is worth, weighing a refinance, or thinking about someday. The platform is built for all of them, co-branded to the county partner, so the partner’s name rides on the search itself, on the listing alerts, on the home value updates and on the local market reports those people use for years. When someone’s own activity says they are getting close, the partner hears about it.

The honest trade belongs on the table before anyone gets excited. A partner pays one fee they can predict. Nothing is charged per name and nothing is deducted at closing, so a heavy month shows up in the partner’s income instead of the invoice. The same arrangement holds that fee steady through a light month, which is the part an agent used to buying volume by the unit has to weigh.

What changed for Oregon agents in 2025 and 2026

Oregon rewrote how an agent attaches to a client and how teams get supervised, and both changes reward the agent who was already known.

Since January 1, 2025, Oregon has required a written representation agreement before an agent works with a buyer. The effect is that the value conversation now happens before the first door opens. An agent who arrives a stranger has to make that case cold, in a driveway, to somebody who has not decided anything yet. An agent whose market updates that same buyer has been opening for two years has a much shorter conversation.

HB 3137 is the larger change. Signed in June 2025 and effective January 1, 2026, it creates a designation called the managing principal broker. The role belongs to a principal real estate broker who has registered or assumed responsibility for a business name. That person then carries ultimate responsibility for the professional activity of every associated broker and every branch office under it. Team oversight tightens. The words “real estate” and “realty” are barred from team names, though the legislature may revisit that point. Education requirements now include a standalone state and federal fair housing course, with other continuing education hours rebalanced around it. Stoel Rives and the Oregon Real Estate Agency have each published summaries worth reading before January.

Oregon also does not allow continuing education carryover. Finish 40 hours in a cycle that required 30 and the extra ten evaporate; nothing banks forward.

One more change matters mostly outside the metros. SB 83, passed in the 2025 session, repealed Oregon’s statewide wildfire hazard map along with the property maintenance rules attached to it, and replaced the minimum defensible space standards with a model code the State Fire Marshal develops for local jurisdictions to adopt if they choose. The map had been in place since 2022 and had drawn complaints from rural owners about insurance costs and property values. For an agent listing acreage in Josephine, Klamath, Wasco or Union County, the disclosure conversation shifted, and clients will ask about it.

The direction across all of it is consistent. Oregon keeps raising the cost of meeting a client for the first time at the moment of the transaction. Every one of these changes pays the agent who was already there.

Oregon’s regions do not move together

Oregon runs six regions with six sets of conditions, and an agent who reads the state as one market will price and prospect wrong in most of them.

Aerial view of Bend, Oregon in autumn with Mount Bachelor rising behind the town
Bend held 3.5 to 3.8 months of inventory into January 2026, its healthiest supply since 2019.

Portland metro. The six-county region recorded 17,083 detached single-family closings in 2025. Multnomah accounted for 6,459, Washington 5,046 and Clackamas 3,986, which put 90.68% of regional sales in three counties. Yamhill added 964, Columbia 487 and Hood River 141. The highest-volume ZIP code in 2024 was 97229, covering Cedar Mill and Bethany across the Multnomah and Washington county line, with 729 homes sold; the most expensive was 97034 in Lake Oswego. Those counts come from RMLS data cleaned and published by a regional appraiser, so read them as one analyst’s dataset, short of an official tally.

Willamette Valley. The entire valley sits below the national rental vacancy rate, per Census figures ECONorthwest presented to the Oregon Legislature in January 2025. Renter cost burden, meaning a household spending more than 30% of gross income on rent, runs 56% in Eugene and 54% in Salem, with Gresham at 61%, Medford at 55%, and Portland and Bend both at 50%. Cost burden is a buyer-pool indicator. It tells an agent who wants out of renting and cannot get out yet.

Central Oregon. Bend’s median ran between $700,000 and $731,000 from late 2025 into January 2026, moving roughly zero to 1.6% on the year, on 3.5 to 3.8 months of inventory that The Bulletin described in December 2025 as the healthiest supply since 2019. Redmond‘s median was $510,000 in November 2025, up $19,000 on the year, on about a month and a half. Deschutes County leads Oregon in population growth at 5.55%. These are single-source figures from local reporting and are worth confirming before anyone builds a listing presentation on them.

Southern Oregon. Jackson County inventory rose nearly 24% year over year and Josephine County more than 30%, per Grants Pass reporting in 2026, which is the only published source carrying those counts. Medford’s median of $414,700 is the lowest among Oregon’s dozen busiest markets. Buyers there have choice they have not had in years, sellers wait longer, and prices keep edging up anyway.

Oregon Coast. Second and vacation homes make up an unusual share of the housing stock here, and the rules on how those homes may be used are set town by town rather than in Salem. A coastal listing’s numbers now depend on which side of a city limit it sits.

Columbia Gorge and Eastern Oregon. Growth here is being built more than it is being moved in. Data center construction across Umatilla and Morrow counties pulled in workers, and housing followed: 270 homes going up on East Theater Lane in Hermiston, a 202-unit apartment building in Pendleton that filled faster than its developer expected, and 250 acres opened for development near Interstate 84.

RegionThe trend that defines it right now
Portland metroDetached closings rose to 17,083 in 2025 from 16,872 in 2024, median up 0.84% to $599,990, average days on market lengthening to 59 (RMLS data via a regional appraiser’s annual review, February 2026)
Willamette ValleyThe entire valley sits below the national rental vacancy rate, with renter cost burden at 56% in Eugene and 54% in Salem (Census ACS 2023, via ECONorthwest to the Oregon Legislature, January 2025)
Central OregonBend held a median between $700,000 and $731,000 into January 2026 on 3.5 to 3.8 months of inventory, its healthiest supply since 2019; Redmond reached $510,000 in November 2025 (The Bulletin, December 2025)
Southern OregonJackson County inventory rose nearly 24% year over year and Josephine County more than 30%, with Medford’s $414,700 median the lowest among Oregon’s dozen busiest markets (Grants Pass Tribune, 2026)
Oregon CoastSecond and vacation homes make up so much of the stock that removing them moves Tillamook’s housing-units-per-household ratio from 1.62 to 1.07 and Lincoln’s from 1.42 to 1.10 (Census ACS 2023, via ECONorthwest, January 2025)
Columbia Gorge and Eastern OregonData centers employed about 7,800 Oregonians in 2025, and communities statewide have designated roughly 9,100 acres for more, concentrated in Umatilla and Morrow counties (OPB, September 2025; Lincoln Chronicle)

A single statewide script fails against that spread. The Bend conversation is about choice for the first time in six years. The Medford conversation is about a buyer who finally has room to negotiate. In Hermiston it is about a job that started last month, and in Portland it is about a tax bill that drifted away from the price years ago. An agent who owns one county can hold all of that. An agent trying to cover Oregon cannot.

The counties beyond the metros, where a name still travels

Most of Oregon’s counties are small enough that one recognized name can cover the whole county, and in several of them a large share of the owners do not live there.

Oregon Coast homes set on a grassy hillside above a wide sandy beach
Strip out second and vacation homes and Tillamook County drops from 1.62 housing units per household to 1.07.

Start with the second-home number, because it is the sharpest county-level fact in Oregon housing data. Census figures presented to the Oregon Legislature in January 2025 show what happens when second and vacation homes come out of the housing stock. Tillamook County drops from 1.62 housing units per household to 1.07. Lincoln drops from 1.42 to 1.10. Wallowa goes from 1.29 to 1.11, Clatsop from 1.28 to 1.04, Jefferson from 1.21 to 1.06, and Deschutes from 1.17 to 1.04. Statewide the adjustment takes Oregon to 1.05 units per household against a national 1.11 before any adjustment, which leaves Oregon the second most constrained housing market in the country.

Said plainly: in those six counties a large fraction of the houses belong to somebody who sleeps somewhere else most of the year. Those owners are their own market. They track the value of a property they do not live in, they think about carrying costs more than a primary-residence owner does, and they react fast to a rule change.

The rules are changing. Clatsop County adopted an 8% cap on short-term rentals in unincorporated areas through Ordinance 26-03 on January 28, 2026. Cannon Beach limits new short-term rental permits to 14 days a year. Lincoln City‘s median reached $576,500 in October 2025 under vacation rental rules looser than those in the unincorporated county around it, a single-source figure from local coverage that deserves confirming, though the pattern behind it holds: two towns twenty minutes apart can now carry completely different investment math.

An owner in Beaverton who holds a rental in Rockaway Beach will not learn about a Tillamook County rule change from a Tillamook County postcard. They will learn about it wherever they already track that property. That is the argument for a platform that follows an owner instead of a mailing route.

CountyPopulationCommunities
Benton96,303Corvallis, Philomath, Adair Village, Monroe
Polk89,662Dallas, Independence, Monmouth, Falls City
Josephine88,179Grants Pass, Cave Junction, Merlin, Wolf Creek
Umatilla79,940Pendleton, Hermiston, Milton-Freewater, Stanfield
Klamath70,247Klamath Falls, Chiloquin, Merrill, Bonanza
Coos64,827Coos Bay, North Bend, Bandon, Coquille, Myrtle Point
Lincoln50,964Newport, Lincoln City, Depoe Bay, Waldport, Yachats
Clatsop41,363Astoria, Seaside, Warrenton, Cannon Beach, Gearhart
Wasco26,552The Dalles, Dufur, Mosier, Maupin
Hood River23,905Hood River, Cascade Locks, Odell, Parkdale

County population from US Census Bureau American Community Survey 2024 five-year estimates. City-in-county assignments verified against the Oregon Secretary of State’s Blue Book incorporated-cities listing. Merlin and Wolf Creek in Josephine County, along with Odell and Parkdale in Hood River County, are unincorporated communities rather than incorporated cities.

The same logic runs inland with different specifics. Umatilla and Morrow are absorbing data center growth and the households that come with it. Malheur and Douglas sit near the top of Oregon’s taxable-value range, at 63.7% and 63.0%, which means owners there feel a property tax increase far more directly than a Deschutes County owner does. Benton runs on a university and Polk on the state capital next door. Curry carries the lowest effective tax rate in the state at $5.02 per $1,000 of market value, and Coos holds the working end of the same coastline. Josephine’s listing count rose more than 30% in a year on the Grants Pass Tribune’s figures. Wasco and Hood River split the Gorge between orchards, wind and recreation.

In a county of 27,000 people, one agent can still turn into the name everyone reaches for, which will never be true of Multnomah, and that position keeps paying on every transaction for as long as they hold it.

Remote and hybrid work keeps sending buyers into Oregon’s smaller counties

The coverage says remote work is over. The federal data says it settled.

Crater Lake in southern Oregon, its deep blue water ringed by the caldera rim in summer
Oregon’s smaller and mid-size counties are the geography positioned to absorb lasting remote and hybrid demand.

The Bureau of Labor Statistics logged 36.7 million teleworkers for the last quarter of 2024, people working from home at least occasionally. Twelve months earlier the same count stood at 32.5 million. That is a gain, logged during the stretch everyone described as the return to the office. The Census Bureau then ran the largest employer-side study ever conducted on the question, surveying about 150,000 US firms, and found that 31.2% of them had somebody putting in a full workday from home. Asked to look five years ahead, those employers described the same picture. Pew Research Center found in October 2024 that 75% of US employees with a job that can be done from home are doing some of it there.

The two stories disagree because of a baseline. Measured against May 2020, remote work collapsed. Measured against 2019, it roughly tripled and stayed there.

What that does to land is the part Oregon agents can use. The US Department of Agriculture’s Economic Research Service counted a net 974,000 people moving into rural counties over 2020 through 2024. That ended a losing streak more than a decade long, and the arrivals skewed young: adults from 25 to 44, not retirees. Those are working-age people who brought their income with them.

Oregon has one measurable advantage here that almost nobody cites. In the 2022 Census count, 73.5% of all Oregon households had high-speed internet, against 68.6% nationally, on figures compiled by the National Association of Realtors. The geography positioned to absorb the shift sits outside Portland, in Benton, Polk, Josephine, Wasco, Union and Hood River counties, in the smaller Willamette Valley cities, along the Gorge, and on the coast.

The buyer who arrives that way carries a different list. First on it is a work space with a door on it, either a room inside the house or a separate structure, an accessory dwelling unit, out back. Square footage matters more to them than it did to the commuting version of the same household. And broadband has to hold a video call, which in a rural Oregon county is a street-by-street question the agent should be able to answer before anyone asks it.

Most agents, teams and brokers in Oregon have written this trend off and are prospecting accordingly. That is the opening.

Counties go to one partner at a time. Start the conversation about yours.

What an Exclusive County Partnership actually gives an Oregon agent

A real estate agent shows Oregon real estate leads on a tablet to a seated couple at a dining table, with brochures and a notepad visible.

A county goes to exactly one agent, team or brokerage. Their brand sits on the consumer experience across that whole county, and ez Home Search puts nobody else inside the line. Everything else follows from that structure.

The economics are worth stating early because they run against the category. The partner owns the leads. Nothing is priced by the name and nothing comes off the top of a closing. A busy quarter in Deschutes County shows up in the partner’s income rather than in what they owe.

The connections convert differently because of where they come from. The person arrives having already used the platform and shown real activity on it. The agent opens the first conversation already knowing the kind of home they kept opening, the neighborhoods they searched again and again, and the tour they finally asked for. Weeks of the usual trust-building are already behind them before either one says a word.

The biggest return, though, is already sitting in a database the partner owns today. Go back to the Profile of Home Buyers and Sellers and the numbers on how people pick an agent are lopsided. Sellers contact a single agent 81% of the time. Repeat buyers interview only one in 77% of cases. Reputation outranks every other factor a seller weighs, and 35% name it first. Most clients never run a comparison at all, so the familiar local name has won before the shopping stage everyone assumes exists. Our own numbers put a figure on what that position is worth. Partners reactivate past clients, repeat purchases and referrals both, 2.5 to 5 times the market rate.

Databases decay on their own. Somewhere between 15% and 22% of the email addresses in a list go dead over twelve months, and up to one person in ten swaps a phone number in the same span. That erosion stops when the list keeps using the co-branded search, opening the home value updates and reading the listing alerts, because every visit hands over a working address and a live number. Nobody has to run a cleanup.

Relocation matters more in Oregon than in most states, given how much of the movement here is one county to another. In a given year, Census figures have roughly 2.1% of the country moving across a state line and close to another 3% moving between counties inside one state. Say a past client in Bend starts pulling up Boise listings. That search runs on the partner’s own co-branded experience instead of a legacy real estate portal, so it registers, and the partner calls before the Bend house goes to somebody else. Take national coverage away and both the client and the listing vanish with no warning at all.

The school and tax depth answers the two questions this article already raised. ez Home Search covers more than 149,000 schools with reports at the state, county, school-district and individual-school level, each carrying its own rating and, where they exist, written reviews from parents. A district page shows average prices for single-family homes, condos and townhomes by ZIP code and neighborhood inside that district. Set that against Oregon’s 197 school districts and an enrollment picture that keeps moving, and the partner holds the answer the family is actually searching for. The property tax lookup by state, county, city and ZIP does the same job against Measure 50.

ezVerify.ai takes the legal risk out of the outreach. Opt-in is confirmed and a recording is kept as evidence of it. Every number is screened against a known-litigator database and suppressed if it sits on the Do Not Call registry, all before a call is placed, and the contact detail an agent normally has to dig up arrives already filled in. That is documentation rather than a lead score, and it means the riskiest part of the job arrives already handled.

The conversion tools are built and running from day one, co-branded, because they come from ez Home Search’s own national platform, so the partner assembles nothing. A few clicks produce an AVM widget for the partner’s own site. A few more produce a QR code that signs visitors in at an open house, a home-value page, or an instant cash offer aimed at an Oregon owner who would rather sell quickly than list. None of it lands in a separate inbox either, because ez Home Search is CRM agnostic: a contact’s activity surfaces wherever the partner already works, fullest in Follow Up Boss, where ezNurture runs the automated follow-up inside the platform, and deepest in Sure Send. Support comes with it. Real people work on the partner’s results through coaching every week, a set of sales enablement playbooks, and the Shut Up and Dial events.

Partners holding a county exclusivity tend to say the same thing about their first ninety days. The surprise is how much was already sitting in the database they had.

Counties get claimed one at a time

Four people sit at a cafe table, discussing Oregon real estate leads over a large map, with laptops, a tablet, notebooks, and coffee cups nearby.

Each Oregon county carries a single partner and no more, so whether yours is available changes month to month.

Oregon has 36 of them. Some are already claimed, more get taken each month, and the model works the same in Multnomah as it does in Wallowa. The name people already know is worth as much in a county of 7,553 as it is in one of 801,477. The one thing the model will not do is scale by adding agents inside a territory. There is a single partner, and the territory belongs to them.

That scarcity works as a plain constraint rather than a sales device. Demand for exclusivity has generally run ahead of the counties available, and once a partner holds the position, the recognition compounds year over year in a way no competitor can copy from outside no matter what they spend on it.

Why the model can hand a whole county to one partner comes down to how the consumer side is built. Under The Only Confidential Home Search, what a person enters, their contact details and what they can spend, is never put up for sale, passed around a second time, or pushed out to a crowd of companies they did not pick. One Single Local Expert receives it, someone who knows the area and was matched to what that household needs. ez Home Search names the promise outright: A Better Way To Discover Real Estate. Oregon owners get a search built to keep it.

Be precise about the limits of that promise. It does not mean literal secrecy, and it does not mean a person’s information never goes anywhere. What a person enters reaches a single vetted county partner, the one who serves that area, and the household knows the moment it happens and who received it.

The preference underneath it is broad and it keeps growing. Pew Research Center surveyed more than 5,000 US adults in 2023. Of them, 81% said they were worried about what companies do with the information collected on them, and 73% said they had little or no say over it. About half had walked away from a product or an app on privacy grounds. More than four in ten had moved to a search engine or browser built not to follow them around.

Companies built around that expectation have done well by it. DuckDuckGo and Brave each grew to around 100 million users by making privacy the default. Proton built email the company itself cannot read and passed 100 million accounts. Apple made privacy a pillar it builds products around. 1Password and Bitwarden went further still, engineering their vaults so the company holding them has no way to see inside. Real estate was among the last industries this reached, and ez Home Search got here first.

An Oregon owner who has spent a decade locking down the rest of their digital life will not hand their budget to a form that sells it. They will use the search that does not, and the partner’s name will be sitting on it.

What this comes down to for your county

A real estate agent shows a brochure to a couple standing by the door of a house with a “For Sale” sign, helping them find top Oregon real estate leads.

Most Oregon agents are running the first of three plays. They keep buying names alongside three or four other agents who bought the same name, and they keep paying by the unit in a state where price appreciation stopped doing the work for them. It produces volume. It also produces a race that gets won some of the time.

The second play is to build the thing yourself. That means a search experience people return to, a valuation model accurate enough that owners check it twice, school data at the district level across Oregon’s 197 districts, property tax detail county by county, consent documentation that survives a dispute, and follow-up automation running on top of all of it. The stack costs millions before it produces one lead, and the underlying data alone is priced past what almost any team or brokerage can reach.

The third play is to hold one county on a platform that already has every piece of that built and running, with your name across the whole experience.

The third path carries an honest cost that belongs on the table before anyone signs anything. The cost arrives as one predictable fee, never a price per name, which means it is still there in a slow quarter. And it does not pay in a week. Expect 30 to 60 days of consistent follow-up before the conversion pattern shows up in your numbers. An agent who needs this week’s closing will find that uncomfortable. An agent building a five-year position in Linn or Josephine or Clatsop County will find it cheap.

One number carries the case, so it is the only one worth ending on. ez Home Search partners reactivate past clients, the second transaction and the referral alike, 2.5 to 5 times the market rate. Every bit of it was earned once already and then left uncollected.

Which returns this to where it started. Oregon took in about 17,000 net new residents in the year to June 2025 and holds 1,084,977 households that already own the roof over their heads. The state’s next decade of transactions is sitting inside houses that are already occupied, in counties where one name can still become the name.

See which Oregon counties are still unclaimed.

Frequently asked questions

Why do two Oregon homes worth the same amount get completely different property tax bills?

Because Oregon taxes assessed value, not market value, and Measure 50 froze the relationship between the two back in 1997. Assessed value was set at 1995-96 market value minus 10% and capped at 3% annual growth from there, while market value kept doing whatever the market did. A house that has sat in the same family since the nineties and a house next door that was rebuilt in 2019 can sell for the same number and carry very different tax bills.

Statewide, taxable assessed value came to 52.6% of real market value in fiscal 2024-25, per the Oregon Department of Revenue. The share by county runs from 40.7% in Deschutes to 63.7% in Malheur. Sellers rarely know their own position, and buyers almost never do. The agent who can pull that comparison by county, city and ZIP holds something worth more in Oregon than in any other state.

What does HB 3137’s managing principal broker requirement change about how an Oregon team handles leads in 2026?

It puts one named person on the hook for everything the team does. Effective January 1, 2026, the managing principal broker is a principal real estate broker who has registered or assumed responsibility for a business name, and who carries ultimate responsibility for the professional activity of every associated broker and every branch office under it. Team oversight tightens, and “real estate” and “realty” are barred from team names.

For lead handling, the practical effect is that loose, undocumented prospecting stops being an individual agent’s problem and becomes the managing principal broker’s problem. A lead source that arrives with documented consent and a screened phone number is worth considerably more under that structure than it was in 2024.

Now that Oregon requires a written buyer representation agreement before showings, how do I reach buyers early enough to earn that signature?

By being present before the buyer starts touring. Oregon has required a written representation agreement since January 1, 2025, which moves the value conversation to a driveway with somebody who has not committed to anything. A stranger has to win that conversation cold.

The alternative is to be known already. A buyer who has been using a co-branded search, opening your listing alerts, and reading your market updates for two years is not evaluating you from scratch. ez Home Search partners get that position by default, because the search experience, the alerts and the home value updates carry the partner’s name across the whole county, for years before anybody needs to sign anything.

Where do Oregon listings come from if the state only adds about 17,000 people a year?

From the 1,084,977 households that already own here. Portland State University’s Population Research Center put net migration at roughly 17,000 for July 2024 to June 2025, which is small next to an owner base holding $539 billion in owner-occupied value. Oregon’s transactions come from turnover inside that base. Very few come from outside it.

That is also why nobody should describe Oregon as short of sellers. Nationally, first-time buyers account for about one in five purchases. The remaining four in five arrive with a house of their own to move first. Most of them start by looking at what their money buys, months before they ever consider listing. Reach them then and the listing follows.

Is Central Oregon still worth farming now that Bend has the most inventory it has had since 2019?

Yes, and the case is stronger now than it was two years ago. The Bulletin reported in December 2025 that Bend held 3.5 to 3.8 months of inventory, the healthiest supply since 2019, with the median running between $700,000 and $731,000. Redmond sat at $510,000 in November 2025 on about a month and a half. Deschutes County still leads Oregon in population growth at 5.55%.

More inventory means buyers deliberate, compare and take advice, which raises the value of an agent they already trust. Deschutes also has the lowest taxable-value share in the state at 40.7% of market value, so Central Oregon owners hold an unusually wide gap between what their home is worth and what it is taxed on. That is a conversation worth having every year with people who are not selling yet.

With Clatsop County capping short-term rentals and most coastal owners living inland, where does an Oregon Coast agent find business?

By serving the owners where they actually live. Strip second and vacation homes out of the stock and Tillamook County goes from 1.62 housing units per household to 1.07, Lincoln from 1.42 to 1.10, and Clatsop from 1.28 to 1.04, per Census figures presented to the Oregon Legislature in January 2025. A large share of coastal owners sleep somewhere else most of the year.

The rules keep moving under them. Clatsop County adopted an 8% cap on short-term rentals in unincorporated areas through Ordinance 26-03 in January 2026, and Cannon Beach limits new short-term rental permits to 14 days a year. An owner in Beaverton or Hillsboro will not hear about that from a coastal mailer. They will hear about it on the platform where they already watch that property, which is exactly what a co-branded national platform is for.

08.18.2026

South Carolina Real Estate Leads: Where Your Next Client Lives

South Carolina has grown faster than almost any state, and most of your next deals already live here

South Carolina has been among the country’s fastest-growing states through the 2020s, and in the years ending July 2024 and July 2025 no state grew faster. Across that whole run, the large majority of its home sales have come from people who already lived here. That gap is the opportunity. It is where South Carolina real estate leads are won and lost, and most of the marketing an agent gets pitched points the other way.

Those arrivals matter. In the year ending July 2025 the state added 79,958 residents, the fastest percentage growth in the nation, according to US Census Bureau estimates. In that same year South Carolina closed 91,372 homes. The state holds about 2.12 million households at a homeownership rate of 71.9%, per the Census Bureau’s American Community Survey, which puts roughly 1.52 million owner-occupied households already living here. Even if every arriving household bought a home immediately, newcomers would account for a modest share of the year’s transactions.

Set those figures side by side and the priority changes. Arrivals are the upside. The households already here are the business, and they are the ones an agent can reach first.

Most South Carolina buyers are also sellers, and the state’s listing supply proves it

Most people buying a home in South Carolina are selling one in the same move. First-time buyers are a minority of purchases nationally, and South Carolina’s homeownership rate of 71.9% sits well above the national 65.2%, so the share of buyers here who already hold a house is, if anything, higher. That turns the most common lead-generation mistake in this state into a structural one: treating buyers and sellers as two separate markets. Watch how budget gets allocated. One line goes to listing leads because listings are the prize, another goes to cheap buyer leads because volume is volume, and the two campaigns run as though they were chasing different people.

They are usually chasing the same person at two moments in one move.

The national numbers set the scale. First-time buyers accounted for 21% of purchases as of mid-2025, near the low end of a long slide, and the typical first-time buyer had reached age 40, according to the National Association of REALTORS. The median age of all buyers was 59, and the median owner stayed 11 years before selling. Read that first figure the other way and four in five buyers already hold a house. The ratio is directional rather than exact, because some of them have already closed the sale, some keep the old place as a rental, and some pay cash. Any one closing has a buyer on one side and a seller on the other, two different names. Follow either of them through a full move and the same name shows up on both sides.

Homeowners in South Carolina are listing in rising numbers. New listings across the state rose from 108,948 in 2023 to 120,180 in 2024 and then 131,223 in 2025, the highest count of the ten years from 2016 through 2025, according to South Carolina REALTORS. Those listings came out of a base of roughly 1.52 million owner-occupied households. The sellers are here. The open question is who reaches them before they raise a hand.

That timing problem is what ez Home Search was built for. The platform watches what a person actually does and answers the side of the move that is live. Someone running a valuation or sitting on a home-value page has opened the seller conversation. Someone saving searches and booking tours has started the buy side. Both signals arrive long before either person looks like a prospect to anyone else, because owning a home moves through dreaming, gathering information, and planning well before it looks like a transaction. One spouse will check the value of the house a dozen times before saying a word to the other. The Only Confidential Home Search is what makes that safe: a person explores, saves, and compares while their contact details and their budget stay out of the hands of businesses they never picked, and one Single Local Expert is who they meet instead. The promise ez Home Search makes is A Better Way To Discover Real Estate. Confidentiality is a large part of how it keeps that promise.

The automated valuation model, or AVM, keeps that expert present through the whole stretch. Values land monthly. Equity becomes visible. The buyer an agent met two years ago becomes the listing no competitor saw coming.

What is driving South Carolina’s housing demand

South Carolina’s housing demand runs on several independent engines. No single number explains it. An agent who plans around one of them plans badly, because the engine they picked can stall while the others keep running.

Start with people. The state added 79,958 residents in the year ending July 2025, with 66,622 of that coming from people moving in from other states, while births exceeded deaths by 564, the first natural increase in five years. International migration stayed a minor factor, per US Census Bureau estimates. Size it honestly. Divide that net gain by South Carolina’s average household size and it lands somewhere on the order of 27,000 households, set against roughly 1.52 million owner-occupied households already in the state, so in-migration is a genuine tailwind rather than the main event. It also cuts both ways for an agent. Arrivals are buyers, and the South Carolinians leaving or moving across county lines are listings and relocation business.

Growth is concentrated. Jasper County grew 6.0% in that same year, the fastest rate of any county in the nation, and carried the fastest-growing housing stock in the country for a second consecutive year at 8.3%. Berkeley County grew 3.3% and Horry County 3.2%, with Horry adding 13,244 people, the largest county gain anywhere in the state. Nine of the 46 counties lost population and the other 37 gained. Household formation is the figure that maps most directly onto housing demand, and South Carolina’s household count rose 16.4% between 2010 and 2021 against 11.3% nationally, according to the 2023 Palmetto State Housing Study from the University of South Carolina’s Darla Moore School of Business.

Jobs are the second engine, and they are spread across sectors. Nonfarm employment reached 2,417,300 in December 2025, up 1.4% year over year, and the state set an all-time high of 2,532,080 residents working in March 2026, with health care, private education, and accommodation and food services leading the gains, per the SC Department of Employment and Workforce. New manufacturing keeps arriving on top of that base. Blythewood landed a Scout Motors plant sized at about 4,000 jobs, and a $25 million workforce training center for it opened there in April 2026. Florence County secured an AESC battery plant whose announced investment passed $2 billion, aimed at roughly 2,000 employees. Both sit alongside the long-standing BMW presence in Spartanburg County and Boeing in North Charleston. Freight follows the factories. SC Ports moved 2.6 million twenty-foot equivalent units in fiscal 2025, up 3%, and Inland Port Greer cleared 200,000 rail moves in a twelve-month period for the first time at 205,523, while Inland Port Dillon handled 33,838.

Two slower forces sit underneath. Tourism reached a record $31 billion in economic impact in 2025, roughly $1 billion above the prior high, on figures from the SC Department of Parks, Recreation and Tourism. It lands unevenly. The College of Charleston’s Office of Tourism Analysis put Charleston at $14 billion, up 7%, while Greenville reported $2.5 billion and Myrtle Beach reported a dip of about 3% in occupancy. The state is also aging in a way that reshapes listing supply. Residents 65 and older went from 13.7% of the population in 2010 to 18.1% in 2020, and the South Carolina Revenue and Fiscal Affairs Office projected in February 2025 that this group would overtake the under-18 population in 2027 and reach 21.4% of the state by 2030.

The price bands are pulling apart. Sales above $1 million rose 12.1% to 5,074 in 2025 and are up 39.6% since 2023, while the tier under $150,000 fell 3.3% to 5,274. Two opposite ends of the market now close within a couple of hundred sales of each other. Market time hardly varied between them, running 70 to 77 days from the bottom band to the top.

All of it lands county by county, and one partner holds each county. Check whether yours is still open.

South Carolina’s supply came back, and that changes what a listing costs to win

Start with what the market actually does, measured across a decade instead of a quarter. South Carolina closed 86,017 homes in 2016 and 91,372 in 2025, and it averaged 95,658 closings a year over those ten years, per South Carolina REALTORS. Volume spiked to 116,419 in 2021, fell to a ten-year low of 87,500 in 2023, then rose in both 2024 and 2025. Read whole, that series describes a market fluctuating around roughly 95,000 sales a year, and it is the baseline every other number on this page sits against.

Against that baseline, South Carolina is building and listing at a materially higher rate than it did before the pandemic, and the practical result for an agent is that listings are easier to find and harder to win. The state authorized 45,510 new private housing units in 2025 against 35,618 in 2019, an increase of 27.8%, and it cleared 41,000 units in every year from 2020 through 2025, according to US Census Bureau building-permit data. The six-year run is the story. Any single year inside it is just a data point.

Existing supply followed the same path. Active listings at the end of 2025 stood at 27,641, above the 26,627 available at the end of 2019 and up roughly 157% from the 2021 low of 10,755. Inventory is back near normal. What South Carolina has is neither a glut nor a shortage, but a return to the conditions agents worked in before 2020.

What changed is how much work a listing takes. Days on market went from 48 in 2021 to 72 in 2025, and sellers received 97.9% of list price in 2025 against 99.5% in 2021. Neither figure describes a weak market. Both describe conditions where an agent’s pricing judgment shows up in the result again. A seller who hired on the highest number quoted in 2021 often got away with it. A seller who does that in a 72-day market spends two months walking the price back down, and the comparative market analysis an agent brings to the listing appointment, the CMA, carries more weight than it has in years.

The entry tier moved furthest. Homes selling under $100,000 have declined roughly 14.8% a year since 2014, and in 2022 they fell below 5% of statewide sales for the first time, per the 2023 Palmetto State Housing Study. That shift varies sharply by region. In 2022, sub-$100,000 sales still made up 22.1% of closings in the Central Carolina area and 14.2% in the Pee Dee, against 1.2% around Charleston and 0.8% around Hilton Head. An agent working entry-level buyers in Lake City and one working them in Bluffton hold the same license and run different businesses.

One cost comes with all of that supply. More listings worth pursuing means more competition for each one, and no lead source removes that. Reach does not settle it. The listing goes to the name the seller already had in mind when the conversation started.

How South Carolina’s regions diverge, and what that means for where you spend

Panoramic skyline view of Greenville, South Carolina, the Upstate market that led the state in closed-sales volume
Greater Greenville closed 17,869 homes in 2025, more than any other South Carolina market area.

South Carolina’s regions do not move together, and they have not for years, which is why one statewide lead plan underserves most of them. In 2025 the spread between the state’s fastest and slowest regions looked like this.

South Carolina regional market activity, 2025

RegionCounties coveredClosed salesChangeMedian priceDays on market
The Upstate (Greater Greenville)Greenville, Laurens17,869up 8.5%$319,90053
SpartanburgSpartanburg, Cherokee, Union6,831up 12.9%$292,90045
The Midlands (Greater Columbia)Richland, Lexington, Kershaw, Newberry, Fairfield13,733up 4.0%$278,87750
The Lowcountry (Charleston Trident)Charleston, Berkeley, Dorchester, Colleton17,776down 1.7%$426,70850
The Grand Strand (Coastal Carolinas)Horry, Georgetown16,128up 1.5%$328,000126
The Charlotte border (Piedmont)York, Lancaster, Chester6,643up 7.4%$399,99052

Source: South Carolina REALTORS, 2025 Annual Report on the South Carolina Housing Market.

Read the day counts first. They govern how a pipeline has to be built more than any other number in the table. The Spartanburg area moved homes in 45 days in 2025 while the Grand Strand took 126. An agent in Spartanburg, Boiling Springs, or Duncan works a cycle short enough that a lead going quiet for three weeks is a lost deal. An agent in Myrtle Beach, North Myrtle Beach, or Surfside Beach carries the same seller across four months, which is longer than most lead sources are built to sustain.

The Upstate carried the volume growth. Greater Greenville closed 17,869 homes in 2025, up 8.5%, and Spartanburg added 12.9%, the largest percentage gain of any area in the state. Greenville, Greer, and Simpsonville anchor the first. Spartanburg and Boiling Springs anchor the second. The Midlands sat mid-pack on every measure, with 13,733 closings around Columbia, Lexington, and Blythewood at a median of $278,877.

The Lowcountry moved down on volume and up on price. Charleston Trident closed 17,776 homes in 2025, a decline of 1.7%, at a median of $426,708, with inventory up 25.0% across Charleston, Mount Pleasant, North Charleston, and Summerville. More inventory at a higher price is a listing-side opening for an agent who is already known there. The Grand Strand held close to flat at 16,128 closings, up 1.5%, on a median of $328,000 that slipped 0.6%, which is what happens when condos are 30.5% of everything that sells. In the Pee Dee, condos are 3.9%. Conway and Florence are about 70 miles apart and are not the same business.

The Piedmont posted the fastest price growth in the state in 2025, ahead of both Charleston and Greenville. That band of York, Lancaster, and Chester counties works as Charlotte’s southern suburbs, and its median rose 4.3% to $399,990 on 6,643 closings with inventory up 30.0%. Rock Hill, Fort Mill, Tega Cay, and Indian Land are the names to know there. At the top of the price range, the Hilton Head area held the state’s highest median at $545,000 while the Beaufort area grew closings 11.9%, and at the other end the Pee Dee ran a median of $229,900.

A statewide average describes none of these places.

Where South Carolina’s people live, and why the county is the unit that matters

Aerial view of Columbia, South Carolina homes and tree-lined streets in the Midlands
Columbia anchors the Midlands, one of only seven South Carolina cities above 50,000 residents.

South Carolina has about 5.6 million residents and only seven municipalities holding more than 50,000 people, which tells an agent more about how to organize a business here than most market statistics do. The seven are Charleston at 154,338, Columbia at 139,643, North Charleston at 119,913, Mount Pleasant at 93,993, Rock Hill at 75,259, Greenville at 74,371, and Summerville at roughly 51,900, per US Census Bureau estimates. Add them up and they hold about 12.7% of the state. At the other end of the scale, South Carolina’s 20 smallest incorporated towns each have fewer than 150 residents, according to the South Carolina Revenue and Fiscal Affairs Office.

That distribution is stable. It has shifted slowly for decades and will not change much in the next several years, which makes it one of the few things about this market an agent can build a decade-long plan around.

Population here concentrates by county rather than by city. About 90% of South Carolinians live in half of the state’s 46 counties, per the 2023 Palmetto State Housing Study, and inside those counties a great many of them live in named communities that have no city government at all. Cane Bay and Nexton sit in Berkeley County, Indian Land in Lancaster County, Carolina Forest in Horry County, and Murrells Inlet in Georgetown County. Not one of those is a municipality. Every one of them is a place a buyer names when asked where they want to live, and none of them appears on a list of South Carolina cities.

County-level recognition is therefore what decides who gets the call. The ten largest counties carry the bulk of the state’s transactions, and in four of them the largest city is not the county seat, a distinction worth knowing before an agent decides where to plant a brand.

The ten most populous South Carolina counties and their principal cities

CountyPopulationPrincipal cityNote
Greenville548,166GreenvilleCounty seat and largest city
Richland422,117ColumbiaCounty seat and state capital
Charleston420,264CharlestonCounty seat and largest city
Horry383,016Myrtle BeachLargest city; Conway is the county seat
Spartanburg347,852SpartanburgCounty seat and largest city
Lexington304,887LexingtonCounty seat and largest municipality
York293,673Rock HillLargest city; York is the county seat
Berkeley246,802Goose CreekLargest city; Moncks Corner is the county seat
Anderson210,478AndersonCounty seat and largest city
Beaufort195,289Hilton Head IslandLargest municipality; Beaufort is the county seat

Source: US Census Bureau, 2024 American Community Survey 5-Year Estimates.

A brand that covers a county reaches the metro, the small towns, and every unincorporated community between them. A brand that covers a city reaches a fraction of the people who will buy and sell there.

The counties past the metros, where the local name still wins

Aerial view of downtown Beaufort, South Carolina waterfront and docks in the southern Lowcountry
The Beaufort market area grew closings 11.9% in 2025 on the state’s second-highest median price.

The fastest-growing county in the United States in the year ending July 2025 sat in South Carolina, a long way from Charleston or Greenville. Jasper County grew 6.0%, adding 2,195 people, and carried the fastest-growing housing stock in the country for a second consecutive year at 8.3%, per the South Carolina Department of Employment and Workforce. Ridgeland is the county seat and Hardeeville is the largest community. Neither one shows up on a list of South Carolina’s biggest cities, and one partner holding Jasper County holds both.

Lancaster County shows the same pattern from another direction. The 29707 ZIP code covering most of Indian Land went from roughly 32,800 residents at the 2020 Census to about 37,600 by 2024. It sits in Lancaster County’s panhandle, directly south of Charlotte and Ballantyne, close enough that a household can work on one side of the state line and buy on the other. Indian Land has no municipal government. It has a ZIP code, school attendance zones, and a fast-growing base of owners who, at the national median tenure of 11 years, will be listing those houses well inside the next decade.

The Pee Dee gets dismissed more often than the numbers justify. Inland Port Dillon handled 33,838 rail moves in fiscal 2025, which makes Dillon County a working freight node, and Florence County anchors a real market across Florence, Lake City, and Timmonsville, where Honda South Carolina Manufacturing operates. Median prices there ran $229,900 in 2025. That is a lower price point, and it turns over steadily.

South Carolina counties beyond the big metros

CountyCommunitiesNote
DorchesterSummerville, St. George, Ridgeville, Harleyville, ReevesvilleSt. George is the county seat; Summerville is far larger and extends into Berkeley County
AikenAiken, North Augusta, New Ellenton, Wagener, JacksonNorth Augusta sits on the Savannah River opposite Augusta, Georgia
FlorenceFlorence, Lake City, Timmonsville, Johnsonville, PamplicoTimmonsville hosts Honda South Carolina Manufacturing
PickensEasley, Clemson, Pickens, Liberty, CentralPickens is the county seat; Easley is the largest city
LancasterLancaster, Indian Land, Kershaw, Van Wyck, Heath SpringsIndian Land is unincorporated and sits against the Charlotte line
OconeeSeneca, Walhalla, Westminster, Salem, West UnionWalhalla is the county seat; Seneca is the largest city
GeorgetownGeorgetown, Pawleys Island, Murrells Inlet, Litchfield Beach, AndrewsMarketed as the Hammock Coast
KershawCamden, Lugoff, Elgin, Bethune, CassattCamden is the county seat
JasperRidgeland, Hardeeville, Tillman, Levy, CoosawhatchieRidgeland is the county seat; Hardeeville is the largest community

Source: county government sites, the South Carolina Association of Counties directory, and US Census Bureau municipality records.

Recognition in places like these compounds faster than it does in a metro, because there is less noise competing for it. An agent needs fewer impressions to own the name in Oconee County than in Greenville County. There is no second place for that position.

The remote-work buyer most South Carolina agents are not working

Waterfall in the South Carolina Upstate, the kind of lifestyle market drawing remote and hybrid buyers
Upstate counties like Oconee and Pickens are positioned for the lasting shift to remote work.

Remote work has not gone anywhere. An agent who reads the return-to-office headlines and stops there gives up business in exactly the South Carolina counties where it costs the least to win. Count the people instead. The Bureau of Labor Statistics recorded 36.7 million teleworkers in the final quarter of 2024, up from 32.5 million in the same period of 2023, and the national telework rate over that span went from 20.7% to 23.4%. Both measures rose.

The employer side reads steadier still. The US Census Bureau’s Business Trends and Outlook Survey reached roughly 150,000 American firms from November 2024 through January 2025. Of those firms, 31.2% said someone on the payroll worked a whole day from home, and when the same firms were asked to look five years out, their projection came back at essentially the level they already ran. Whatever a handful of large-company announcements suggest, the employer base is not planning a retreat.

The finding that touches this state directly comes from the USDA Economic Research Service. Its migration work shows rural counties across the country taking in a net 974,000 movers over 2020 through 2024, which ended better than a decade of losses, and it shows the arrivals weighted toward people aged 25 to 44 rather than toward retirees. All of that is a national count. The kind of county it describes is the kind South Carolina has in quantity: Oconee and Pickens in the Upstate, Laurens in the Lakelands, Newberry and Kershaw in the Midlands, Georgetown along the Hammock Coast, and Colleton and Jasper in the Lowcountry.

What this changes at the listing appointment is concrete. A buyer whose paycheck comes from Charlotte, Atlanta, or a company with no office anywhere shops against criteria a purely local move never produces. A door that shuts on a working space is worth money to them. They will ask whether the lot carries a detached structure, or an accessory dwelling unit, the ADU, before anyone gets to the kitchen. Square footage beats walk-to-town. And a house can lose them over its internet service, which partners tell us most listing descriptions in these counties never mention at all.

An agent who leads a Walhalla or Newberry listing with the office, the ADU, and the internet service is answering a buyer almost nobody else in that county is writing for. That edge compounds when one agent holds the whole county. See whether yours is still open.

What South Carolina agents do for leads, and where each approach runs out

Aerial view of Myrtle Beach, South Carolina oceanfront where condos are roughly a third of closed sales
Grand Strand homes averaged 126 days on market in 2025, nearly three times the Spartanburg area figure.

Most South Carolina agents run some combination of seven things. Every one of them works, up to a point. Shared leads bought from legacy portals put names in a pipeline immediately, which is why they stay the default. An IDX website builds an asset the agent owns outright. Cold calling and circle prospecting still produce listings for anyone willing to do the reps. Predictive-seller software surfaces households worth a look. A general-purpose CRM keeps follow-up from falling on the floor. Paid ads and self-produced content put a name in front of people quickly. FSBO and expired farming, open houses, and referral cultivation are the oldest dependable sources in the business, and they are still dependable.

The limits are no secret either. A legacy portal sells the same shared lead to several agents, so the opening conversation becomes a sprint against everyone else who bought that name. An IDX site takes years to earn its ranking and needs feeding every week to keep it, which makes it a slow asset rather than a fast one. Predictive software hands over a score, and a score is not a relationship. A general-purpose CRM is a system the agent has to configure, administer, and keep populated, which is unpaid work stacked on top of the paid work. Ads and content stop producing the week the spend stops.

What makes those limits bite harder in South Carolina is the shape of the state.

Time comes first. A 45-day Spartanburg-area market and a 126-day Grand Strand market do not run on the same pipeline. A lead source tuned to a 45-day cycle starves an agent working a 126-day one, because the follow-up sequence runs dry three months before the client is ready to move.

Reach is the second problem. A meaningful share of coastal owners do not live in South Carolina at all, which is what a 30.5% condo share on the Grand Strand tends to look like from the ownership side. A phone-first prospecting habit reaches that owner worse than anyone else in the state, and every one of those calls still has to clear TCPA consent and the Do Not Call registry.

Economics is the third. Under the rules effective August 17, 2024, sellers no longer automatically pay the buyer’s agent fee, and an agent needs a signed written agreement with a buyer before touring a home. A cold, unqualified buyer lead now costs a conversation and a signature before a single showing. The price of a bad lead went up.

Relationships are the fourth and the largest. South Carolina absorbs tens of thousands of arrivals a year who have no local agent and no local lender. The National Association of REALTORS puts the share of sellers who contact a single agent before choosing at 81%. Most of those arrivals never comparison shop. One name is already familiar to them, and the rest of the market may as well not exist.

ez Home Search answers all four with a single mechanism. A county’s buyers and sellers use a home search that carries the partner’s brand, for years, which turns their own activity into the timing signal and keeps the partner’s name in front of them the entire time. Nobody else is sold that same name. The person arrives already knowing whose platform they have been using, which is why the first call starts somewhere other than the beginning.

What an Exclusive County Partnership changes in a South Carolina county

Aerial view of Spartanburg County, South Carolina, home to BMW manufacturing and the state's fastest-selling market
Spartanburg grew closed sales 12.9% in 2025, the largest gain of any South Carolina market area.

One agent, team, or brokerage takes an entire South Carolina county under an Exclusive County Partnership. Their brand rides the consumer experience across that territory, and no competing partner operates inside the county lines. Leads are not priced individually and closings are not split, so a heavy month pays the partner more without costing them more. That structure is the point. Everything else follows from it.

Start with what arrives. Someone who lands with a partner through ez Home Search brings a readable history: the neighborhoods they went back to, the price band they kept circling, the homes they saved, the second time they ran a valuation. The opening conversation can start with what that person actually wants. Weeks of trust-building are already half done before a word is spoken, and partners typically convert those connections within 30 to 60 days.

The database a partner already owns is the larger opportunity, and most agents let it sit. Repeat and referral business is the least expensive business an agent will ever win, and it leaks for one reason: time. It takes two things to hold a past client, a steady stream of material worth opening and a home search good enough that they come back to it on their own. Almost nobody manages both while also serving live clients. ez Home Search runs the whole apparatus co-branded to the partner, with ezNurture handling automated follow-up inside the CRM the partner already uses, and its partners reactivate past clients, by repeat sale or referral, at 2.5 to 5 times what the market produces on its own.

A database also erodes on its own. Email addresses die off at something like 15% to 22% a year, and a tenth of the people on any list will change a phone number over the same stretch, so a database that looked complete twelve months earlier already has holes in it. That erosion stops when the people on the list keep using a co-branded search, because their current email and phone come back through the platform as they change them.

Relocation is the other leak, and South Carolina has more of it than most states. Census figures show about 2.1% of Americans changing states in a given year and roughly 3% more moving between counties inside their own state. Stay in touch with a client for a decade and those odds add up. A Beaufort County retiree or a Horry County second-home owner who starts shopping a new market does it inside the partner’s co-branded platform, so the move shows up as a signal months early. The partner makes the call while the listing is still theirs to win, and the home they sold that client is the home they list.

Recognition converts all of it. Among repeat buyers, 77% interview a single agent, and reputation ranks as the top factor for 35% of sellers, ahead of anything else they weigh, per the National Association of REALTORS. In a state with seven cities above 50,000 people, that recognition gets earned at the county level or nowhere.

Compliance sits underneath the whole thing. Before an agent dials, ezVerify.ai has already checked the number against a database of known litigators, dropped every number sitting on the Do Not Call registry, established that the person opted in, kept the recording that proves it, and filled out the contact detail an agent would otherwise go hunting for. None of it functions as a lead score. What it produces is documentation, and documentation is what decides a TCPA consent dispute.

The conversion tools show up built and running, because each one belongs to the national platform and simply carries the partner’s name: an AVM widget for their site, a home-value page, an open-house page behind a QR code that signs visitors in, and an instant cash offer for an owner deciding whether to sell fast. Weekly coaching sessions, Shut Up and Dial events, and sales enablement playbooks add people to the partner’s results, which is more than any software does on its own.

None of it happens overnight. A county compounds over quarters, and the partners who do best bring their existing database in on day one instead of waiting for the platform to hand them strangers.

Only one partner holds a South Carolina county

South Carolina has 46 counties and one partner position in each of them. Some are already held. More get claimed every month, and once a county is taken there is no second slot behind it. The position is worth what it is worth precisely because no competing partner operates inside the same lines.

Size is not the variable. Greenville County holds 548,166 residents and Oconee County holds a small fraction of that, and being the recognized local name is worth as much in the smaller one. It may be worth more, since a county with less competition for attention takes fewer impressions to own and holds the position longer once it is established.

What a partner steps into is already running. It works from day one. The listing alerts, the home-value updates, the local market reports, the compliance layer, and the search experience itself all sit inside a national platform used by millions of people, and they carry the partner’s brand from the first week. Nothing needs configuring and nothing needs administering. An agent assembling the equivalent would either buy an all-in-one system and spend months standing it up, or bolt a stack together and spend every week keeping it alive, and on either path the data and the engineering underneath the valuations and the search would stay beyond reach.

Some South Carolina counties are open and some are not, and which is which changes month to month.

Deciding where your South Carolina lead budget goes

Three paths are open to a South Carolina agent or team, and the money goes to one of them whether or not the choice gets made deliberately.

The first is to go on buying shared leads and racing the other agents who bought the same name that morning. It produces volume. It also produces a pipeline the agent never owns, and the price climbs as more agents in Greenville, Charleston, and Myrtle Beach bid for the same inventory.

The second is to build the whole apparatus in house: the search experience, the valuation model, the school and tax data, the alert infrastructure, the consent and compliance layer. Teams do try this. The data sourcing alone sits beyond what any single brokerage funds, and the engineering never reaches a finish line.

The third is to hold a county. That means one partner in one territory, with no charge per lead, no commission split, and a co-branded platform running the follow-up agents never find time for.

Here is the trade-off, stated plainly. A county partnership is a commitment to work a territory, not a switch to flip off after a slow month, and the compounding shows up across quarters. An agent who needs leads this week should buy leads this week.

One number is worth more than the rest of this page. Past clients return to an ez Home Search partner at 2.5 to 5 times the market’s own rate, arriving as repeat business or as a referral. That is business already earned once, and silence is the only thing that takes it away.

Every county in South Carolina will have one recognized name in it a few years from now. Find out whether yours is still unclaimed.

Frequently asked questions

South Carolina’s Upstate and Lowcountry markets do not move together. Does one statewide lead strategy still work here?

It works only with adjustment. In 2025 Spartanburg grew closings 12.9% while Charleston Trident declined 1.7%, and the two carry different price points, different inventory levels, and different buyer profiles. A statewide campaign spends the same dollar against both and gets uneven returns.

The practical fix is to run the plan at county level, which is also how ez Home Search assigns territory. One partner holds one county and works it on that county’s terms.

Condos are roughly a third of Grand Strand sales and a small fraction of Pee Dee sales. How should that change where I spend?

It should change nearly everything about your follow-up. Condos were 30.5% of Grand Strand closings in 2025 and 3.9% in the Pee Dee. A coastal condo buyer is frequently a second-home or investment buyer living out of state, so phone-first prospecting reaches them poorly while platform activity and email reach them well. A Pee Dee agent is mostly serving primary-residence buyers who live a few miles away. The license is the same and the playbook should not be.

Market time on the Grand Strand runs months longer than around Spartanburg. How do I keep a pipeline warm across a gap that wide?

Build the sequence for the longer market and let the shorter one finish early. The gap in 2025 ran 45 days in the Spartanburg area against 126 on the Grand Strand. Most lead-nurture sequences run 30 to 90 days and then stop, which drops a Grand Strand seller out of the sequence before they ever list.

A search experience the client keeps using on their own behaves differently from a drip campaign, because the engagement continues even in the weeks when the agent has nothing new to say.

How does South Carolina’s 4% legal residence versus 6% assessment ratio change the way I follow up with second-home buyers?

It hands you a reason to call that has nothing to do with asking for the listing. South Carolina assesses an owner-occupied legal residence at 4% of fair market value and non-owner-occupied residential property at 6%, which puts 50% more taxable value on the same house. The 4% rate is not automatic. The owner must apply with the county assessor and can hold it on only one property at a time.

Plenty of second-home buyers do not learn this until after closing, and owners who later convert a property to a primary residence have to file for it themselves. An agent who raises it early becomes useful before they are needed.

Are Charlotte-area buyers landing in Indian Land, Fort Mill, and Tega Cay worth targeting as a South Carolina agent?

Yes, and the numbers support it. The Piedmont region of York, Lancaster, and Chester counties posted the fastest median price growth in the state in 2025 at 4.3%, reaching $399,990, with inventory up 30.0%. The 29707 ZIP code around Indian Land counted roughly 32,800 residents at the 2020 Census and about 37,600 by 2024.

These buyers work in North Carolina and buy in South Carolina, so they arrive with no local relationships at all. That is the exact situation where a recognized county name wins the client without a comparison ever happening.

Blythewood and Florence County have landed multi-thousand-job manufacturing plants. How early should a Midlands or Pee Dee agent start working that relocation demand?

Start earlier than feels natural. Blythewood in Richland County landed a Scout Motors plant sized at about 4,000 jobs, and Florence County landed an AESC battery plant whose announced investment passed $2 billion. Scout Motors targeted its first vehicles for 2027 while hiring its first 200 to 400 floor workers by the end of 2026, which is the shape of every plant timeline: the households arrive well before the line runs.

Those households research schools, property taxes, and neighborhoods long before they contact anybody. You reach them during that research stage, well ahead of the transaction, and that is the whole advantage of a platform people use privately for months.

South Carolina has led the nation in population growth. Should new arrivals be where most of my marketing goes?

No, and the arithmetic is not close. South Carolina added 79,958 residents in the year ending July 2025, with 66,622 of that from domestic migration, which works out to something on the order of 27,000 households at the state’s average household size. In that same year the state closed 91,372 homes against roughly 1.52 million owner-occupied households.

Arrivals are genuine business and they are a minority of it. Most of the year’s transactions came from people who already lived here, which is why reactivating a database outperforms buying new leads for most partners who try both.

South Carolina’s 65-plus population is on track to outnumber its under-18 population. What does that mean for a Beaufort or Horry County listing pipeline?

It means your listing pipeline is being assembled by people who have not decided anything yet. The South Carolina Revenue and Fiscal Affairs Office projected in February 2025 that residents 65 and older would pass those under 18 in 2027, and Beaufort and Horry counties concentrate that shift.

There is a tax argument to have with those owners well before a listing conversation. Under the rules in force for the 2025 tax year, a $15,000 deduction opens against any South Carolina income beginning in the year a resident turns 65, on top of a retirement-income deduction of up to $10,000; military retirement income is deducted in full, and Social Security is not taxed by the state at all, per the South Carolina Department of Revenue. Very few owners arrive knowing all of that.

An owner in their late sixties weighing whether to stay, modify, or sell works through that decision across years. They will not open it by calling an agent. They will open it by checking what the house is worth, and the agent whose brand sits on that valuation is the one they call.

08.17.2026

How to Get Real Estate Leads in Each of Oklahoma’s 77 Counties

Oklahoma real estate leads behave one way in the Oklahoma City metro and another way in the southeast, and the gap is wider than most agents assume. In 2025 the Oklahoma City metro sub-market carried 3.3 months of supply and sold homes in 47 days, according to the Oklahoma City Metropolitan Association of REALTORS® annual report on the MLSOK marketplace. In May 2025 the southeastern sub-market covering Pittsburg, Le Flore, Pushmataha and four neighboring counties carried 8.96 months and an average of 75 days, per the monthly inventory analysis compiled from Greater Tulsa Association of REALTORS® data. Both readings describe one state in one year. A house in the southeast takes about half again as long to sell, and the supply behind it would take nearly three times as long to clear.

A pipeline built on one of those numbers misfires on the other. Follow-up cadence lands too early or too late. Ad budgets burn through before a lead is anywhere near ready, and the pricing conversation an agent opens with a seller starts from a premise the local data does not support.

Which of the 77 you work should change what you buy, when you follow up, and what you tell a seller.

Most Oklahoma buyers are selling something first

Roughly four in five people buying a home already own one, which means the buyer riding around with you on Saturday is a listing you have not asked for yet. The National Association of REALTORS® put first-time buyers at 21% of purchases nationally by mid-2025. That is the national figure. No clean Oklahoma-specific first-time-buyer share was available to check it against, so treat the four in five as directional rather than exact.

Most agents run the two halves of one move as two campaigns. One group markets “list with me” and treats buyer work as the consolation prize. The other buys buyer leads by the hundred and waits for a listing to fall out of the pipeline. Both are working the same person twice, badly.

Be precise about what the number means. On any single house in Edmond or Bartlesville, one person buys and a different person sells. Across a move they are usually the same person, working one side and then the other, and they almost always start on the buy side. A homeowner in Yukon studies what their money buys in Piedmont for months before they call anyone about listing. The agent who only chases listings hands those months to whoever the person met while shopping, and that agent earns the listing at the end of them.

The three groups need three different approaches.

  • First-time buyers are about one in five. They have no home to sell, so they need affordability math, plain explanation and confidence. Equity conversations mean nothing to them yet.
  • The buyer and seller majority is roughly four in five. They need the equity in the home they are leaving, the timing between the two sides, and both halves handled as one move rather than two files.
  • Seller-only owners are the minority. That group covers estates, landlords exiting and owners moving in with family, and it is real business in a smaller pool.

A good pipeline reads which side is live rather than guessing. A valuation run a second time, an equity question, a visit to a home-value page: the seller conversation is open. Saved searches picked back up, alerts opened the day they arrive, a tour finally booked: the buyer side is moving. For most Oklahomans it is both, in sequence, and the platform behind the agent should follow that shift instead of picking a lane on their behalf.

Which side moves first varies by county. A Canadian County move at 47 days on market and a Pittsburg County move at 75 are not the same transaction, and they should not get the same follow-up sequence.

What is actually happening across Oklahoma

Aerial view of the Oklahoma City skyline with downtown high-rises and the ballpark, the center of the state's largest real estate market
Oklahoma City anchors Frontier Country and the MLSOK marketplace numbers agents read every January.

Several things are moving at once, and no single one of them explains the state. Start with the market itself.

The market is steady and the shelves are full. Closed sales in the Oklahoma City-area REALTOR® marketplace have run between about 22,300 and 29,800 every year since 2015, averaging roughly 24,831. In 2025 they came in at 24,083, up two years running from the 2023 low. That series is the Oklahoma City Metropolitan Association of REALTORS® count for the MLSOK marketplace, not a statewide figure. Inventory carries the more useful signal. The same marketplace ended 2025 with 7,894 homes for sale, the highest year-end count in eleven years and above the 6,573 of 2015, on 34,003 new listings. Homes still sold in 51 days against 63 in 2015, and the median price moved from $156,000 to $262,900 across the decade.

More people are arriving, from different places and for different reasons. Oklahoma reached about 4,088,380 residents in 2025, up 25,530 on the year and 24th nationally, with growth concentrated in urban and suburban counties. Owasso grew fastest among cities, up 3.5% to nearly 43,000. Net domestic in-migration was 10,534 in 2025, ninth-highest in the country, which is about a quarter of one percent of the population and sits alongside 51,694 international arrivals since 2020. That is modest, and it runs both directions: arrivals are buyers, departures are listings and referral fees. Who arrives matters more than how many. More than 32,000 Texans moved in during 2023, close to 30% of them Generation Z, drawn by housing costs roughly 30% below Texas. Of about 6,300 Coloradans, 38% were Baby Boomers.

Health care is where the job growth sits. Oklahoma added 18,500 nonfarm jobs in 2024, and education and health services supplied 11,700 of them, with health care and social assistance alone at 10,500, according to the Oklahoma Employment Security Commission. Construction added 3,100 and leisure and hospitality 3,200. Unemployment held at 3.1% in July 2025. Energy employment fell from 49,546 in January 2025 to 47,582 a year later, though mining, quarrying and oil and gas extraction was still the single largest contributor to the state’s first-quarter 2025 earnings growth at 1.10 percentage points, with construction second at 0.65 (BEA figures via OESC). The sector now employs fewer people and still produces more income growth than almost anything else in Oklahoma.

Aerospace and defense pay wages in four different counties. More than 120,000 Oklahomans work in aerospace and defense, and the sector produces close to $44 billion in annual activity supporting 206,000 jobs, per the Oklahoma Department of Commerce. Tinker Air Force Base is the largest single-site employer in the state at more than 26,000 people. American Airlines runs the world’s largest single-site commercial aircraft maintenance operation at Tulsa International. Fort Sill generates $1.5 billion and 20,000 jobs in Lawton, and Vance Air Force Base sustains 3,000 jobs and $400 million in Enid.

Tribal nations anchor the eastern half. Oklahoma’s tribal nations contributed $23.4 billion to the state economy in 2023, employing more than 55,000 Oklahomans directly and supporting close to 140,000 jobs on more than $7.8 billion in wages, according to United for Oklahoma and the Oklahoma Indian Gaming Association in June 2025. The Choctaw Nation alone accounts for $4.1 billion and 26,917 jobs, and the Cherokee Nation for roughly $3.1 billion and 14,500 employees.

The newest capital is landing in small towns. Google announced a $9 billion, two-year Oklahoma investment at its Pryor campus on August 13, 2025: expansion at Pryor in Mayes County, a new Stillwater campus in Payne County with phase one targeted for 2027, and two campuses in Muskogee County near Summit and Council Hill.

One number holds the rest together. Homeownership statewide ran 66.8% in 2024, 1.2 points above the national rate, and it ranged from 72.3% in Enid to 59.1% in Lawton. Thirteen points of spread sit inside one state.

Six regions, six different jobs for an agent

Downtown Tulsa at sunset with the Arkansas River behind it, the anchor market of Oklahoma's Green Country region
Tulsa anchors Green Country, where inbound remote workers and data center capital are reshaping demand.

Oklahoma’s own tourism department splits the state into six regions, and each one hands an agent a different lead generation problem to solve. They are Green Country in the northeast, Frontier Country in the center, Great Plains Country in the southwest, Chickasaw Country in the south central, Choctaw Country in the southeast, and Red Carpet Country across the northwest and the panhandle. Oklahomans use these names. That makes them a more useful unit for planning a marketing budget than a state line drawn around 77 counties with almost nothing in common.

Green Country brings in people who picked the region deliberately and arrived carrying an income earned somewhere else, so the agent there is reaching someone researching a place before they ever look at a house. Frontier Country publishes its numbers every January, which means every competing agent in Oklahoma City, Edmond and Norman opens the same report on the same morning. Nobody wins that on information. The edge goes to whoever already owns the relationship when the report comes out.

Great Plains Country runs on a military calendar. Fort Sill moves families on orders rather than on impulse, Lawton carries the lowest metro homeownership rate in the state, and the same houses trade again and again on a schedule an agent can learn in a year. Chickasaw Country asks something else entirely, because the growth in McClain County and the wage base anchored around Ada, Ardmore and Durant put steady buying power into towns that no statewide lead product prices correctly.

The clock runs slowest in Choctaw Country. Homes there take roughly half again as long to sell as homes in the Oklahoma City metro, so a follow-up sequence built for a fast metro sale runs out before the seller is ready to talk. Red Carpet Country sits at the other end, with the highest metro homeownership rate in the state and a resident base that has been in place for years, which makes it a long-tenure market where the reason to call has to be worth the owner’s time.

An agent who plans a year of lead generation off a statewide average is planning for a place that does not exist.

RegionWhereAnchor marketsThe trend that shapes lead generation there
Green CountryNortheastTulsa, Broken Arrow, Owasso, Bartlesville, Muskogee, Claremore, Bixby, Jenks, Tahlequah, PryorTulsa Remote has drawn 3,475 remote workers, 70% of whom still live in Tulsa (Tulsa Remote 2024 Economic Impact Report); Google’s $9 billion Oklahoma investment expands the Pryor campus in Mayes County and adds two Muskogee County campuses near Summit and Council Hill (Google, August 2025; Oklahoma Business Voice, November 2025)
Frontier CountryCentralOklahoma City, Edmond, Norman, Moore, Yukon, Mustang, Guthrie, Stillwater, Shawnee, El RenoThe Oklahoma City-area association’s MLSOK marketplace closed 24,083 sales in 2025 while year-end active listings rose 27.7% to 7,894, the highest count in eleven years (OKCMAR 2025 annual report). Marketplace figures, not a statewide count
Great Plains CountrySouthwestLawton, Altus, Duncan, Elk City, Weatherford, Clinton, AnadarkoFort Sill generates $1.5 billion and 20,000 jobs in the Lawton economy (Lawton Economic Development Corporation); Lawton has Oklahoma’s lowest metro homeownership rate at 59.1% (Census, via USAFacts, 2024)
Chickasaw CountrySouth centralArdmore, Ada, Sulphur, Pauls Valley, Madill, Marietta, Tishomingo, PurcellOklahoma’s tribal nations contributed $23.4 billion and supported nearly 140,000 jobs statewide in 2023 (United for Oklahoma and the Oklahoma Indian Gaming Association, June 2025); McClain County grew 15.11% since 2020, second fastest in the state
Choctaw CountrySoutheastDurant, McAlester, Idabel, Broken Bow, Poteau, Atoka, Hugo, AntlersThe Choctaw Nation generated a $4.1 billion impact supporting 26,917 jobs in fiscal 2023 (Tribal Business News); the region’s REALTOR® sub-market ran 8.96 months of supply and 74.54 average days on market in May 2025 (RE STATS, from Greater Tulsa Association of REALTORS® data)
Red Carpet CountryNorthwest and panhandleEnid, Woodward, Ponca City, Alva, Guymon, Blackwell, FairviewVance Air Force Base sustains 3,000 jobs and $400 million in Enid (Oklahoma Department of Commerce); Enid has Oklahoma’s highest metro homeownership rate at 72.3% (Census, via USAFacts, 2024)

The ten counties where most Oklahoma transactions happen

Aerial view of an Oklahoma suburban neighborhood of single-family homes with green lawns and mature trees
Suburban growth in counties like Canadian and Wagoner is outpacing the two largest counties by rate.

Ten of Oklahoma’s 77 counties carry the bulk of the state’s residential transactions, and Oklahoma County and Tulsa County alone hold roughly a third of everyone who lives here. Add Cleveland, Canadian, Comanche, Rogers, Wagoner, Payne, Creek and Pottawatomie and an agent has covered most of the deal volume in the state without leaving the top ten.

That ranking is not the same as an opportunity ranking, and treating it as one is how agents end up bidding against each other for the same names. The counties expanding fastest sit next to the large ones rather than inside them. Canadian County, home to El Reno, Yukon and Mustang, has grown 24.16% since 2020. McClain County has grown 15.11% and Logan County 12.45%, and neither of those two makes the top ten by size at all. Growth rates and transaction counts point at different maps.

An agent working Oklahoma County is competing with the largest concentration of licensees in the state for a market whose numbers get published every year. An agent working Wagoner or Pottawatomie County is competing with far fewer people for a household base that is still expanding. Both are real businesses. They are not the same business, and the lead generation budget that fits one will not fit the other.

CountyCounty seatOther principal cities
OklahomaOklahoma CityEdmond, Midwest City, Del City, Bethany, Warr Acres, Choctaw
TulsaTulsaBroken Arrow, Owasso, Bixby, Jenks, Sand Springs, Collinsville, Glenpool
ClevelandNormanMoore, Noble, Lexington
CanadianEl RenoYukon, Mustang, Piedmont, Union City
ComancheLawtonCache, Elgin, Sterling, Fletcher
RogersClaremoreCatoosa, Chelsea, Inola, Oologah, Verdigris, with Owasso extending into the county
WagonerWagonerCoweta, Porter, Okay, with Broken Arrow extending into the county
PayneStillwaterCushing, Perkins, Yale, Glencoe
CreekSapulpaBristow, Kiefer, Mounds, Drumright, Kellyville
PottawatomieShawneeTecumseh, McLoud, Earlsboro, Asher

The Oklahoma outside the two metros

Aerial view of Tenkiller Ferry Lake in eastern Oklahoma at sunset, with wooded hills and a marina
Eastern and southeastern Oklahoma counties run a longer sales cycle than the metros, and a different pipeline.

Outside the Oklahoma City and Tulsa metros, the sales cycle stretches. Where the association numbers are published, homes take roughly half again as long to sell, and that is a pipeline design question rather than a reason to write those counties off. In 2025 the Oklahoma City metro sub-market carried 3.3 months of supply, sold homes in 47 days and returned 98.3% of list price (OKCMAR 2025 annual report). In May 2025 the REALTOR® sub-market covering Haskell, Latimer, Le Flore, McIntosh, Pittsburg, Pushmataha and Sequoyah counties carried 8.96 months of supply, averaged 74.54 days on market and returned 94.77% of list price (RE STATS monthly inventory analysis, compiled from Greater Tulsa Association of REALTORS® data). One state, one year, and the second market needs nearly triple the time to absorb what it has.

An agent who moves a marketing budget from one of those to the other without changing anything else will watch the cost per closing rise and never learn why. Follow-up sequences run out. Ad spend keeps buying clicks for a house that has not sold yet. Seller pricing conversations get set against a metro number the seller’s own county never produces.

The divergence does not stop at the metro line either. Inside the Oklahoma City marketplace in 2025, closed sales rose 17.0% in the 73044 area and fell 14.4% in Midwest City, while median price rose 31.9% in 73142 and fell 9.9% in 73089 (OKCMAR 2025 annual report). Two ZIP codes in one metro moved 40 points apart on price. The county is the right planning unit across most of Oklahoma, and inside the metro even a county line paints too broadly.

There is a business consequence in the slower counties that most agents read backward. A longer sales cycle punishes whoever is renting attention and rewards whoever owns the relationship, because the person paying per lead pays again every month the house sits while the person who is already the recognized local name simply stays in the conversation. County exclusivity is worth more in a county running 75 days than in one running 47, not less. The slow markets are where a per lead budget bleeds and where a held territory compounds.

If you work one of these counties, the first thing worth knowing is whether anyone else has already claimed it. Check whether your Oklahoma county is still open.

CountySeatOther communities
BryanDurantCalera, Caddo, Colbert
CarterArdmoreHealdton, Wilson, Lone Grove
PittsburgMcAlesterKrebs, Hartshorne, Kiowa
Le FlorePoteauHeavener, Spiro, Talihina
McCurtainIdabelBroken Bow, Valliant, Wright City
GarfieldEnidCovington, Garber, Waukomis
WashingtonBartlesvilleDewey, Ochelata, Ramona
DelawareJayGrove, Kansas, Colcord
MayesPryorChouteau, Salina, Locust Grove
MuskogeeMuskogeeFort Gibson, Warner, Council Hill, Summit

The remote-work buyer most Oklahoma agents stopped looking for

Woman wearing a headset sits at a desk with a laptop and two monitors, jotting down Oklahoma real estate leads during a video call in a bright home office.

The buyer who works from home and can therefore live almost anywhere is still moving, and Oklahoma has spent the past two years making far more of its counties livable for that person. Most agents quit chasing this buyer around 2023, when the return-to-office headlines started. The headlines were about a few very large employers. The measured national numbers went the other way.

Bureau of Labor Statistics telework figures reached 36.7 million Americans in the fourth quarter of 2024, a rise from 32.5 million twelve months earlier, and the telework rate moved from 20.7% to 23.4%. A Census Bureau survey of about 150,000 firms, fielded from November 2024 into January 2025, found that employers expect roughly as much work from home five years ahead as they had at the time they answered. Both are national figures. So is the third one that matters most for Oklahoma: the USDA Economic Research Service finds rural counties gained 974,000 net migrants between 2020 and 2024, concentrated among working-age adults between 25 and 44 rather than retirees.

Oklahoma’s own contribution is the part almost nobody has priced in. The Oklahoma Broadband Governing Board has awarded roughly $525 million in grants, more than $840 million once provider matching funds are counted, across more than 180 projects. At least one of those projects is slated in 59 of the state’s 77 counties, with more than 69,000 homes and businesses approved for service (Oklahoma Broadband Office, July 30, 2025). The detail runs to the county. Pine Telephone is running $58.8 million of fiber across Choctaw, Latimer, Le Flore and McCurtain counties, connecting 1,512 homes and businesses, including virtually every home and business in the Choctaw County town of Grant. Atlas Broadband won $17.1 million across Rogers, Osage, Nowata and Tulsa counties. Hilliary is connecting 2,007 locations across eleven counties from Atoka and Comanche to Pittsburg and Washita.

Tulsa proved the demand side locally. The W.E. Upjohn Institute found that Tulsa Remote returns more than $4 in benefits for every $1 spent and creates jobs six times more efficiently than comparable business tax incentives, with 58% to 70% of participants representing genuine program-induced moves against “but for” rates typically below 25% for business incentives (Economic Innovation Group and SSTI, 2025). Brookings found in 2022 that participants gained about $26,500 in real annual income after moving.

A county that could not support a remote worker three years ago can support one now. That buyer shops for things the local listing description usually leaves out: an office that shuts, a detached building or accessory dwelling unit to work from, more square footage than a city budget bought, and a connection fast enough to hold video calls all day. The counties getting fiber are the counties most agents have already written off.

Why lead generation is harder in Oklahoma, and why it gets harder as you grow

Lead generation is harder in Oklahoma than the national advice accounts for, and it gets harder as an agent adds people. Three forces drive that: the state’s own numbers refuse to support one playbook, most of what an agent can buy captures demand that already exists rather than creating any, and the informal system that carries a solo agent starts failing at three agents and breaks at ten.

Start with the numbers, because they set the terms. An agent who builds a system around 47 days on market and 3.3 months of supply has built a system that misfires in a county running 75 days and 8.96 months. Follow-up cadence keys off the sales cycle. So does ad budget pacing, the pricing conversation with a seller, and the cash flow planning behind both. Within the Oklahoma City marketplace alone, 2025 closed sales rose 17.0% in the 73044 area and fell 14.4% in Midwest City (OKCMAR 2025 annual report), so even a metro-wide assumption breaks before it reaches the county line.

The second reason is the one most agents never name. Almost everything on the market reaches a person who has already started looking. Shared leads, paid search, social ads and portal placement all work the same way at the root: they find someone whose search is already underway. That group is small in any county at any moment, and every agent nearby is bidding for the same slice of it. The far larger group has not started looking yet, will move eventually, and can only be reached by something that runs in the background for months without an agent having to think about it. That gap explains a pattern I have watched play out at company after company that sells to agents: the lead budget rises every year while the pipeline stays flat.

Third, what works for one agent stops working at three. A solo agent’s pipeline runs on memory and relationships. That is a system with one point of failure and no documentation, and it holds up fine until volume arrives. Growth is the pressure that exposes it, and the cracks show in the same places every time. Leads route to whoever answers first rather than whoever is right for the client. Follow-up quality varies by person. The database fragments across individual phones and inboxes, and nobody owns the contacts that went cold.

The database problem has a size, and Oklahoma’s own tenure numbers set it. NAR reports a national median of 11 years in the home before an owner sells, so the average past client is years away from listing and the contact record decays the entire time. A meaningful share of email addresses stop working every year, on the order of 15% to 22%, and roughly one homeowner in ten changes a phone number. A list that looked complete in 2023 is partly unreachable now, and the past clients who slip off it are usually the ones most worth keeping.

Consistency is a property of the system an agent runs, and no amount of effort inside a single month substitutes for one. Each of those three problems has a practical answer, and most of them are worth trying before anyone buys anything.

What Oklahoma agents do today, and how to do each one better

Oklahoma agents run about seven plays to generate business, and every one of them can be improved without spending another dollar. Each also has a ceiling worth knowing before the budget goes in.

  • Shared leads from legacy portals and lead marketplaces. Better version: buy at the smallest geography the source will sell you, and measure cost per closing county by county, because cost per lead hides the answer. A blended number that averages a 47-day county with a 75-day county describes neither, and it buries which half of the spend is working. The ceiling is structural. That same name still reaches several agents, so the purchase is a race for the first callback.
  • Paid search and social with retargeting. Better version: run a separate campaign per county and pace the budget against that county’s actual days on market rather than a statewide assumption. Put the money behind a home-value or neighborhood-report offer. A listing carousel captures a browser; a value offer captures an owner. The ceiling: it produces while the budget runs and stops producing the day the budget stops.
  • An IDX website. Better version: give people a reason to come back, with saved-search alerts and a monthly value update, and publish for the actual towns in the county. Pages about Chouteau and Locust Grove face almost no competition; pages about the metro face all of it. The ceiling, stated plainly: this takes longer than the vendors suggest, and a self-hosted site cannot match minute-level listing refresh, so the alert lands after the tour is already booked.
  • Cold calling, circle prospecting and door knocking. Better version: work from a trigger instead of a list. Oklahoma supplies real ones, including a PCS cycle at Tinker, Fort Sill, Vance or Altus, a plant or campus announcement in a small county, and the long-tenure owner whose assessed value has drifted away from the market, which the next section covers. The ceiling is consent exposure, and it is serious enough to have its own section further down.
  • Predictive-seller scoring. Better version: let the score decide who gets called first, then still make the call yourself, and pair every scored name with a reason the homeowner would recognize as useful. The ceiling: a score is a guess about a name, and the relationship behind that guess is still the agent’s to build.
  • A CRM plus content the agent writes. Better version: pick one repeating asset the agent will genuinely sustain, a county market note or a monthly value-update email, automate its distribution, and resist adding a second and a third channel. The ceiling: the agent ends up operating software when they should be serving clients, and output falls off in a busy month, which is exactly the month the pipeline needed it.
  • Referrals and past clients. Better version: treat the database as an owned asset, rebuild it with current contact details, and give yourself a standing reason to stay in touch that does not depend on remembering. The ceiling: keeping a list current by hand does not scale, and an 11-year median tenure means the payoff arrives years after the work.

Every one of those is worth doing better. The mechanism ez Home Search runs has a different shape. It is a confidential home search a person returns to over years, with intent read from their own activity. The consumer chooses the connection, and one partner holds the entire county, with no per-name auction anywhere in it. Opportunities that arrive this way typically convert in 30 to 60 days, because the person already trusts the platform their agent’s brand sits on. What we hear from the county exclusivity partners running this model in markets like Ardmore and Claremore is that the difference shows up on the first call, when the agent already knows which neighborhoods the person has been searching and which homes they keep coming back to.

Before the next budget cycle, find out whether your county is even available. See whether the Oklahoma county you work is still unclaimed.

Reasons to call an Oklahoma owner who is not moving

Oklahoma state flags flying in front of the Oklahoma State Capitol building in Oklahoma City
Article 10, Section 8B of the Oklahoma Constitution caps annual growth in a property’s fair cash value.

The best reason to call an Oklahoma homeowner who has no plans to move is that their county has been telling them something about their house that stopped being true years ago. People sell because of a job, a divorce, a death, a birth or a retirement. No tax provision has ever made anyone move, and any agent who pitches one as a motive will be seen through immediately. What a trigger does is earn the agent a place in the conversation before the job offer or the diagnosis arrives.

Oklahoma hands agents a good one. Article 10, Section 8B of the Oklahoma Constitution caps the annual increase in a property’s fair cash value at 3% for homestead property and agricultural land, and at 5% for everything else (Oklahoma Constitution, via Wagoner County and the Tulsa County Assessor’s Property Taxation 101). Alongside it sit the $1,000 standard homestead exemption and the Senior Valuation Limitation, which for a qualifying owner aged 65 or older locks the taxable fair cash value in place. That last one is widely misunderstood, including by the people who have it: the limitation holds the value, and it does not freeze the tax bill itself. The income test runs off a county-level HUD figure that resets every year, so the threshold in Tulsa County differs from the one in Garfield County.

Over ten years that cap compounds into a real gap. NAR reports a national median of 11 years in the home before an owner sells. Across that same stretch, the median sale price in the Oklahoma City-area marketplace moved from $156,000 in 2015 to $262,900 in 2025 (OKCMAR annual reports). An owner who has been in place since 2014 has watched a capped number arrive in the mail every year while the market did something else entirely. The figure in their head is the assessment, and it is the wrong number by a wide margin.

That is a reason to make contact, and it holds whether or not the owner is thinking about selling at all. An accurate automated valuation model (AVM), a co-branded home-value page and a monthly value update turn that gap into a conversation an agent never has to invent. A proposal to lower the caps to 1.75% for homes and agricultural land and 4% for other property has been put to Oklahoma voters, which is worth knowing and is not yet law.

One agent, one Oklahoma county, every lead in it

An Oklahoma real estate agent walking two clients toward a two-story home during a showing
One partner per county means the same agent serves that client through every move that follows.

The Exclusive County Partnership hands one agent, team or brokerage an entire Oklahoma county. The consumer experience carries that partner’s brand. No second partner works the territory, nothing is billed per name, and the commission on a closing stays whole. A partner in Canadian County holds Canadian County. That does not mean a ZIP code inside it, a shared queue with three other agents in Yukon, or a monthly invoice that swells the month the leads finally show up.

The difference is what comes attached to the opportunity. Someone arriving through ez Home Search carries a record the agent can read: which homes they kept opening, which neighborhoods they returned to week after week, where their price kept settling, and the valuation they ran a second time. The first call starts where a normal first call ends. That is why these opportunities typically convert in 30 to 60 days, and why the relationships behind them tend to run for years rather than a single closing.

The reach behind it is the part no single agent in Bartlesville or Durant could assemble alone, and that is not a knock on anyone’s ambition. The proprietary automated valuation model covers more than 90 million US residential properties in the public-records and valuation universe. The proprietary ez rating covers more than 160,000 schools nationwide. Listing data refreshes every minute around the clock, against a category norm measured in days. A platform like that costs millions of dollars and years of engineering before the first consumer ever sees a page, and the partner receives it already running, with their name on it.

Most lead sources chase the people who are shopping this month, which in any Oklahoma county is a small fraction of the households in it. The rest are watching their equity, saving homes they cannot buy yet, and sitting a year or two from a move they have not mentioned to anyone. The largest and cheapest return available to a partner sits inside that group, in the database they already own. That same 11-year median tenure means a past client is usually years from listing while their contact record decays out of sight, with email addresses failing at a steady rate every year and phone numbers turning over for about one owner in ten. ez Home Search keeps those records current because the people in them keep coming back to the co-branded search, and partner reactivation of past clients runs 2.5 to 5 times the market rate.

None of it works without the consumer trusting the platform first, which is the point of the two promises underneath it. The Only Confidential Home Search means the budget and the contact information a person enters stay out of the resale market, never recycled and never pushed to a list of businesses they did not pick. The Single Local Expert means one vetted partner who works that county is matched to them, picked as the right fit for what they need. Held together, those two promises are what ez Home Search means when it says A Better Way To Discover Real Estate, and they are why a buyer in Owasso or Enid engages honestly enough for an agent to be useful.

Own the county and you stop renting attention in it.

When an Oklahoma client moves to Texas, you should hear it first

A pyramid diagram shows Oklahoma real estate leads hierarchy: high-value leads at the top, medium-value in the middle, and volume leads at the bottom, each with examples.

An agent should learn about a client’s move to Texas from the client’s own search activity, months before a listing agreement is signed with somebody else. Texas is Oklahoma’s largest source of new residents, sending more than 32,000 people north in 2023 alone, and it is also one of the most common places Oklahomans go. The traffic runs both ways every year, in every metro in the state.

Name the loss precisely, because most agents mourn the wrong half of it. The purchase in Dallas or Houston was never available to an Oklahoma agent, license limits being what they are. The deal that was genuinely theirs is the house in Edmond, Bixby or Broken Arrow that the client is about to list. That one leaves too, and it leaves for a specific reason: while pricing the new market, the client met an agent on a legacy portal, and the person who answered a question about Frisco is the person who ends up recommending a listing agent back home.

The scale is steady enough to plan around. Census figures put annual state-to-state moves at about 2.1% of Americans, and another 3% or so move to a different county inside their own state. Roughly one person in twenty relocates past the area a single agent or team serves, every year, and every one of them owns or rents a home they are leaving behind.

National coverage closes the gap. The platform runs in all 50 states, so a client pricing Dallas does it on their own agent’s co-branded platform instead of leaving for a portal, and those searches surface to the agent as an early signal. The agent calls before the move is public, handles the sale of the Oklahoma home, and refers the Texas purchase to a vetted agent there for a referral fee. The client moves. The relationship does not.

Proof of consent on every Oklahoma opportunity

Two professionals in a modern office discuss Oklahoma real estate leads, sales growth charts, and financial data; laptops, documents, the state seal, and “ez” logo are visible.

Every opportunity ez Home Search sends an Oklahoma partner arrives with documented consent already attached, which removes the single largest legal exposure in prospecting. Most agents never learn that the law treats them as telemarketers the moment they pick up a phone or send a text to someone who has not asked to hear from them. Circle prospecting in Edmond and door-to-door follow-up calls in Lawton sit squarely inside that definition.

The part that surprises people is where the burden lands. If a recipient disputes consent, that person does not have to prove they never agreed. The caller has to produce proof of consent for the number dialed. Every call or text made without that proof exposes the caller to $500, a willful violation runs to $1,500, and no ceiling sits on the total across a campaign. Do Not Call complaints reaching the Federal Trade Commission passed 2.6 million in fiscal year 2025, though federal enforcement is not the exposure that finds a working agent. The exposure that reaches an agent or a ten-person team is the private lawsuit, which any consumer can file on their own and which plaintiffs’ firms increasingly file as class actions.

ezVerify.ai handles that before an Oklahoma partner ever dials. It confirms the person opted in and keeps a recording that proves it, cross-references the number against the national Do Not Call registry, screens it against a known-litigator database, and supplies contact detail the agent would otherwise spend an afternoon chasing. Scoring tools guess which homeowner might sell. This one documents which person agreed to be contacted, which is a different job entirely.

What changes day to day is the confidence. The riskiest task on an agent’s calendar is the outreach, and here it is documented before the call is placed.

Seventy-seven counties, and they are not all still open

Oklahoma has 77 counties, one Exclusive County Partner apiece, and several of them are claimed every month. There is no waiting list that reopens a territory once a partner is in it, because the whole value of the position depends on nobody else holding it. An agent who has been thinking about this for a quarter may find their county spoken for by someone who thought about it for a week.

The operational lift surprises agents who have been burned by a software rollout, because there is almost none. A partner joins a platform that millions of people already use, carrying their own brand across it, and it produces from the first day. Nothing needs configuring, no system needs an administrator, no integrations need sequencing, and no six-week onboarding stands between the partner and the first opportunity.

The model does the same work in Osage County that it does in Oklahoma County, and that is the part small-market agents tend to doubt. The recognized local name matters at least as much in a rural county as in a metro, because of how people choose an agent. The National Association of Realtors finds that 81% of sellers choose without ever contacting a second agent, and that 77% of repeat buyers interview only one. Most clients never run a comparison at all. They call the name they already associate with real estate where they live, and that name gets decided long before anyone picks up a phone.

That name is available in each Oklahoma county exactly once.

What an Oklahoma agent should do about this

A real estate agent shows two men a property listing on a tablet inside a bright, modern living room, connecting with quality Oklahoma real estate leads.

An Oklahoma agent has three real paths from here, and only one of them changes the arithmetic. The first path is the status quo, which means buying more shared leads priced as though Bartlesville and Edmond were the same market and competing on how fast you can dial. It still produces closings. It also produces a cost per closing that rises every year while the pipeline stays where it was.

The second is to hold one Oklahoma county outright and let the platform work the entire homeownership lifecycle inside it, from the dreamer saving homes in Jenks to the owner in Ponca City who has been in place since 2013 and has no idea what their house is worth.

The third is to build the equivalent yourself. That means national data ingestion, a valuation model accurate enough to send an owner every month, listing data that refreshes by the minute, a compliance layer that documents consent, and a co-branded content engine that keeps running during your busy season. It costs millions of dollars and takes years, and no single team or brokerage in Oklahoma is going to get there.

The trade-off in the second path deserves stating plainly, because it is the one that makes agents hesitate. County exclusivity is a flat fee, and a flat fee does not shrink in a slow month the way a lead budget does. The database reactivation that drives most of the return compounds over quarters, so the first ninety days feel quieter than the second year. That is the honest shape of it.

One number is worth carrying out of this. Partner reactivation of past clients, through repeat business and referral, runs 2.5 to 5 times the market rate. Those are clients the agent already earned once and would otherwise never see again.

Find out where your county stands before someone else does.

Every Oklahoma county already has a name people call first. In most of the 77, that name is still being decided.

Frequently asked questions

Homes in southeastern counties like Pittsburg, Le Flore and Pushmataha sit for about 75 days against 47 in the Oklahoma City metro. Is a county down there worth building a pipeline in?

Yes, provided the pipeline is built for that clock rather than borrowed from a metro. The REALTOR® sub-market covering those counties ran 8.96 months of supply and 74.54 average days on market in May 2025 (RE STATS, from Greater Tulsa Association of REALTORS® data), so nurture sequences need to run longer and ad pacing needs to stretch.

The other half of that math favors you. Fewer agents are competing for each listing, and the agent who is already the recognized name does not have to win an auction every time a house comes up. The clock that costs a per-lead buyer another month of spend costs a county partner nothing.

The Oklahoma City-area MLS ended 2025 with more homes on the market than any year since 2015. Does that mean more listing opportunity, or more competition?

Both, and the two show up in different places. The MLSOK marketplace ended 2025 with 7,894 active listings, the highest count in eleven years, along with 34,003 new listings, and it still closed 24,083 sales in 51 days on average against 63 days back in 2015 (OKCMAR annual reports). More sellers came to market and the market absorbed them.

The opportunity is at the seller level, since every one of those listings started with an owner who chose someone. The competition is at the individual listing level, where more choice means pricing and presentation matter more than they did in 2021.

Google is building data centers in Pryor, Stillwater and Muskogee County. Is that real housing demand for an agent in Mayes, Payne or Muskogee County, or just construction traffic?

Both, in sequence, and the sequence is what an agent should plan around. Google announced a $9 billion Oklahoma investment on August 13, 2025, expanding the Pryor campus in Mayes County, adding a Stillwater campus with phase one targeted for 2027, and siting two Muskogee County campuses near Summit and Council Hill.

Construction phases bring rental demand and temporary residents. Operations phases bring salaried households that buy. The second wave lands years after the announcement, which means the agent who becomes the known name in Pryor or Council Hill during the construction years is the one who meets the operations hires.

Oklahoma caps how fast a home’s taxable value can rise. Is that a useful reason to reach out to a long-time owner, or is it a gimmick?

It is useful, as long as it is used as a reason to make contact and never as a claimed motive to sell. Article 10, Section 8B of the Oklahoma Constitution caps annual growth in fair cash value at 3% for homestead property, so an owner who has been in place a decade has been reading a number that drifted away from the market years ago.

It holds up because the owner can verify it themselves. Any conversation that starts with information a homeowner can check is a different conversation from one that starts with a pitch.

More than 32,000 Texans moved to Oklahoma in a single year and close to 30% were Gen Z, while most of the Coloradans arriving were Boomers. Should I work those two buyers the same way?

No, and treating them alike is how an agent loses both. Of the 32,000-plus Texans who came in 2023, close to 30% were Generation Z, drawn largely by housing costs around 30% below Texas (Greater Oklahoma City Economic Development, April 2025). Of roughly 6,300 Coloradans, 38% were Baby Boomers.

The Gen Z arrival is usually making a first purchase and needs affordability math, financing guidance and patience. The Boomer arrival is usually moving equity, often shopping single-level homes near medical care, and moves fast when the right property appears. They search different counties at different price points and they respond to entirely different outreach.

Tinker, Fort Sill and Vance move people on a schedule. How do I get in front of a military seller in Midwest City, Lawton or Enid before the orders turn into a listing?

Be present before the orders exist, because once they arrive the seller has weeks and calls whoever is already familiar. Tinker Air Force Base alone employs more than 26,000 people, and the base-adjacent ZIP codes in Midwest City, Lawton and Enid turn over the same houses repeatedly.

The practical move is a standing value relationship: a monthly home-value update on the property they bought when they arrived, so the number is already in hand when the assignment changes. A service member who has watched their equity for two years does not need a listing presentation. They need a call returned the same day.

08.16.2026

Wyoming Real Estate Leads: Where the Buyers Are Moving

Most of Wyoming’s growth is happening outside the city limits

About 31% of Wyoming residents live outside any incorporated town. Since the 2020 Census the state has grown at twice the rate of its eleven cities and towns over 10,000 people, and in Laramie County, the largest county in the state, rural residential prices rose 172% between 2005 and 2025 against 145% inside the city.

Almost every source of Wyoming real estate leads points at the towns. Farming, door knocking, circle prospecting, neighborhood pages, and shared leads from legacy real estate portals priced by city all reach the incorporated two-thirds, where the homes cost less, the growth is slower, and every competitor in the county is already working.

Cheyenne added more residents in 2025 than any other city in the state. The country around it grew faster, and almost nothing an agent can buy is built to find the people moving there.

Most Wyoming buyers are selling a home to buy the next one

First-time buyers fell to 21% of US purchases in the year ending June 2025, the lowest share the National Association of REALTORS® has recorded since it began tracking in 1981. The other 79% already own a home. They sell it to buy the next one.

Wyoming has more of those owners than most states. Its homeownership rate has run above the national rate in every year since 2000 and reached 73.7% against a national 65.2% in 2025.

The seller you want and the buyer you paid for are frequently the same household, six months apart. Most marketing treats them as two households: a “list with me” campaign aimed at one, purchased buyer leads aimed at the other, and nothing connecting the two files.

That split gets more expensive in Wyoming every year. The state recorded the largest drop in births of any state between 2014 and 2019, at 14.7%, and its annual natural increase, births minus deaths, has fallen under 400 people against 1,446 in 2019. Fewer Wyoming-raised first-time buyers are coming. The owners already here are the market, and they will be for the next decade.

Three groups buy differently. The first-timers, one purchase in five nationally, have no equity behind them and need affordability and guidance. The owners who make up the other four in five need the money tied up in the current house, the timing between two closings, and both sides run as one move. Seller-only owners, mostly estates and landlords getting out, are the smallest of the three.

ez Home Search follows the behavior instead of guessing which group someone belongs to. Two valuations in a year, a question about equity, a stop on a home-value page, and the selling conversation is already open. Saved searches and a tour request say the buying side is live. Most people do both inside a year, and the automated valuation model, or AVM, holds a partner’s name in front of them across the months in between, which is where the next listing comes from.

Wyoming’s sales volume is steady, and nine other things are moving underneath it

Laramie County closed 1,787 homes a year on average from 2021 through 2025, against 1,479 a year from 2006 through 2010 and 2,061 from 2016 through 2020. The Cheyenne Board of REALTORS® has published that county’s closings every year since 2005, and across those 21 years volume cycles inside a band rather than trending one way. The single-family median moved from $150,000 in 2005 to $199,900 in 2015 to $368,000 in 2025.

Wyoming lost residents to other states in nearly every year from 2014 through 2019, then gained in every year since 2020, at roughly two to three thousand net arrivals against a population near 590,000. Two-thirds of counties gained in 2025, led by Laramie, Sheridan, Natrona, and Lincoln. Campbell, Teton, and Sweetwater each lost more than a hundred. Both directions are business: the people leaving Campbell County own homes that need listing, and the people arriving in Sheridan County need to buy.

Mining employed about 16,000 Wyoming workers in 2024, down from 30,372 in 2008. Total nonfarm employment rose from 301,600 in June 2025 to 304,100 in June 2026, and the Wyoming Department of Workforce Services projects its largest gains in health care and social assistance, accommodation and food services, professional and technical services, and construction. Mining halved across roughly fifteen years and Wyoming kept adding jobs.

Four industrial projects are under construction or federally cleared to start outside Wyoming’s two largest cities. TerraPower began a five-year build of its Natrium plant at Kemmerer in April 2026, peaking near 1,600 workers and settling at about 250 permanent jobs. WE Soda’s Project West near Granger ramps toward roughly 1,300 construction workers through 2026. The Bureau of Land Management cleared the Dry Creek Trona Mine in Sweetwater County, which could carry up to 2,000 workers while it is built. Ramaco broke ground on the Brook Mine north of Sheridan in July 2025, the first new coal mine in Wyoming in more than fifty years.

A fifth build-out is under way in Cheyenne. Microsoft moved in 2026 to buy about 3,200 acres there and committed $68 million to roads, storm sewer, and water upgrades, after paying more than $11 million in local property tax in 2025 as the city’s top taxpayer. Meta’s Project Cosmo adds an $800 million, 715,000 sq ft data center in the same county.

Aerial view of a Wyoming oil refinery with wind turbines on the horizon, part of the industrial construction pipeline driving housing demand across Sweetwater, Carbon, and Lincoln counties
Wyoming’s industrial build-out runs through counties well outside Cheyenne and Casper.

Wyoming visitors spent $5 billion in 2025 and supported about 34,000 jobs. Teton County’s visitor spending rose 44.6% between 2019 and 2025, and Park County’s went from $519 million in 2024 to $538 million in 2025.

The rules deciding what a Wyoming homeowner pays in property tax changed four times between 2024 and 2026. Voters approved a constitutional amendment in November 2024 making residential property its own class. House Bill 45 capped the annual increase in a residential structure’s assessed value at 4%. House Bill 3 exempted half the value for owners 65 and older who have paid Wyoming property tax for 25 years. Senate File 69, signed in March 2025, exempted 25% of the first million dollars of value with no sunset date. Almost every homeowner in the state is touched by at least one of them.

Wyoming’s rental vacancy rate hit 14.7% in 2017, fell to 4.4% by 2023, and rose to 7.1% by 2025. A ten-point swing inside a decade is what the energy cycle does to rentals here, and it has done it before.

One in four Wyoming residents will be 65 or older by 2030. More than half the state’s counties recorded more deaths than births in 2025, and two-thirds of Wyoming houses were built before 1990. That is a large group of long-tenured owners holding equity in aging homes with a decision in front of them.

Median home values exceeded what median-income households could afford in every Wyoming county in 2023, including the cheapest ones, according to Root Policy Research working for the Wyoming Community Development Authority.

Every one of those ten gives some Wyoming household a reason to move. The problem is knowing which household, and when. Before any of that matters, check whether your Wyoming county is still open.

Ten counties hold three-quarters of Wyoming’s population

Laramie County and Natrona County hold about 31% of Wyoming between them, the ten largest counties hold roughly 77%, and the remaining thirteen split the rest across an area larger than most states. A lead strategy built for one Wyoming county rarely transfers to the next.

Three county-seat pairings catch out-of-state agents. Sweetwater County’s seat is Green River, but Rock Springs is the larger city. Fremont County’s seat is Lander, but Riverton is larger. Lincoln County’s seat is Kemmerer, a town of about 2,350, while the Star Valley communities in the north of that county hold more than twice that between them. An agent who gets one of those wrong in a first conversation loses credibility that is hard to earn back in a small market.

In Laramie County, 34,760 residents live outside Cheyenne, Pine Bluffs, Burns, and Albin combined. That unincorporated balance grew 3.9% between 2020 and 2025 while the city of Cheyenne grew 1.7%. A third of the county lives out there, growing at more than twice the city’s rate, with no neighborhood name to farm and no subdivision list to buy.

Cheyenne is adding adults and losing children

Laramie County led Wyoming in 2025 for both population growth and net migration, which is arrivals minus departures. Laramie County School District #1 enrolled 13,426 students in the 2024 to 2025 school year, according to the federal Common Core of Data, and the district’s own October 2025 count came in lower still.

Adults are arriving while school enrollment falls. Those two facts point at remote workers, downsizers, and later-life movers rather than families chasing an elementary school. Those buyers shop different price bands on different timelines, and a listing flyer built around school ratings does not reach them.

Aerial view of a Wyoming residential neighborhood with tree-lined streets and single-family homes set against rolling hills
Two Wyoming counties hold about 31% of the state’s population between them.

Wyoming’s ten most populous counties and their principal cities

County2025 populationPrincipal cityOther named places
Laramie102,938Cheyenne (66,507)Pine Bluffs, Burns, Albin
Natrona80,526Casper (58,771)Mills, Bar Nunn, Evansville, Midwest, Edgerton
Campbell48,145Gillette (34,024)Wright
Sweetwater41,267Rock Springs (22,936)Green River (county seat), Superior, Wamsutter, Granger
Fremont39,464Riverton (10,910)Lander (county seat), Dubois, Shoshoni, Hudson, Pavillion
Albany38,558Laramie (32,284)Rock River
Sheridan33,241Sheridan (20,015)Ranchester, Dayton, Clearmont
Park31,171Cody (10,377)Powell, Meeteetse
Teton23,333Jackson (10,720)Wilson, Teton Village, Moose, Kelly, Moran
Lincoln21,180Kemmerer (2,353, county seat)Afton, Star Valley Ranch, Alpine, Thayne, Diamondville, Cokeville

Population estimates as of July 1, 2025, from the Wyoming Economic Analysis Division and the US Census Bureau. Uinta County, at 20,728 with Evanston as its principal city, is eleventh and just misses the table.

Wyoming runs on investment income more than any other state

Wyoming’s per-capita investment income of $32,658 leads the country and runs more than double the national $15,342. Its overall per-capita personal income of $86,477 in 2024 ranked fourth among the states, behind the District of Columbia, Connecticut, and Massachusetts, and rose 53.7% across the decade from 2014 to 2024. Those figures come from the Bureau of Economic Analysis by way of the Wyoming Economic Analysis Division.

Investment income accounted for 77.2% of all personal income in Teton County in 2024, 42.8% in Park County, 37.2% in Sublette, 36.1% in Lincoln, and 35.9% in Sheridan. Four Wyoming counties outside Jackson Hole draw more than a third of everything residents earn from assets rather than paychecks. Sheridan, Sublette, and Lincoln lead the state in building permits per resident, and Lincoln, Sheridan, and Park lead it in growth outside the city limits.

A wage earner moves when a job moves, and a job move announces itself: a transfer, a promotion, a plant opening, a hiring wave. An owner living on investment income moves when a portfolio, a tax bill, or a stage of life changes. Not one of those three sends a signal anyone outside the household can see, and a lead source priced on search behavior is watching the wrong thing.

Volume is the wrong thing to buy in those counties. You cannot predict the trigger, so you have to already be in front of the household when it fires, which makes this a follow-up problem measured in years rather than a lead-count problem measured in months.

Teton County is the extreme case. It holds about 4% of Wyoming’s population and earned 23% of the state’s total personal income and roughly half of its total investment income in 2023. Its residential property was assessed at $3.5 billion out of $9.8 billion statewide, which puts about 35% of Wyoming’s residential value inside one county. It generated more than half of the state’s 3% lodging tax in fiscal 2024. Per-capita personal income there ran $471,751 in 2023 and $532,903 in 2024, first among more than 3,000 US counties and nearly double second-place Summit County, Utah.

Average is not median. Teton County uses $128,900 as the median income figure for its own property tax rebate program. The households at that end of the range are the ones commuting in from Idaho, and an agent who quotes $532,903 without $128,900 sounds like a tourist.

Wyoming’s six regions need six different lead strategies

The Wyoming Community Development Authority splits the state into Southeast, Central, Northeast, Northwest, Southwest, and Teton for its housing work, and the job of finding business changes at every one of those boundaries.

Southeast (Albany, Goshen, Laramie, Niobrara, Platte) is absorbing the state’s largest corporate build-out. Laramie County led Wyoming in 2025 for both total growth, at 1,251 residents, and net migration, at 1,120. Albany County grew 4.0% since 2020 while its unincorporated balance grew 11.2%.

Central (Carbon, Converse, Natrona) holds the state’s second-largest county market and its steepest population loss at once. Natrona County added 255 residents in 2025 on net migration of 275, enough to cover a year in which deaths outnumbered births. Carbon County fell 0.5%, tied for the steepest drop in Wyoming, and the 622-turbine Chokecherry and Sierra Madre project south of Rawlins moved its completion deadline from 2026 to 2029. That pushes the payoff for Rawlins sellers three more years out.

Northeast (Campbell, Crook, Johnson, Sheridan, Weston) is where Wyoming builds. The city of Sheridan crossed 20,000 residents for the first time in 2025 and Sheridan County has grown 7.5% since 2020. Crook County has grown 9.3%, the fastest in the state, with Pine Haven alone up 17.2% on the Wyoming edge of the Black Hills. Ramaco’s Brook Mine north of Sheridan broke ground in July 2025 and added a pilot processing plant that October.

Northwest (Big Horn, Fremont, Hot Springs, Park, Washakie) grows outside its towns. Park County is up 5.2% since 2020, but the unincorporated balance is up 8.8% while Cody and Powell held flat. Park’s direct travel spending went from $519 million in 2024 to $538 million in 2025. Fremont and Washakie each fell 0.5% in 2025.

Southwest (Lincoln, Sublette, Sweetwater, Uinta) holds the fastest-growing county in Wyoming and the biggest loser, side by side. Lincoln County is up 8.2% since 2020 with its unincorporated balance up 11.8%, and TerraPower’s Kemmerer build began in 2026 toward a peak near 1,600 workers. Sweetwater County lost 2.4% of its population across the same five years while carrying the largest industrial construction pipeline in the state. An agent in Rock Springs and an agent in Afton run different businesses.

Teton is one county and its own region. Its population was flat between 2020 and 2025 and it lost net migrants in 2025 while gaining through births. It hosts more than half of Wyoming’s overnight stays. Its average apartment rent runs about 3.3 times the state average and its average house rent about 2.8 times.

The Grand Teton range reflected in a still Wyoming lake in Teton County, where average rents run roughly three times the statewide average
Teton is one county and its own region in Wyoming’s framework.

Wyoming’s cost-of-living index reports Lincoln County as two areas, Afton and Kemmerer, because the legislature added Afton as a sampling point in 2003. Their housing index numbers differ by about 30%. One Wyoming county can be two markets, and the state says so on paper.

Wyoming’s six regions and what is moving in each

RegionCountiesWhat the data shows
SoutheastAlbany, Goshen, Laramie, Niobrara, PlatteLaramie County led Wyoming in 2025 for both growth (+1,251) and net migration (+1,120). Microsoft moved in 2026 to buy about 3,200 acres near Cheyenne, and Meta is building an $800 million data center.
CentralCarbon, Converse, NatronaNatrona added 255 residents in 2025 on net migration of +275. Carbon fell 0.5% while the 622-turbine Chokecherry and Sierra Madre project moved its completion deadline to 2029.
NortheastCampbell, Crook, Johnson, Sheridan, WestonSheridan city passed 20,000 for the first time in 2025 and Sheridan County has grown 7.5% since 2020. Crook County has grown 9.3%, the fastest in the state.
NorthwestBig Horn, Fremont, Hot Springs, Park, WashakiePark County has grown 5.2% since 2020 with its unincorporated balance up 8.8% while Cody and Powell held flat. Park travel spending rose from $519 million in 2024 to $538 million in 2025.
SouthwestLincoln, Sublette, Sweetwater, UintaLincoln has grown 8.2% since 2020 and TerraPower’s Kemmerer build began in 2026 toward a peak workforce near 1,600. Sweetwater lost 2.4% while carrying the state’s largest construction pipeline.
TetonTetonPopulation flat from 2020 to 2025 with a net migrant loss in 2025. Hosts more than half of Wyoming’s overnight stays. Average rents run roughly three times the state average.

Regional framework from the Wyoming Community Development Authority. Population and migration figures from the Wyoming Economic Analysis Division and the US Census Bureau. Travel spending from the Wyoming Office of Tourism. Rents from the Wyoming Rental Vacancy Survey, fourth quarter 2025.

Wyoming housing costs have outrun national inflation for seven straight years

Wyoming housing inflation ran 2.7% against a US consumer price index of 2.3% in 2019, 7.4% against 7.0% in 2021, 8.3% against 6.5% in 2022, 5.6% against 2.9% in 2024, and 5.2% against 2.7% in 2025. Housing carries a 49.4% weight in the Wyoming Cost of Living Index, which makes that gap close to a statement about the state’s whole cost structure. Rents moved with it. Between the fourth quarters of 2024 and 2025, apartments rose 4.1% statewide, houses 4.8%, and mobile home lots 5.7%.

The same index prices 28 Wyoming cities and towns twice a year and publishes a housing number for all 23 counties against a statewide average of 100. Teton comes in at 238. Lincoln-Afton is 118 and Laramie County 112. Sublette at 101, Albany at 100, Campbell at 98, and Sheridan at 97 sit within a few points of the average. Natrona at 94, Lincoln-Kemmerer at 91, Park at 90, and Fremont at 89 fall below it. At the bottom are Goshen and Niobrara at 70, Hot Springs at 72, and Big Horn, Washakie, and Weston at 74.

The same marketing dollar buys three times the housing in Torrington that it buys in Jackson. A lead that pays for itself in Wilson may not pay for itself in Lusk, and an agent spending uniformly across a Wyoming county line is overpaying on one side of it.

A trolley on a downtown Cheyenne street in Laramie County Wyoming, where the housing cost index runs above the statewide average
Laramie County’s housing cost index sits at 112 against a statewide average of 100.

Wyoming homeowners have watched a housing cost line climb faster than the national average seven years running, and almost none of them have seen the comparison written down where they can check it. That is a reason to call a homeowner who is not shopping.

Wyoming’s homebuilding moved counties over the past two decades

Compare average annual residential permits in the 2006 to 2015 decade against 2016 to 2025, from the US Census Bureau building permit survey as the Wyoming Economic Analysis Division publishes it. Statewide, permits fell 19%. Lincoln County nearly doubled, up 99%. Laramie rose 54%, Platte 43%, Sheridan 37%, and Park 15%. Natrona fell 52%, Sweetwater 74%, Converse 81%, Goshen 83%, and Weston 88%.

The state total went down. Five counties went up.

Wyoming averaged 2,353 permitted units a year across 2021 to 2025, above the 1,860 average of 2016 to 2020 and the 2,073 of 2011 to 2015. The 2023 figure of 1,681 units, the one quoted in housing testimony, was the bottom of a cycle.

Sheridan County averaged 331 units a year across 2021 to 2025 against 185 a year across the whole 2006 to 2015 decade, a 79% increase. In 2025 it authorized more residential units than Natrona County on 41% of Natrona’s population. Per 1,000 residents in 2025, Sheridan permitted 12.7 units, Sublette 11.5, and Lincoln 11.4, against a Wyoming rate of 3.8 and a Fremont County rate of 0.5.

Sheridan, Sublette, and Lincoln also sit among the five counties where investment income tops a third of what residents earn. The building and the money are in the same counties, and neither is in Cheyenne or Casper.

New construction is three lead sources at once. Someone building a new house usually has an old one to sell, a new subdivision needs buyers to fill it, and permits move before people do. All three concentrate in counties where almost nobody runs a serious lead engine.

Kemmerer is the clearest live example. Average apartment rent in the Kemmerer reporting area rose faster between the fourth quarters of 2024 and 2025 than in any other Wyoming reporting area, and house rent rose at a similar pace, while the Afton end of the same county moved about a point. A developer has reported plans there for a 116-acre subdivision of about 275 homes plus a 240-unit apartment project.

Kemmerer’s mayor has said he does not want the town past 5,000 to 6,000 residents, against a town population near 2,400, and he puts the constraint on municipal sewer and water capacity rather than builder appetite: the will-serve letters the city has issued, its written promises to supply water and sewer to a given project, already account for the capacity it has. A five-year construction cycle running to 2030 into a town with a hard infrastructure ceiling produces different business from an open-ended boom, and a relocating engineer will hear that explanation from one agent in the county at most.

At the 2010 Census, 42.6% of Wyoming’s vacant homes were held for seasonal, recreational, or occasional use, reaching 77.6% in Sublette County, 73.8% in Teton, and 61.4% in Crook. A second-home owner is a non-resident with equity, a mailing address in another state, and no local agent by default. In three Wyoming counties that describes most of the vacant stock, and nobody is farming it.

None of that appears in a listing count, and each of those counties seats exactly one partner. Ask whether yours is still open.

Ten Wyoming counties beyond the big metros

County2025 populationCommunitiesWhat the data shows
Crook7,852Sundance, Moorcroft, Pine Haven, HulettFastest-growing county in Wyoming since 2020 at 9.3%. Pine Haven is up 17.2%.
Johnson8,908Buffalo, KayceeBuffalo grew 6.9% since 2020, and 3,890 residents live outside both towns.
Big Horn12,024Basin, Greybull, Lovell, CowleyBurlington grew 25.2% since 2020, the fastest percentage gain of any Wyoming town.
Converse13,824Douglas, Glenrock, Rolling HillsCounty population rose 0.2% in 2025 while permits fell 81% decade over decade.
Goshen12,640Torrington, Lingle, LaGrange, Fort LaramieMore than 25% of residents are 65 or older, and the county ties Niobrara for the lowest housing cost index in the state at 70.
Platte8,634Wheatland, Guernsey, Glendo, ChugwaterGrew 0.8% in 2025 after four years of decline. Permits rose 43% decade over decade.
Uinta20,728Evanston, Lyman, Mountain View, Bear RiverThe unincorporated balance is up 6.0% since 2020, and Lyman grew 1.0% in 2025.
Carbon14,013Rawlins, Saratoga, Hanna, EncampmentSaratoga grew 4.3% since 2020 while Rawlins fell 6.3%.
Sublette8,929Pinedale, Marbleton, Big Piney, BondurantHousing units rose 7.0% since 2020 while population slipped, and the county permitted 11.5 units per 1,000 residents in 2025.
Weston6,840Newcastle, UptonMore than 25% of residents are 65 or older, and permits fell 88% decade over decade.

Population from the Wyoming Economic Analysis Division and the US Census Bureau, July 1, 2025. Permits from the US Census Bureau Building Permits Survey. Housing cost index from the Wyoming Cost of Living Index, fourth quarter 2025.

The work-from-home shift is why the county lines moved

The Bureau of Labor Statistics telework rate held between 21.5% and 23.0% across the twelve months ending March 2026. The Business Trends and Outlook Survey, which the Census Bureau put to about 150,000 firms, found 31.2% of US businesses where somebody works a full day at home, and the same employers expect no different five years from now. Return-to-office headlines describe a reversal neither dataset shows.

Wyoming’s own work-from-home share went from 5.73% in 2019 to 9.72% in 2024, against a national 5.72% and 13.32%, per the Census Bureau’s American Community Survey. Wyoming roughly doubled off a low base, and the low base is why the effect concentrates. Ten percent of Wyoming’s workers is a small number of households, and they did not spread evenly across 23 counties.

A rustic log cabin on acreage in rural Wyoming, the kind of property drawing remote and hybrid workers into the unincorporated parts of the state
About 31% of Wyoming residents live outside any incorporated town.

The USDA Economic Research Service reports that rural counties nationally gained 974,379 net migrants between 2020 and 2024 while deaths exceeded births by 563,550, and that 65% of nonmetro counties recorded positive net migration across that span.

Wyoming’s state demographer named the local version. Dr. Wenlin Liu of the Economic Analysis Division, in the state’s 2026 population release: “Since the COVID-19 pandemic, less populated and more affordable areas have gained attractiveness. Some professional and business workers with telework capabilities opted to move to rural areas.”

The unincorporated balances of Lincoln, Albany, Sheridan, Park, and Crook counties are where that shows up on the map, along with Star Valley, the Bighorn Basin, and the country around the Powder River Basin. Park County is the cleanest case: its unincorporated balance grew 8.8% since 2020 while Cody and Powell held flat. Lincoln County planning officials reported as of 2023 that roughly 60% of Alpine’s working-age population commuted, about 1,200 people a day, and that about 90% of new homes were going up in unincorporated parts of the county.

What those buyers ask for is consistent: a room with a door that closes and works as an office, a shop or accessory dwelling unit standing apart from the house, more acreage than the last place, and internet service that holds a video call. They shop counties rather than neighborhoods. An agent who opens a rural showing by explaining what the line on that road can carry is answering the question the buyer drove out there to ask.

Six lead sources Wyoming agents run, and the wall each one hits

Every one of the six carries real business somewhere in Wyoming, and every one of them stops at a boundary this state draws.

Shared leads from legacy real estate portals arrive fast and in volume, and for a newer agent they are a real way to get at-bats. Sold to four agents in a market that closes tens of thousands of homes a year, a shared lead is a percentage play. Sold to four agents in Laramie County, which averaged 1,787 closings a year across 2021 to 2025 and is the largest county market in the state, it is four people calling one person inside the hour, and whoever bought it owns nothing afterward.

An IDX website of your own is the right instinct, and the asset is yours. Search traffic to a single-agent site in a county of 20,000 takes years to build, competes with national domains for the same terms, and needs paid traffic in the meantime. The site is fine. The audience it needs is the hard part.

Cold calling, circle prospecting, and farming built most of the successful books in this state and still work where the doors are close together. About a third of Wyoming’s population lives outside any incorporated town, and Lincoln County planning officials put roughly 90% of that county’s new home construction in unincorporated areas as of 2023. Sweetwater County alone is larger than nine states. A farm route assumes a density Wyoming does not have.

Predictive seller tools score a database and rank who might sell, and the ranking is often useful. The output is a name with a probability attached to it. A probability becomes a listing only through a relationship the agent has to build anyway, which is the work the tool was sold to take off their plate.

All-in-one platforms and best-of-breed stacks both hand the work back. An all-in-one leaves you configuring it. A stack leaves you maintaining every piece of it every week. Neither gives you the data behind a home valuation or an audience that arrives on its own.

Do-it-yourself content and paid advertising both work. Both are a second job.

Response time got less forgiving underneath all of them. Laramie County single-family days on market averaged about 85 across 2005 to 2009 and about 28 across 2020 to 2025. The window between someone becoming a buyer and becoming another agent’s client shrank by roughly two-thirds in twenty years, and it will not widen again. Any name that reaches you a day late is worth nothing by the time it arrives.

Rural residential has been about one closing in five in Laramie County for two decades. The share held steady. The price gap is what moved, which makes it a pricing shift rather than a new market.

ez Home Search watches what people do on a platform they already trust and surfaces the contact while the interest is live: a search picked back up after eight months, a second run at the home valuation, a saved listing opened again, an alert read the morning it landed. The agent calls the person whose own activity says they are close, already knowing the searches they ran and the price they kept landing on.

Most of those connections take 30 to 60 days to become a transaction. The partnership runs on one flat fee rather than a charge per lead, so a month of heavy activity does not come back as a heavier invoice, and the engine works the database a partner already owns before it touches anyone new.

The Exclusive County Partnership puts one Wyoming county in one agent’s hands

A Wyoming county goes to one agent, one team, or one brokerage and to nobody else inside those county lines, with their brand across the consumer experience. The fee is flat. No charge attaches to a lead and no percentage comes off a closing, so a busy month costs the same as a slow one.

People come to ez Home Search and stay because their contact details and budget are never resold, recycled, or pushed out to a long list of unknown businesses. What they get instead is a single expert, vetted and local, picked for the ground that expert knows and for what the person needs. The Only Confidential Home Search is what ez Home Search calls that, and delivering it is how the company makes A Better Way To Discover Real Estate real for the person searching. For the partner it means the first call is not a cold one. The person arrives with a legible history behind them: the neighborhoods they came back to, the price they kept landing on, the tour they finally asked for.

Buyers rate their agents well: 88% to 92% say they would hire the same one again or recommend them. Only about 18% go back to an agent they have already worked with. The whole distance between those two numbers is business earned once and then handed to someone else. Repeat and referral business is roughly 41% of what an agent closes industry-wide, and the majority of what the longest-tenured ones close. ez Home Search partners bring past clients back, as repeat business or as referrals, at a rate 2.5 to 5 times what the market produces.

Wyoming’s homeownership rate has topped the national rate every year since 2000. Two-thirds of its housing stock predates 1990. Its births decline thins the first-time-buyer pipeline into the 2030s, and its buyer base leans on income from assets, which puts the timing signal in equity and taxes instead of a job offer. Those four facts make the database the business here, and ez Home Search runs the follow-up that keeps it producing, co-branded to the partner, at a quality and cost no single team reaches alone.

A database also erodes on its own. Dead email addresses run 15% to 22% of a list in a year, and phone numbers turn over at close to one in ten. The people in a partner’s database keep opening the listing alerts, the home value updates, and the co-branded search itself, so ez Home Search picks up the new address and the new number as they change rather than flagging the old ones after a send fails.

The Census Bureau counts roughly 2.1% of Americans changing states in a year, plus about another 3% who cross a county line without leaving home. Wyoming borders six states. Teton County’s workforce commutes from Idaho, and Lincoln County planning officials put roughly 60% of Alpine’s working-age population in a daily commute as of 2023. When a past client starts looking across one of those lines, the agent usually never sees it, the client connects with a stranger attached to a listing over there, and the home on this side gets listed by whoever that stranger hands them to. Nationwide coverage is what changes the agent’s line of sight. The client searches the new market on the partner’s own co-branded platform, the activity surfaces as an early signal, and the agent takes the listing on the home being left while referring the purchase.

In the National Association of REALTORS® buyer and seller profile, 81% of sellers talk to one agent and never open a second conversation, 77% of repeat buyers sit down with exactly one, and reputation outranks every other consideration for 35% of sellers. In a Wyoming county of 8,000 people, the recognized name is the whole competition, and one partner holds it at a time.

ezVerify.ai establishes the opt-in and keeps the recording behind it, screens each number for known litigators, and clears Do Not Call registrations before a single dial. It also fills in detail on the contact that an agent would otherwise spend an afternoon running down. A dispute over consent then meets documentation.

The rest runs without the partner building or operating any of it: the search experience, the home valuations, the market reports, the listing alerts, and the automated follow-up that ezNurture handles inside Follow Up Boss and Sure Send™ carries natively. Weekly coaching, sales enablement, and events sit on top of that, because the partnership only pays for ez Home Search when it pays for the partner.

One partner per county, and Wyoming has 23

Wyoming has 23 counties and the Exclusive County Partnership seats one partner in each. Many are already held. More go every month, and the ones that go first tend to be the counties adding permits and people faster than their own county seats.

The partner’s name is what county residents see on the search experience they already use, on the home value updates, and on the local market reports. While the partner holds the county, no rival can occupy that same co-branded position at any price, because the position exists once per county.

It works on day one, with no configuration and no administration on the partner’s side. A partner walks onto a platform that millions of people already use and finds their own name on it, instead of spending three months standing up an all-in-one system or losing every Tuesday to keeping a stack of tools alive.

A county of 8,000 residents with one recognized name is a different business from a metro with a thousand agents competing for the same searches. Exclusivity is worth more where there is less to divide.

Three ways to work a Wyoming county

Keep buying shared leads and farming the incorporated part of the county. That reaches roughly two-thirds of the population, the slower-growing and less expensive two-thirds, and it is the part every competitor is already working. The tactics are proven and the ceiling is low.

Build the whole thing yourself. The whole thing means a consumer search people return to unprompted, a valuation model accurate enough to trust, listing data that refreshes by the minute, an alert engine, a content operation producing something worth opening every month, a compliance layer that can prove consent on every number you dial, and enough national traffic to feed all of it. That is a technology and data budget in the millions, and the data sourcing alone sits past what any single team or brokerage in Wyoming can buy. Agents try anyway, one piece at a time, and end up administering six tools instead of talking to clients.

Take one county on a platform that already operates every one of those pieces, put your name on it, and pay a single flat fee.

A county partnership pays off slowly. Most connections take 30 to 60 days to become a transaction, reactivation compounds over quarters rather than weeks, and the county has to be open when you ask, which nobody can promise. That is the price of a position no competitor can copy from outside, whatever they spend.

Weigh all of it against one number. An ez Home Search partner sees past clients come back, whether they buy again or send someone, 2.5 to 5 times as often as an unaided market delivers. In a state where the homeownership rate has run above the national rate every year since 2000 and two-thirds of the houses were built before 1990, that is the number that matters.

Find out whether your Wyoming county is still open.

Frequently asked questions

Most of Wyoming’s growth is happening outside the city limits. How do I generate leads there?

That will not come from farming. The unincorporated parts of Lincoln, Albany, Sheridan, Park, and Crook counties all grew faster than their towns between 2020 and 2025, and none of them offer a subdivision name to target or an owners roster to buy.

Someone looking at forty acres outside Buffalo searches by county, price, and acreage rather than by neighborhood, and usually does it for months before speaking to anyone. County exclusivity puts a partner’s name on that search across the whole county instead of one subdivision at a time.

Laramie County averages under 2,000 closings a year. How many leads does a Cheyenne team need to grow?

Fewer than a vendor will try to sell you. Laramie County averaged 1,787 closings a year across 2021 to 2025, spread across every price band and every brokerage in the county. A team chasing 3% of that is chasing about 54 transactions in a year.

Conversion rate and relationship depth decide that number rather than volume. An ez Home Search partner reactivates a past client at 2.5 to 5 times the market’s rate, and a client who comes back costs nothing to acquire.

Will the construction workforce at Kemmerer and the Sweetwater trona projects turn into buyers, or only renters?

These projects produce both, in that order. A five-year build brings workers who rent first, which is why rents in the Kemmerer reporting area rose faster than anywhere else in Wyoming between the fourth quarters of 2024 and 2025. The permanent jobs are where the buyers are: about 250 at TerraPower’s Kemmerer plant, and roughly 300 each at Dry Creek and Project West once those two are running. Both mine trona, the mineral soda ash is made from.

Kemmerer’s mayor has said he does not want the town past 5,000 to 6,000 residents, and municipal sewer and water capacity sets the pace. Part of that permanent workforce will buy in Evanston, Rock Springs, or Star Valley instead, which is a lead-generation question as much as a housing one.

My past client is priced out of Teton County and looking at Star Valley or across the line in Idaho. How do I keep the listing on this side?

You see the move before the home becomes a listing. Teton County lost net migrants in 2025 while its average house rent ran about 2.8 times the Wyoming average, and the households leaving move south through the Snake River Canyon into Star Valley or west into Idaho. Roughly 60% of Alpine’s working-age population was already commuting as of 2023.
The listing at risk is the home they are leaving, and it gets lost when the agent finds out late. A past client searching a new market on their agent’s own co-branded platform turns that search into an early signal instead of a silence. You call before the home is in play, take the listing on this side, and refer the purchase for a fee.

Wyoming changed its homeowner property tax rules four times between 2024 and 2026. How do I use that to open seller conversations?

Give people a number they can check. Wyoming assesses residential property at 9.5% of fair market value, and total residential mill levies run between 65 and 80 mills depending on the tax district, a mill being one dollar of tax per thousand dollars of assessed value. On a $400,000 home at 70 mills, that is $38,000 of assessed value and roughly $2,660 a year, and the 25% exemption on the first million dollars of value takes about $665 off it. Treat that as an illustration, because the mill levy in a specific district decides the figure a homeowner actually pays.

Most Wyoming homeowners know their bill changed and cannot say why. The conversation covers the 4% cap on annual assessed-value increases, the 25% exemption, and the long-term exemption for owners 65 and older who have paid Wyoming property tax for 25 years, and it ends where every seller conversation ends, at what the home is worth.

A lot of my county’s income is investment income rather than wages. Does that change how I should prospect?

It changes what you are waiting for. Investment income accounted for 42.8% of personal income in Park County in 2024, 37.2% in Sublette, 36.1% in Lincoln, and 35.9% in Sheridan. A wage earner moves when a job moves, and that is visible in advance. An owner living on assets moves when a portfolio, a tax position, or a stage of life changes, and none of that shows from outside.

Presence replaces pursuit. You cannot predict the trigger, so you have to be there when it fires: home value updates, local market reports, and a search experience the person returns to on their own across years.

How does county exclusivity work in a Wyoming county with 8,000 people?

The structure is identical to Laramie County and the economics are arguably better. One partner holds the county with their brand on the consumer experience, for a flat fee that carries no per-lead charge and takes no share of a commission.

In a small county the recognized name is close to the entire competition. In the same National Association of REALTORS® profile, 81% of sellers approach one agent only, and 35% put reputation ahead of every other consideration. A county of 8,000 people has room for exactly one.

08.15.2026

Vermont Real Estate Leads: Find the Owners Who Sell Next

Vermont’s population slipped in 2024 and again in 2025, and the number of Vermont households rose in both of those same years. The Legislature’s nonpartisan Joint Fiscal Office stated it flatly in May 2026: population down, households up. That gap is the most useful fact available to anyone working Vermont real estate leads, because a household is what signs a listing agreement. A person is not.

The arithmetic behind the population headline is mostly about age. Across the year ending July 2025 the state recorded 4,979 births against 6,748 deaths. Net migration over the same stretch came out 103 people short, with 623 arrivals from other countries set against a net loss of 726 to other states. Widen the window and the direction reverses. From April 2020 through July 2025 Vermont added 1,568 residents, because net migration of 10,279 more than covered a natural decline of 8,669.

The line worth building a business on sits underneath the headline. Vermont holds roughly 193,000 owner households, and about three in every hundred of them sell in any given year. Those owners are the market. Even in the slowest recent year they produced 5,759 sales, which dwarfs anything migration did in either direction.

Ten trends shaping the Vermont housing market

Roadside sign reading Welcome to Vermont, The Green Mountain State, beside a two-lane road with autumn foliage and houses
Vermont’s market is smaller than most states and steadier than the headlines suggest.

Vermont’s market is steady, and the ten forces below are what move it.

Sales volume fluctuates; it does not fall. Primary home sales cleared 8,000 in each of 2019, 2020, and 2021, slid to 5,759 in 2023, the lowest annual total since 2012, then rose about 9% in 2024 and rose again through 2025. The source is Property Transfer Tax records, which capture every residential title transfer recorded in Vermont, so that series is a census of sales rather than a survey.

Prices climbed straight through the sales trough. The statewide median primary home went from $309,000 in 2022 to $325,000 in 2023, roughly $353,000 in 2024, and roughly $370,000 by mid-2025. Apart from a slight dip in Lamoille County, no Vermont county posted an annual median decline between 2019 and 2023.

Inventory loosened without volume falling. Those are two different measurements, and treating them as one is the most common error in market commentary. Listings ran more than 8% above the prior year through August 2025, and months of supply sat near 2.6 against a balanced level of four to six. Stock on the market is a snapshot. Sales are a flow.

Migration is small in both directions. Net migration swung from a loss of 1,458 in 2016 to a gain of 5,250 in 2021 and back to a loss of 726 to other states by 2025. Set against 273,000 households, a few hundred people is a rounding error. Departures are listings and relocation referrals. Arrivals are buyers.

Employment spreads across sectors rather than one anchor. Health care and social assistance added about 500 jobs in 2025 and remains the largest and fastest-growing sector, driven by the age profile below. Manufacturing contributes roughly $3B to state GDP at an average wage of $71,831, about 11.4% above the statewide average for all jobs. Professional and technical services and tourism round out the Department of Labor’s leading growth sectors.

A lot of Vermont buyers work for themselves. Census figures counted 65,028 nonemployer establishments in Vermont in 2023, meaning businesses with an owner and no payroll, against 20,841 that do employ someone. About three in four Vermont businesses have no employees. Statewide that works out to one owner-run business for every four households. That is a large slice of your buyer pool. Those owners prove income with tax returns and profit-and-loss statements rather than pay stubs, so the financing conversation with them has to start earlier than it does with a salaried buyer.

The owner base is old and getting older. Residents 65 and over make up 24.1% of Vermont, and the median age of 43.2 ranks third oldest in the country. Of the 16,000 to 17,000 new owner households the Vermont Housing Finance Agency projects through 2029, more than 12,000 will be headed by someone past 65.

Households keep shrinking while the homes do not. Every net household added between 2010 and 2022 was a one or two person household, and the count of larger households fell over the same stretch. Yet 68% of Vermont owner households hold one or two people while only 26% of the homes here have two bedrooms or fewer.

The stock is old and new construction is expensive. More than a quarter of Vermont homes predate 1940, against 12% nationally, and the median new home price rose from $365,569 in 2019 to $616,500 in 2023.

Land-use law is being rewritten around housing. Act 47 of 2023 raised the Act 250 review threshold from 10 to 25 units in downtowns and village centers and barred local bans on multi-family housing, accessory dwellings, and parking minimums in those areas. Act 181 of 2024 replaced Act 250’s size-based triggers with location-based tiers on a five-year schedule.

One more thing is worth knowing before you plan against any of it. Vermont is the only state in the country without regular official population projections, a gap the Census Bureau’s own listing of state projection programs confirms. The number people quote loudest is the one Vermont measures least.

Most Vermont buyers are also sellers, and most of them start as buyers

About four buyers in five are carrying a house they intend to sell in order to fund the next one, so an agent running a listing campaign and a buyer-lead campaign is often running one campaign twice. Most agents work a single side anyway. They market “list with me” to owners, or they buy cold buyer names, and one move gets split into two campaigns aimed at two imagined customers.

The national numbers show how large that miss is. The National Association of Realtors runs a Profile of Home Buyers and Sellers each year, and the 2025 edition put the first-time buyer share at 21%, the lowest reading since the survey began in 1981. Repeat buyers made up the other 79%. That first-time buyer was 40 years old at the median, an all-time high in the series, against 62 for the typical repeat buyer, and 30% of all buyers paid cash.

Vermont has no clean state-level first-time-buyer series, and saying so is better than inventing one. What Vermont does have points the same way, harder. Nearly 73% of Vermont households own their home, the third highest rate in the country against roughly 65% nationally. The share of Vermont homeowners carrying a mortgage eased from 63% in 2017 to 61% in 2022, consistent with older owners retiring loans and with cash purchases. Younger buyers are gaining ground rather than disappearing: homeownership among Vermonters aged 25 to 34 reached 48.9% in 2022, up 7% over the 2017 estimate and the highest that age group had recorded since 2007.

Put those together and the Vermont buyer sitting across from you is usually holding a house.

That changes what counts as a lead. Someone who runs a home valuation, returns to a home-value page, or asks what their equity would cover has opened the seller conversation, whatever they typed into a search bar first. Someone whose saved searches wake up and who books a tour has opened the buyer side. Most people do both, in sequence, across months or years. ez Home Search reads that activity and serves whichever side is live, and the automated valuation model (AVM) keeps an owner coming back to check their number long before they are ready to list, so the buyer you help now becomes the listing you earn later.

The arithmetic underneath is patient rather than thin. About three in every hundred Vermont owner households sell in a given year. The other ninety-seven are standing in front of a decision they have not made yet, and the whole job is to be there before they make it.

Anyone who wants to build on that base has one question to settle first: whether their Vermont county is still open.

Roughly one in six Vermont homes belongs to someone who lives somewhere else

Vermont ski resort at the base of snow-covered mountains with ski runs, lifts, and wooden lodge buildings
Resort towns like Stowe, Killington, and Ludlow hold Vermont’s densest concentration of seasonal owners.

Seasonal, occasional-use, and vacation homes account for between 15% and 17% of Vermont’s housing stock depending on the Census vintage, which works out to roughly 50,000 homes and the second highest share of any state. Maine ranks first and New Hampshire third, and Vermont has sat inside the national top three since the Census Bureau started counting in 1940. Vermont’s own share has held high across that span: 9% in 1950, 15% in 1980, 17% in 1990, and roughly 15% in the most recent estimates.

That one fact explains a recurring data problem. Three quarters of every Vermont home the Census Bureau files as “vacant” is one of these, which is why national rankings occasionally announce that Vermont leads the country in empty houses. Those houses are not empty. They belong to somebody who sleeps elsewhere most of the year.

Two official sources count them and the counts disagree by design. The Census Bureau classifies a home by how its occupants use it. Vermont’s property Grand List classifies by the building’s physical characteristics, things like whether it has insulation or a heat source, so a comfortable year-round second home is not a “seasonal property” on the Grand List at all. Neither count is wrong. They answer different questions, and an agent quoting one at a listing appointment should know which one they are holding.

The geography is lopsided. Seasonal homes make up 38% of the housing stock in Essex County and 37% in Grand Isle County, the two highest shares in Vermont, against 3% in Chittenden County, the lowest. At the town level the concentration sits where you would guess. Stowe, Killington, Ludlow, West Dover, and Warren lead Vermont both for seasonal homes and for short-term rental listings. The Vermont Housing Finance Agency’s analysis put roughly 2.5% of all Vermont homes as listed short-term rentals at some point in an average month before 2020, with about 1.4% listed consistently. That level dipped and has since returned.

The consequence for lead generation is uncomfortable. A meaningful share of the Vermont listing pool belongs to a person you cannot door-knock, cannot farm, cannot meet at an open house, and cannot reach with a postcard drop, because they are in another state for most of the year. They still sell eventually. They sell to somebody. The agent who wins that listing is the one whose name stayed in front of them the entire time they were away.

How Vermont’s six regions diverge, and what that changes about your marketing

Aerial view of a small Vermont town with church steeples and houses surrounded by autumn foliage and wooded hills
Six regions, 14 counties, and a price range that runs better than two to one from end to end.

The costliest Vermont county has run about two and a half times the cheapest one in both of the recent years the county comparison covers, which is why a single marketing message cannot serve the whole map. In 2023 the median primary home sold for $185,000 in Essex County and $460,500 in Chittenden County. In 2024 that same pair read $200,000 and $500,000. The levels move. The ratio barely does.

The rest of the 2023 spread, from Property Transfer Tax records, fills in between those two poles: Lamoille at $390,000, Addison at $350,000, Washington at $325,000, Grand Isle at $320,500, Bennington and Windsor at $310,000 each, Windham at $299,000, Franklin at $282,000, Rutland at $275,000, Orleans at $240,000, Orange at $232,284, and Caledonia at $225,000. Only three Vermont counties, Caledonia, Orleans, and Essex, sat inside the affordable band on the Vermont Housing Finance Agency’s home-price-to-income ratio in 2022, a measure that sets a county’s median home price against its median household income.

RegionCountiesWhat the data shows
Greater BurlingtonChittendenVermont’s highest prices and its lowest seasonal-home share at 3%. Holds 31% of the state’s rental stock, and 36% of its own homes are rentals, both the highest in Vermont.
Northwest Vermont and the Champlain IslandsFranklin, Grand IsleFranklin is the affordable commuter alternative to Chittenden, with a single-family median near $400,000 in 2025 on rising unit sales. Grand Isle carries the second-highest seasonal-home share at 37%.
Addison County and the middle Champlain ValleyAddisonA $350,000 median primary home in 2023, with Middlebury anchoring year-round demand and Vergennes, one of Vermont’s 10 incorporated cities, serving as a second center.
Central Vermont and the resort corridorWashington, Lamoille, OrangeLamoille held Vermont’s second-highest county median in 2023 at $390,000, lifted by Stowe. Washington County single-family sales rose 16% in 2025. Orange County stayed among the most affordable at $232,284.
The Northeast KingdomCaledonia, Orleans, EssexVermont’s most affordable region, and the only one where every county sat inside the affordable price-to-income range in 2022. Essex also carries Vermont’s highest seasonal-home share at 38%.
Southern Vermont and the Upper ValleyRutland, Windsor, Windham, BenningtonMost of Vermont’s roughly 50,000 seasonal homes sit in these four counties. Medians in 2023 ran from $275,000 in Rutland to $310,000 in Windsor and Bennington.

County single-family figures for 2025 come from Vermont MLS reporting; the median primary-home figures come from Property Transfer Tax records published by the Vermont Housing Finance Agency. The two measure different things, which is why they do not match.

Chittenden County earns its own note, because it behaves unlike the rest of Vermont. Apartment construction there reached 824 units in 2024, more than twice the annual pace of any year in the prior two decades, and roughly 570 more units finished in 2025 with about 550 projected for 2026. Rental vacancy moved from under 1%, where it sat for more than a year beginning in December 2021, up to about 3% by June 2025. That matters to a buyer’s agent. Renters who are no longer scrambling for a unit are renters with room to plan a purchase.

Every Vermont county, and the towns where the transactions happen

Aerial view of Newport, Vermont, showing tree-lined streets, a marina with boats, and buildings beside the lake
Newport City, the shire town of Orleans County and one of Vermont’s 10 incorporated cities.

Almost all Vermont business gets written in towns and villages rather than cities. The state has 14 counties and only 10 incorporated cities, because a Vermont municipality becomes a city by petitioning the Legislature rather than by crossing a population threshold. That makes town-level knowledge most of the job here, in a way it never is somewhere with three big cities and a ring of suburbs. County seats are called shire towns, and Bennington County is the only one with two of them, Manchester in the north and Bennington in the south.

CountyPopulationShire townPrincipal centers
Chittenden169,758BurlingtonBurlington, South Burlington, Essex Junction, Colchester
Rutland60,425RutlandRutland City, Killington, Castleton
Washington60,017MontpelierMontpelier, Barre City, Waterbury
Windsor57,990WoodstockWhite River Junction, Springfield, Woodstock
Franklin50,638St. AlbansSt. Albans City, Swanton, Georgia
Windham45,923NewfaneBrattleboro, Wilmington, Bellows Falls
Addison37,664MiddleburyMiddlebury, Vergennes, Bristol
Bennington37,269Bennington and ManchesterBennington, Manchester, Arlington
Caledonia30,475St. JohnsburySt. Johnsbury, Lyndon
Orange29,761ChelseaRandolph, Williamstown, Bradford

Populations are Census American Community Survey 2024 five-year estimates. Chittenden County alone holds more than a quarter of everyone in Vermont.

Two of those rows carry a detail worth keeping straight at a listing appointment. Orange County’s shire town is Chelsea, but its largest town is Randolph, at roughly 5,012 people. Montpelier, the shire town of Washington County, is the smallest state capital in the country.

Outside the Burlington area, the towns below are where a great deal of Vermont business gets written.

CountyCommunities
RutlandBrandon, Fair Haven, Poultney, West Rutland
WashingtonNorthfield, Waitsfield, Warren, Moretown
WindsorLudlow, Norwich, Chester, Hartland
FranklinFairfax, Enosburg Falls, Richford, Highgate
WindhamPutney, Dover, Londonderry, Dummerston
AddisonFerrisburgh, Starksboro, Leicester, Weybridge
BenningtonDorset, Pownal, Winhall
CaledoniaDanville, Hardwick, Barnet
OrleansNewport City, Derby, Barton, Craftsbury
LamoilleStowe, Morrisville, Hyde Park, Johnson

That leaves the two smallest counties, and neither should be written off. Grand Isle County, at 7,450 people across North Hero, South Hero, Grand Isle, Alburgh, and Isle La Motte, sits on Lake Champlain inside a commutable distance of Burlington, and 37% of its homes belong to someone using them seasonally. Essex County, at 5,982, runs from Guildhall, a shire town of roughly 257 people, out to Lunenburg, its largest town at about 1,273, plus Concord, Canaan, and Brighton. Essex is the most affordable county in Vermont and the one with the highest seasonal-home share. Small counties are still whole counties, and in this model a whole county is the unit.

Vermont ranks seventh in the nation for working from home

Vermont’s work-from-home share reached 15.96% in 2024, up from 7.04% in 2019, which places it seventh among all states and the District of Columbia, ahead of Virginia, Utah, Maryland, and Massachusetts. Both figures are Census Bureau numbers, from the American Community Survey one-year estimates, table B08006. For the second least populous state in the country, that is an unusual position to hold, and most agents working here have no idea they hold it.

It is also the trend everyone has been told is finished. The federal evidence says otherwise.

In 2026 the Bureau of Labor Statistics published a study built on the National Longitudinal Survey of Youth 1979, tracking one cohort through four decades of working life, the longest continuous look at remote work any federal agency has put out. The finding that matters here: workers reporting no telework, or only a minimal amount of it, never came back to their pre-pandemic share of the workforce, which BLS read as a structural move toward broader telework. Separately, the Census Bureau’s Business Trends and Outlook Survey put the question to roughly 150,000 firms, and those employers put their five-year forecast for remote work at roughly the level they were already running.

For a Vermont agent the useful question skips past whether remote work holds and lands on which parts of the state are positioned to take the demand.

The answer follows the fiber. Communications Union Districts, which are governed by their member towns, have been building it where private carriers did not. Otter Creek’s completed build reached 3,626 locations in the Rutland County region, 1,278 of which were addresses with no service at all. DVFiber reached nearly 5,000 locations in southeastern Vermont, 4,290 of them previously unserved or underserved, with roughly 60 more miles running through West Brattleboro, Dummerston, Marlboro, Newfane, and Guilford targeted for completion in August 2026. Federal approval released $93 million of Vermont’s roughly $229 million broadband allocation to keep that work moving.

Statewide, 89.7% of Vermont households hold a broadband subscription and 43.8% of adults 25 and over hold a bachelor’s degree or higher. That combination, in the Northeast Kingdom or Rutland County or the Windham County towns named above, is what a remote buyer needs in place before a purchase is even thinkable.

It changes what they ask you for, too. They want a workroom with a door on it, or an outbuilding or accessory dwelling unit set apart from the main house, and more square footage than a commute-radius budget used to allow, on a connection that carries a video call through a Tuesday afternoon. A listing presentation that speaks to none of that is selling the house the way houses sold in 2015.

If you would rather have that demand pointed at you than at whoever happens to rank for the town name, it is worth finding out whether your county is still open.

The seven ways Vermont agents fill a pipeline, and where each one stops

Vermont’s lead-generation problem starts with a ratio. The Vermont Association of Realtors serves more than 2,000 members, and statewide primary-home sales have run from roughly 5,800 in the slowest recent year to above 8,000 in the busiest, across the past decade. Divide one into the other. There is no version of that arithmetic in which an agent here can afford to lose a past client, and no version in which raw volume covers a weak conversion rate.

Every approach below works. Each one also has a point where it stops.

Shared leads from legacy portals deliver volume immediately, with nothing to build. They also deliver the same person to several agents at once, cold and unverified, priced either per lead or as a slice of the commission if a deal ever closes. You are paying for an introduction and racing three other people to it.

An IDX website you build and run yourself produces something you own, which matters more than most agents credit. It is also slow to rank, and the data underneath it is the part a single team cannot buy. Accurate valuations, school-level detail, and property-tax comparison across 14 counties sit at the infrastructure layer, well below anything a website theme can add.

Cold calling and circle prospecting still work on the resident owner who picks up. They do nothing whatsoever about the absentee owners described earlier, who hold a large share of Vermont’s listing pool. They also carry consent exposure, which the next section covers.

Predictive seller scoring tells you that a name has a high probability of selling. It does not hand you a relationship with that name, and the agent who already has one will get the listing regardless of what the model said.

All-in-one CRMs promise the entire stack in a single login. What arrives is a configuration project, an administration burden, and a system that stays only as good as the hours you keep feeding it.

Done-for-you content and newsletters fill an inbox. They are another subscription to administer, parked away from anywhere your clients spend their time, and nobody goes back to a newsletter the way they go back to a home search.

Paid advertising scales with spend and stops with spend. Vermont adds a second problem: outside Chittenden County the audience pools are often too thin to optimize against reliably, so you pay metro prices for rural reach.

The pattern across all seven is the same. Each one either rents you a stranger or asks you to build the platform yourself, and the platform is the expensive half. The alternative is to work from behavior. Someone who already knows you runs a valuation, reopens a search they abandoned in March, or returns to the same three saved homes inside a week. A model can guess at a stranger. This is a person telling you they are moving.

What Vermont’s flood disclosure rule and property tax changes give you to talk about

Two pieces of Vermont law changed what a listing conversation sounds like here, and each of them hands you a reason to call an owner.

The first is Act 121 of 2024, the Flood Safety Act. A seller has to disclose flood risk in writing, in a separate document attached to the contract rather than buried inside it. The disclosure covers any flooding or flood damage that occurred while they owned the property, whether the property sits in a FEMA-mapped special or moderate flood hazard area, and whether they carry flood insurance or are federally required to carry it. The teeth are the part to know: a buyer who never receives that disclosure can terminate before the transfer of title or occupancy, and can sue for damages and reasonable attorney’s fees. This is a standing obligation on residential sales in Vermont, not a form that expires.

The second is Act 73 of 2025, which rewrote how Vermont funds education. It created a separate property tax class for second homes and moved the system away from income sensitivity and toward a homestead exemption. The numbers moved with it. Vermont capped the fiscal 2026 education property tax increase at 1.1% against a projected 5.9%. For fiscal 2027 the average homestead education tax rate, which is charged per $100 of assessed property value, is projected at $1.54, down from $1.59. Total homestead taxes are still forecast to rise 4.6%, because assessed values climbed more than the rate fell. The Department of Taxes owes a homestead exemption design by December 15, 2026.

Whatever an owner concludes about any of that, they are thinking about it. A property tax bill that moves is one of the few things that reliably starts a homeowner wondering what the house is worth.

A third compliance surface sits underneath all of it, and most agents never see it coming. Start prospecting by phone or by text, and the law files you under telemarketer. Should the person on the other end dispute consent, proof is yours to produce, for every number dialed. ezVerify.ai covers that side. It captures the opt-in and stores the proof, screens numbers against a known-litigator database before anyone dials, clears out Do Not Call registrations, and supplies contact detail you would otherwise spend an afternoon chasing down. Its job is consent and compliance rather than scoring, and the documentation exists before anyone disputes anything, which is the only moment documentation can help.

What an Exclusive County Partnership does in a state with 14 counties

Real estate agent holding a tablet showing a bedroom to a smiling couple beside a large window with greenery outside
One partner per county, co-branded across the search buyers and sellers already use.

A single Vermont county belongs to a single agent, team, or brokerage. Their brand rides the search experience the county’s buyers and sellers already use, and nobody else holds that position inside the territory. The cost is one predictable fee, with no per-lead billing and no cut taken out of a closing, so a busy month pays the partner rather than the invoice.

Those connections convert because of what sits underneath them. By the time someone reaches an ez Home Search partner, they have been searching on a platform that does not sell their contact details and budget to a list of businesses they never chose. A Single Local Expert was picked for them on fit, ahead of any question of who bid most to reach them. They also arrive carrying a history you can read: the price band they kept returning to, the neighborhoods they searched over and over, the valuation they ran twice inside a month. Trust that normally takes weeks is half built before the first call.

Four parts of that matter more in Vermont than they would somewhere larger.

The database you already own is the highest-return asset in the business, and in Vermont that is not close. With roughly 193,000 owner households here and only a few thousand primary-home sales in a year, the past clients you already earned outweigh anything you could buy. Most agents leave that asset sitting. ez Home Search partners reactivate those past clients, through repeat business and through referral, delivering 2.5 to 5 times the market rate, well past that in plenty of cases, because a home search wearing the partner’s own brand is somewhere a past client returns without being prompted.

The listing a departing client leaves behind is the part that gets lost. Census figures show roughly 2.1% of Americans crossing a state line in a year, with about another 3% moving to a different county without leaving their state. Across the years you stay in touch with a client, those odds accumulate. The house they leave behind is a listing that should be yours, and it usually goes instead to whoever they met on a legacy portal while shopping their new market. National coverage means they shop that new market on your own platform, and the searches they run there surface as an early signal that a move has started.

Recognition across a whole county is worth more than most agents price it at. Research from the National Association of Realtors puts numbers on it. Sellers overwhelmingly stop at one agent, 81% of them, before they choose. Repeat buyers interview a single agent 77% of the time, and 35% of sellers rank reputation above every other factor. Most of the time no comparison happens at all, and the recognized name has already won. In a 14-county state, that position is reachable in a way it never is in a state carrying a hundred of them.

The conversion tools you never build or operate arrive already running. You get a valuation widget for your own site, a QR-code open-house page that signs visitors in as they arrive, a home-value page, a fast cash offer for the owner weighing whether to skip the open market, plus the listing alerts and the local market reports. The follow-up runs off the same record of activity, and in Follow Up Boss, ezNurture handles the automated outreach. All of it sits on ez Home Search’s national platform with your name on it, inside the same one fee.

Underneath every piece of that sits the reason people engage deeply enough for any of it to work. The Only Confidential Home Search means a searcher’s contact details and spending power stay out of the resale market entirely, never handed on, never rented again, never broadcast across a row of businesses the person did not choose. That is the whole of it, and it is what ez Home Search means by A Better Way To Discover Real Estate. Apple, DuckDuckGo, Brave, Proton, 1Password, and Bitwarden each grew a business on that same premise inside their own categories. What we hear from county exclusivity partners is that clients raise it themselves, without being asked.

Why county position in Vermont is scarcer than it looks

Vermont has 14 counties, and that is the entire supply. Some states hold more counties inside a single metropolitan area than Vermont has altogether, and only one agent, team, or brokerage holds each one. That map does not grow.

The distribution tightens it further. Chittenden County alone accounts for more than a quarter of everyone in Vermont, which leaves the other 13 counties splitting the rest between them. Counties are claimed continuously, with more spoken for each month, so the picture looks different from one quarter to the next.

Size is not the sorting mechanism most agents expect. The model behaves the same in a county of 169,758 people and a county of 5,982, because a small market rewards the recognized local name every bit as heavily as a large one does. In Vermont’s smaller counties it is also reachable, and that is the part that stops being true in a metro of two million. A team that would spend a decade and more money than it has trying to become the known name across a large county can become the known name across a Vermont county and keep it.

Everything you step into is already built and already running. The search, the listing alerts, the valuations, the market reports, and your brand across all of it sit on a platform millions of people already use. Your name goes on it, and day one is a working day.

The decision in front of a Vermont agent

The path most Vermont agents are already on is to keep buying shared leads, keep paying per name or per closing, and hope volume covers a thin conversion rate. In a market producing a few thousand primary-home sales a year against more than 2,000 Realtors, volume is the one thing that will not show up to rescue it.

The second path is to build the whole apparatus yourself. That means an IDX site that ranks, a valuation engine accurate enough to put your name on, school and property-tax data across 14 counties, listing alerts people open on a Tuesday, a content operation that runs every week without you, and consent documentation that survives a dispute. Every piece of it is buildable. Assembled, it is a technology company, and you already have a full-time job showing houses.

The third path is to take the county and let a platform that already exists run underneath your name.

The honest cost of that third path is worth stating before you weigh it. County exclusivity is a commitment rather than a trial, and the two effects that matter most, reactivating the database you own and becoming the recognized name across a county, compound over quarters instead of landing in week one. The reasonable short-term expectation is 30 to 60 days to convert an opportunity into a client. If what you need is this month rescued, look elsewhere first.

What the third path does deliver is the return no outside lead source can sell you. Repeat and referral business through an ez Home Search partner posts 2.5 to 5 times the market rate. Business the partner earned once comes back a second and a third time, in a state where the same 193,000 owner households will be trading houses with each other for the next thirty years.

Vermont has 14 counties. Find out whether yours is still open.

Frequently asked questions

A Vermont county averages about 46,000 people. Is countywide brand recognition realistic for one agent or team at that size?

Yes, and it is the main structural reason this model fits Vermont. Several Vermont counties hold fewer than 30,000 people. One strong team can realistically become the name people associate with real estate across a territory that size, which stops being true in a county of a million. The catch is supply. There are 14 counties, one partner each, and no more being made.

Vermont’s population fell in 2024 and 2025 while its household count rose. Which of those two numbers should my marketing plan follow?

Follow the household count, every time. Homes are bought and sold by households, and in Vermont the two lines moved in opposite directions. Primary-home sales cleared 8,000 a year from 2019 through 2021, fell to 5,759 in 2023 as rates climbed, then rose about 9% in 2024 and rose again through 2025. The Joint Fiscal Office found the household count rising in both of the years the population dipped. Plan against the number that signs the paperwork.

Roughly one in six Vermont homes is a seasonal or vacation property. How do I reach owners who live out of state?

Not with the tools built for residents. Every one of them assumes the owner is nearby, whether that is door-knocking, farming, an open house, or a postcard drop, and 38% of Essex County’s housing stock and 37% of Grand Isle’s belongs to somebody who is not. What reaches them is a home search and a monthly value update they already use, carrying your brand, arriving wherever they spend the rest of the year. Seasonal owners still watch what the Vermont property is worth, and that watching is your opening.

In 2024 the median primary home sold for about $200,000 in Essex County and $500,000 in Chittenden County. How should my marketing differ between the Northeast Kingdom and the Burlington area?

The price gap is the smaller difference. The buyer is the bigger one. Around Burlington you are frequently working a move inside the county, with a rental market that loosened to roughly 3% vacancy by June 2025 releasing first-time buyers into the market. In Caledonia, Orleans, and Essex, the three counties whose price-to-income ratios sat inside the affordable range in 2022, you are more often working affordability, remote-work arrivals, and seasonal owners deciding to convert to full time. A message tuned for South Burlington reads as irrelevant in Newport.

What does Vermont’s Act 121 flood disclosure requirement change about how I list a property?

It adds a written step you cannot skip and a liability if you do. Your seller has to disclose, in a separate document attached to the contract, any flooding or flood damage during their ownership, whether the property sits in a FEMA-mapped special or moderate flood hazard area, and whether flood insurance is carried or federally required.

A buyer who never receives that disclosure can terminate before the transfer of title or occupancy, and can sue for damages and reasonable attorney’s fees. Build it into your listing intake rather than into the closing scramble.

Vermont homeowners are asking about the Act 73 education property tax changes. Can I use property tax questions to open listing conversations?

Yes, and it is one of the steadier openers Vermont hands you. Act 73 of 2025 created a separate tax class for second homes and shifted the system toward a homestead exemption. The fiscal 2026 education property tax increase was capped at 1.1%, and fiscal 2027 homestead taxes are forecast to rise 4.6% even with the average rate projected down to $1.54 from $1.59.

Owners notice a bill that moves. A conversation about what the change does to their carrying cost turns naturally into a conversation about what the house is worth.

Vermont’s owners are among the oldest in the country and only about 3% of them sell in a given year. How do I stay present for the rest?

You do not do it by calling them. You stay in front of them by owning something they return to on their own: a home search carrying your name, a monthly value update on their own property, and local market reports worth opening. That keeps you present without you having to invent something to say every month.

Then the activity does the sorting. When one of those owners runs a second valuation or reopens a search they abandoned, that behavior tells you which of the 97% just moved into the 3%.

Fiber is reaching rural Vermont through Communications Union Districts. Does better broadband change buyer demand in places like Rutland County or southeastern Windham County?

Yes, and you can trace it to where the fiber landed. Otter Creek’s completed build reached 3,626 locations in the Rutland County region, 1,278 of which had no service at all. DVFiber reached nearly 5,000 locations in southeastern Vermont, with roughly 60 more miles running through West Brattleboro, Dummerston, Marlboro, Newfane, and Guilford targeted for August 2026.

A household that cannot hold a video call cannot seriously consider a house in that town. Vermont already ranks seventh nationally for working from home, at 15.96% in 2024 against 7.04% in 2019, and the towns getting service last are the ones with the most ground left to gain.

08.14.2026

Ohio Real Estate Leads: Reaching Owners Before They List

Ohio real estate leads start with a number the county just mailed

The best Ohio real estate leads are not bought. They arrive on a schedule the state publishes years ahead of time.

Every Ohio county revalues its property under a fixed statutory cycle, a full reappraisal every six years with an update three years between. Forty-one counties were in a valuation year for tax year 2026, which put a new official number for someone’s home into several hundred thousand mailboxes across the state.

That number is not what the home would sell for. Butler County‘s auditor puts the office’s values at roughly 90% of full market value, and a six-year figure absorbs six years of movement in a single step rather than showing one year of appreciation. It does not move a tax bill one for one either.

The owner opens the envelope and gets a question instead of an answer. What is this place worth?

The county will never give a selling valuation, even though the law calls its assessment an appraisal. That gap is a trigger event, and a wise agent can build a year of listing conversations around it. Most agents and brokers miss it. What follows is how to work it, county by county, across Ohio.

Ohio’s housing market is steady, priced unevenly, and growing again

Bar charts compare Ohio cities’ median home prices, closed sales volume, and inventory for Q3 2023 vs Q3 2024, highlighting trends valuable for Ohio real estate leads.

Ohio closed 126,015 homes in 2025, and statewide volume has sat in a steady band for three years running. Ohio REALTORS® recorded those closings against 124,446 in 2024, a gain of 1%. On the association’s prior reporting basis, a separate count that does not line up with the current one, 2024 finished at 131,716 against 129,064 the year before, a gain of 2.1%. The two measuring sticks give the same answer. Volume is flat to slightly up.

That answer matters because the 2021 peak of 169,585 sales still shapes how people talk about this market. It was a low-rate anomaly. A comparison to that peak invents a decline the longer record does not support. The pre-pandemic years ran about 153,000 to 155,000 sales on the association’s older count, so today’s level sits modestly below a normal pre-pandemic year and nowhere near the 2021 high.

Prices have climbed steadily rather than sharply. The statewide median reached $263,000 in March 2026, up 6.5% from $247,000 a year earlier, and the 2025 average sales price finished at $256,775, up 6% over 2024.

Inventory is expanding from a low base. Active listings reached 31,489 in March 2026 against 26,868 two years earlier, and supply sits near three months where six is treated as balanced. Read that second figure carefully. Months of supply counts what is sitting on the market at a single moment, and it says nothing about how many homes close over a year. Ohio’s closings have been steady while its shelf has been thin.

The price spread inside the state is wider than the statewide median suggests. Central Ohio’s median hit $350,000 in May 2026, up 4.3%, on 2,618 single-family closings, per Columbus REALTORS®. Greater Cincinnati‘s median sold price reached $300,000 in January 2026, up 10%, with active inventory up 32.1%, per the REALTOR® Alliance of Greater Cincinnati. An agent working a $350,000 Central Ohio median and one working a county at half that price are running different businesses.

Ohio is also gaining people again, which cuts against how the state usually gets described. Census figures show a net gain of 11,926 residents between 2024 and 2025, the highest in-migration in 25 years, and Ohio was one of only four states to post more births, fewer deaths, and improved domestic migration at once. Keep that in proportion. Against a population near 11.9 million and 126,015 annual closings, migration moves a fraction of a percent and is a minor driver of transaction volume next to the owners already here. It runs both directions too, and both directions are business: arrivals are buyers, departures are listings.

The job base underneath all of this is broad rather than concentrated. Manufacturing employs more than 680,000 people and produces 17.5% of state GDP. More than 640 aerospace companies operate here, and federal and military installations support over 400,000 jobs and nearly $55 billion in gross regional product, per JobsOhio, alongside healthcare and life sciences, logistics and distribution, financial services, and food and agribusiness.

The capital projects deserve an honest timeline. Intel’s Ohio One campus in New Albany, Licking County, represents more than $28 billion and roughly 3,000 manufacturing and 7,000 construction jobs, but the two initial fabs have slipped to 2030 and 2031 from an earlier end-of-2026 target. The Honda and LG battery plant runs about $3.5 billion, Anduril is building its Arsenal-1 campus, and an AWS data-center buildout approaches $10 billion. Agents farming for these should plan in years, not quarters.

Growth is not spread evenly either. JobsOhio projects employment growth of 8% in Central Ohio, 6% in the Southwest, 4.1% in West Ohio, 4% in the Southeast, 3% in the Northeast, and 2.7% in the Northwest. Ohio was named CNBC’s top state for business in 2026 and has ranked first in infrastructure three years running.

CountyPopulation (2025)County seatNote
Franklin1,361,536ColumbusState capital; added 8,880 residents, the largest county gain in Ohio
Cuyahoga1,232,925Cleveland
Hamilton838,418Cincinnati
Montgomery539,598DaytonAdded 2,668 residents
Summit538,376Akron
Lucas423,347Toledo
Butler400,128HamiltonHamilton is both the seat and the largest city, at 64,817
Stark373,771CantonCanton population 69,211
Lorain323,219ElyriaElyria is the seat at 53,604; Lorain is the larger city at 65,435
Warren257,181LebanonLebanon is the seat; Mason is the larger city at 36,088

Ohio’s ten most populous counties. County populations are US Census Bureau estimates for July 1, 2025; city populations are Ohio Department of Development 2024 estimates.

Two of those rows carry a distinction worth holding onto. Lorain County is run from Elyria but its largest city is Lorain, and Warren County is run from Lebanon while Mason carries more people. A county campaign addressed to the wrong one reads as outside work to the owners who live there.

Most Ohio buyers are also sellers, and the seller-only playbook misses four in five of them

A woman arranges pillows on a sofa while a man with a clipboard observes, discussing Ohio real estate leads in a bright living room.

About four in five buyers are carrying a house they have to sell in order to buy the next one, so an agent who markets only to sellers is competing hard for a fifth of the opportunity and ignoring the rest.

Start with the mistake, because most lead strategies contain some version of it. One campaign says list with me. A separate budget buys cold buyer leads. The two halves of a single move get handled as two different customers in two different systems, and the person doing both at once falls straight between them.

The National Association of Realtors put numbers on it in the 2025 Profile of Home Buyers and Sellers. First-time buyers fell to 21% of purchases nationally, a record low since tracking began in 1981, and the median first-time buyer reached age 40. Before 2008 that share ran near 40%. Ohio does not publish a clean state equivalent, so treat the 21% as the national anchor it is.

Be precise about what it means. Any individual sale still has two parties standing on opposite sides of it. The point is that the same person is usually both across their own move, and they almost always begin on the buy side. They look at what their money buys long before they call anyone about listing. An agent waiting for a listing signal meets that person late, after another agent has already earned the relationship and, with it, the listing.
Three groups come out of that math. First-time buyers, the one in five, have no existing home behind them and need affordability and a plain explanation of how the process works, not equity math. The much larger group trading up, down, or across has to solve three things at once: what the current house frees up, how the two closings line up, and what the next purchase costs. Estates and exiting landlords, the owners with no purchase waiting on the other side, are the smallest group of the three.

Ohio has an unusually deep pool for this. The state’s homeownership rate reached 70.3% in 2025, up from 69.6% a year earlier and 5.1 points above the national rate, which means roughly five in seven Ohio households own. Set that against 126,015 closings and the picture is clear: the owners who did not transact this year are next year’s move, already living in the county.

ez Home Search is built to work the person rather than the side. A valuation check, an equity question, or a visit to a home-value page opens the seller conversation. Saved searches, alerts opened, and a tour request show the buyer side coming to life. Most people run both in sequence, and the platform follows the shift instead of guessing. The automated valuation model, an AVM, keeps a partner present through the quiet stretch when someone is only wondering, which is exactly when the relationship gets decided.

Only one partner holds an Ohio county at a time, so the first practical step is checking whether yours is still open.

What Ohio agents use for leads now, and the point each channel stops working

A woman in business attire talks on the phone, writes in a notebook, and reviews Ohio real estate leads on her laptop in an office setting.

Every method Ohio agents use to find business works, which is exactly why the limits are worth naming plainly rather than pretending one channel replaces all of them.

Start with the arithmetic, because it explains the pressure. Ohio REALTORS® has more than 35,000 members and the state closed just over 126,000 homes in 2025. Spread evenly, that is fewer than four closings per member per year. Nobody is evenly spread, and volume has been steady rather than growing, so the agents who grow are taking share from the agents who do not. That is the game in Ohio, and every lead decision an agent makes is a decision about share.

Shared leads from legacy portals give an agent volume immediately with nothing to build, which is a genuine advantage when a pipeline is empty. The trade sits in the structure. One name lands with several agents simultaneously, the consumer picked none of them, the cost repeats with every lead, and the conversation opens cold because the person has no reason to prefer whoever dials first.

An IDX site solves the ownership problem. The site is an asset that compounds, and the agents who commit to one for years are usually glad they did. The trade is time and depth. The site takes quarters rather than weeks to rank, the content and technical upkeep never stop, and the data behind accurate valuations, school detail, and property-tax comparisons costs more than any single team or brokerage can reach on its own. Initial traction can arrive in months. The agents and local brokers I have watched build a real market position this way spent three to five years and millions of dollars getting there. That can be a wise investment when it is implemented well, and it asks for more time, more money, and more sustained focus than most will put in.

Disciplined operators still produce with cold calls, for-sale-by-owner outreach, and expired listings, and a good caller will outperform a mediocre ad budget every time. Two limits apply. The output stops the day the calling stops, since nothing compounds, and phone and text prospecting puts an agent inside the consent rules whether or not they realize it. If a recipient disputes consent, the burden sits with the caller to produce proof for every number dialed.

Predictive-seller software narrows a database to the names likeliest to move, which beats working a list alphabetically. A score is still not a relationship. Someone has to earn the trust that carries a name from a probability to a signature, and that work stays with the agent.

Generic all-in-one platforms consolidate the stack into one bill and one login, and that consolidation is worth real money. The cost shows up as administration. The agent becomes the person configuring, maintaining, and troubleshooting the system, and none of it gives a past client a reason to return on their own. A CRM is a place the agent goes, and the client has no reason to open it.

Do-it-yourself content and paid advertising keep control in the agent’s hands. Both stop the moment attention or spend stops, and content quality is the first thing to slip in a month with three closings and a family in contract.

None of these choices is a mistake. They share one limit: each works on the small share of people transacting right now, and none holds the far larger group who will transact in a year or three. Those owners are already living in the county, watching their value, and moving toward a decision without announcing it. The harder problem is reaching them early, and that is the one worth solving.

Ohio’s reappraisal calendar is a listing conversation with a date on it

Ohio publishes, county by county and often community by community, exactly when hundreds of thousands of owners will be handed an official number about their own home, which makes it the most predictable home-value conversation available anywhere in the state.

Ohio property value notice and paperwork on a desk, representing a county reappraisal review
A county valuation notice raises a question about market value that the county itself will not answer.

The mechanism is statutory. Each county runs a full reappraisal every six years, with a lighter update three years in between, and 41 counties sat in a valuation year for tax year 2026, per Ideastream Public Media. The schedule is published in advance, so an agent can know which counties are in play and roughly when the mail lands.

The 2026 figures show how much the answer varies. Butler County’s median residential and agricultural values rose 19%, with commercial and industrial up 20%, on an abstract the Ohio Department of Tax Equalization approved on June 25, 2026, per Auditor Nancy Nix. Montgomery County came in near 19% as well, lifting total county value from about $39 billion to nearly $46 billion, with more than 150,000 notices mailed starting July 13, 2026, per Auditor Karl Keith. Franklin County‘s triennial update ran lighter, at a tentative average near 9% residential per the county Auditor’s Office, with values mailed from June 9, 2026 and informal review open from July through September. Summit County‘s fiscal office reported 18%. Ashtabula County‘s auditor reported about 30%. Mahoning County‘s auditor reported average residential property taxes up about 24%.

Two other counties are worth knowing about precisely because they are on a different clock. Cuyahoga County‘s 2024 reappraisal averaged 32% countywide, ranging from 15% in Hunting Valley to 67% in East Cleveland, and Lucas County‘s 2024 revaluation ran 29.6% with its next one now moved to 2028. Owners there are living with those numbers without a fresh letter to explain them.

Butler County published its results down to the jurisdiction, which is where the useful detail sits.

Jurisdiction, Butler CountyMedian residential value change
Lemon Township39%
New Miami32%
Middletown30%
Hamilton27%
Sharonville24%
Trenton22%
Butler County overall19%
West Chester Township18%
Fairfield Township15%
Oxford15%
Fairfield12%

Selected jurisdictions from the Butler County Auditor’s 2026 reappraisal, June 30, 2026. The full published set runs to 23 jurisdictions.

A 27-point spread inside one county is the whole point. Two owners in the same county opened envelopes describing different realities, and no statewide average would have told either of them anything useful about their own house.

Most owners get the next part wrong, and it is where an agent becomes genuinely useful. A value change is not a tax change. Ohio House Bill 920, on the books since 1976, keeps many property taxes from rising in step with values, and Mahoning County Auditor Ralph Meacham gave the cleanest illustration of it: at the prior revaluation, an average 38% valuation increase produced about a 7% increase in property taxes. Butler County’s auditor adds that bills track voted levies more closely than value changes, and puts dollar figures on them. Mills are the unit a levy rate is set in, and because only a portion of a home’s value is taxed, the auditor publishes what each one costs per $100,000 of home value. A countywide two-mill developmental disabilities levy runs roughly $70. A Fairfield Township fire levy at 4.49 mills runs about $157. A two-mill Fire and EMS levy in Milford Township runs about $70.

A value change is not a market price either. Butler County’s auditor states that the office’s values run at roughly 90% of full market value across all taxing districts, by design. A six-year number also compresses six years of movement into one line, so it reads like a sudden jump when it is a delayed accounting.

Put those together and the opportunity is obvious. An owner is holding a number that is not their market value, attached to a bill that will not move the way they fear, on a date the agent could have known months in advance. They want a real number and a straight explanation. Whoever provides both is the person they call when they eventually sell.

Ohio’s regions do not behave alike

Ohio’s six regions diverge enough that a statewide number describes almost none of them accurately, and the gap between the highest and lowest regional job-growth projections is nearly three to one.

Cleveland, Ohio skyline at dusk with tall buildings and a bridge over the river
Northeast Ohio absorbed the heaviest valuation increases of the 2026 cycle.

Central Ohio is the growth engine. JobsOhio projects 8% employment growth there, the highest in the state, and the housing numbers follow: a $350,000 median in May 2026, up 4.3%, on 2,618 single-family closings, per Columbus REALTORS®. Licking County carries the Intel campus, and Delaware and Union counties are absorbing the spillover. An agent here is working the highest prices and the most competition in Ohio at the same time.

Southwest Ohio is close behind at 6% projected growth. Greater Cincinnati’s median sold price reached $300,000 in January 2026, up 10%, and the more interesting number is inventory: active listings up 32.1% year over year, per the REALTOR® Alliance of Greater Cincinnati. More listings and rising prices at the same time is what a market getting healthier looks like. Butler and Warren counties sit inside this region and both are in the middle of valuation cycles.

Northeast Ohio is where the 2026 valuation wave landed hardest. Summit came in at 18% and Ashtabula near 30%, and Cuyahoga’s owners are still absorbing a 32% average from 2024. Projected job growth is 3%, the second lowest in the state, which makes the region a reminder that a slow labor market and an active housing market can sit in the same place. Cuyahoga, Summit, Lorain, Stark, Medina, Portage, Geauga, Lake and Trumbull counties together hold more people than any other region in Ohio, and every one of those owners has a home value they are curious about.

Northwest Ohio carries the state’s slowest projection at 2.7%. Lucas County’s 2024 revaluation ran 29.6% and its next one moved to 2028, so owners around Toledo are working from a number that is already aging. Wood, Ottawa, Sandusky, Hancock and Allen counties round out a region where the recognized local name still decides most listings.

Southeast and Appalachian Ohio is the largest and least understood piece of the state, a run of 32 contiguous counties with no major metro among them, and JobsOhio projects 4% job growth there. Buyers in those counties shop against the $263,000 statewide median rather than Central Ohio’s $350,000. Thin population is usually read as thin opportunity. It also means a single recognized agent can hold a genuine position across a whole county in a way that is impossible in Franklin.

West Ohio and the Miami Valley sit at 4.1% projected growth, anchored by an aerospace and defense base that JobsOhio ties to more than 400,000 jobs statewide. Montgomery County’s 2026 reappraisal came in near 19%, and Greene, Miami, Clark, Darke and Preble counties surround it.

RegionProjected job growthA current market fact
Central Ohio8.0%Median price $350,000 in May 2026, up 4.3%, on 2,618 single-family closings (Columbus REALTORS®)
Southwest Ohio6.0%Greater Cincinnati median $300,000 in January 2026, up 10%, active inventory up 32.1% (REALTOR® Alliance of Greater Cincinnati)
West Ohio and the Miami Valley4.1%Montgomery County’s 2026 reappraisal averaged about 19% (Montgomery County Auditor)
Southeast and Appalachian Ohio4.0%32 contiguous counties with no major metro; buyers shop against the $263,000 statewide median of March 2026, not Central Ohio’s $350,000 (Ohio REALTORS®; Columbus REALTORS®)
Northeast Ohio3.0%Summit County values up 18% and Ashtabula about 30% in the 2026 cycle (county offices)
Northwest Ohio2.7%Lucas County’s 2024 revaluation ran 29.6%; next revaluation moved to 2028

Job-growth projections are JobsOhio figures. Market facts are dated to their sources.

The practical read is that a lead strategy tuned to Columbus prices will misfire in Ashtabula, and one built for a rural county will leave money on the table in Delaware. Whatever an agent uses has to work at the county level, because the county is the level at which Ohio differs. The fastest way to find out what that looks like in a particular market is to check whether that county is still open.

Ohio counties beyond the big metros

Ohio has 88 counties and only a handful of them contain a major metro, which means most of the state is made up of places where one recognized agent can still own the whole conversation.

People walking and cycling on a brick-lined Ohio street beside a farmers market and historic storefronts
Outside the largest metros, one recognized agent can hold an entire Ohio county.

The economics favor the smaller county in a way that gets overlooked. In Franklin County an agent is one voice among thousands, competing for attention in a market where a $350,000 median attracts every national marketing budget in the business. In Wayne County or Ashtabula County the same effort buys a position that competitors cannot copy from outside, because local recognition there is built on being present rather than on outspending anyone.

The reappraisal cycle reaches these counties on exactly the same schedule as the metros. Wayne County ran a full sexennial reappraisal in 2026. Geauga County ran a triennial update, and Ashtabula County was revalued in the same 2026 cycle at an average near 30%. Owners in a county of 40,000 people get the same envelope, ask the same question, and have far fewer places to take it.

CountyRegionCommunitiesWhat is happening there
DelawareCentral OhioDelaware, Powell, Sunbury, Genoa Township254 closings in May 2026 at a $539,000 median, up 10.5% (Columbus REALTORS®)
UnionCentral OhioMarysville, Plain City, Richwood, Jerome Township118 closings in May 2026, up 34.1%, at a $487,500 median (Columbus REALTORS®)
LickingCentral OhioNewark, Pataskala, Heath, GranvilleHome to the Intel campus, with the first two fabs now targeted for 2030 and 2031
MedinaNortheast OhioMedina, Brunswick, WadsworthSits between the Cleveland and Akron job markets without belonging to either
PortageNortheast OhioRavenna, Kent, Streetsboro, AuroraA university county with a commuter base pointed at both Akron and Cleveland
WayneNortheast OhioWooster, Orrville, RittmanCompleted a full sexennial reappraisal in the 2026 cycle
GeaugaNortheast OhioChardon, Middlefield, Burton, ChesterlandRan a triennial update in the 2026 cycle
AshtabulaNortheast OhioJefferson, Ashtabula, Conneaut, GenevaValues up about 30% in the 2026 revaluation, after about 32% three years earlier

County seats are Delaware, Marysville, Newark, Medina, Ravenna, Wooster, Chardon and Jefferson. Community lists are drawn from county government sources.

None of these counties will produce Franklin County’s volume, and none of them needs to. A partner who holds one of them owns the whole market rather than a slice of it, for as long as they hold the position, and the owners there open the same envelope on the same schedule as everyone else in Ohio.

Remote and hybrid work still decides which Ohio counties buyers want

Remote work did not go away. Agents who take the headlines at face value are handing an advantage to the ones who went and read the data.

Two-story brick suburban home in Ohio surrounded by blooming trees under a clear sky
Remote and hybrid buyers shop for a room with a door, a separate structure, and broadband that holds up.

The decline story rests on a single measurement choice: comparing today against May 2020, when roughly 61% of paid workdays happened at home. No economist treats that emergency peak as an equilibrium. Measured against the pre-pandemic baseline of about 5% to 8% of paid workdays, the picture is a structural tripling that has held steady since 2023.

The federal data says the same thing. Nationally, 36.7 million people teleworked for at least part of their week during the last quarter of 2024, up on 32.5 million a year prior, which moved the national rate from 20.7% to 23.4%. Those are Bureau of Labor Statistics figures. Employers report the same stability: across roughly 150,000 firms canvassed from November 2024 into January 2025, 31.2% had someone putting in a full workday at home, and the same employers forecast essentially that share five years ahead. The source there is the Census Bureau, in its Business Trends and Outlook Survey. They are planning for this to continue.

That matters for Ohio geography specifically. Rural America reversed more than a decade of population decline starting in 2020, gaining 974,000 net migrants through 2024, and the USDA Economic Research Service finds the gain concentrated among working-age adults between 25 and 44 rather than retirees. Those national findings land somewhere, and in Ohio they land in the places where the math works: the Appalachian counties across the southeast, the exurban ring beyond Delaware and Union, and the mid-size counties around Wooster, Chardon and Ravenna. A household earning a Columbus or Cleveland salary and shopping against a $263,000 statewide median rather than a $350,000 Central Ohio one is making an obvious trade.

Ohio’s own migration turnaround is consistent with that. The state posted its highest in-migration in 25 years between 2024 and 2025.

The practical use is in showings. A remote or hybrid buyer needs an office that shuts, and a corner of the dining table does not qualify. They ask about a detached structure or an accessory dwelling unit before they ask about the primary suite. They want square footage that a hybrid schedule justifies, and they will walk from a house whose broadband cannot carry a full day of video calls. An agent who leads with those four features in a mid-size Ohio county is speaking directly to the buyer everyone else assumes stopped existing.
What an Ohio partner gets from holding the whole county

The territory in an Exclusive County Partnership is a whole Ohio county, held by a single agent, team, or brokerage. Their brand runs across the consumer experience, no rival partner works the same ground, nothing is billed per lead, and no piece of the commission goes anywhere at closing.
Older Ohio couple reviewing home paperwork and a laptop together at a sunlit kitchen table
Most of a county’s owners are not transacting this year, which is exactly why the database matters.

That last part changes the arithmetic. A strong month costs the same as a slow one, so a partner who works the county harder keeps the upside instead of paying it back in per-lead fees. The fee is predictable, and the flow does not spike with a campaign and disappear when the budget does.

Start with the answer to that envelope. The automated valuation model, home-value pages, and monthly value updates carry the partner’s brand, which means the Summit County owner staring at an 18% increase and the owner in Hamilton looking at 27% both have somewhere to get a real number. That is the moment the relationship gets decided, and it arrives on a schedule the partner can plan around rather than one they have to chase.

The bigger opportunity is the contact list a partner already has. Ohio’s 70.3% homeownership rate means most of a county is made up of owners, and most agents let their past clients go cold. Repeat business and referrals make up roughly 41% of production across all agents, and while the share of buyers who say they would hire their agent a second time runs from 88% to 92%, only about 18% do. That gap is business already earned and then lost. On the ez Home Search platform that gap narrows sharply: past clients come back to a partner, buying again or sending someone, at between 2.5 and 5 times the market rate. The reason is plain: the home search they keep going back to has that partner’s name on it. The platform also holds the list together. Every year a meaningful share of email addresses stop working, on the order of 15% to 22%, while up to one person in ten changes a phone number, and ongoing engagement captures the new details as they change.

Relocation is the second leak, and Ohio’s two-sided movement makes it live. Census figures put interstate moves at roughly 2.1% of Americans a year, with about another 3% crossing a county line inside their own state. Put together, that is roughly one American in twenty each year moving past whatever territory a single agent covers. When a past client starts searching Arizona on the partner’s own co-branded platform, that search surfaces as a signal. The agent cannot sell in Arizona, but the house that client owns in Medina County is a listing in play, and the agent now knows about it before it lists with someone else.

The recognized county name is what compounds all of it. The National Association of Realtors puts numbers on that in its Profile of Home Buyers and Sellers: 81% of sellers reach out to a single agent and stop there, 77% of repeat buyers interview exactly one, and reputation is the single most important factor for 35% of sellers. For most people there is no comparison shopping at all. The recognized name wins before the conversation starts, and in an Ohio county of 60,000 people that position is achievable in a way it never will be in Franklin County.

The compliance layer sits underneath the outreach. An agent working an ez Home Search opportunity gets the consent question answered before they dial. ezVerify.ai captures the opt-in and the recording behind it, checks each number against a known-litigator database, suppresses every number listed on the national Do Not Call registry, and rounds out the contact record so nobody has to go looking for a missing phone or email. All of that is documentation, which is what matters if someone disputes consent and the burden of proof falls on the caller.

None of it produces a closing next week. Partners generally see the first conversions land in 30 to 60 days, and the reactivation and recognition effects build over quarters rather than weeks. That is the honest shape of it.

One partner per Ohio county, and the position does not reopen often

A real estate agent shows a house to a couple outside a brick home with an “Ohio Home Listing” sign, generating valuable Ohio real estate leads.

Ohio has 88 counties, one partner holds each one at a time, and a county that is taken stays taken for as long as that partner keeps it.

Counties come off the board steadily rather than all at once, and more get claimed every month. There is no way to know from the outside which Ohio counties are open at any given moment, and the honest answer for any specific one is that it takes a conversation to find out. What is worth understanding before that conversation is why a county is worth holding in the first place.

The reason sits underneath the whole platform. Legacy real estate portals earn their money by taking a person’s contact details, budget, and sometimes their relationship status and passing all of it to a long list of businesses: an agent, a loan officer, a title company, an insurance agent, sometimes a data broker. The consumer rarely learns who received it. ez Home Search runs on the opposite arrangement, and that structural difference is what the umbrella line “A Better Way To Discover Real Estate” describes.

The Only Confidential Home Search is how ez Home Search delivers that better way. Nobody sells, resells, recycles, or broadcasts a person’s contact details and budget to businesses that person never chose. One vetted local expert who knows their area takes it from there, picked as the right fit rather than as the highest bidder, and the rest of the vetted network, from loan officers to roofers, is theirs to call on when they want it. That is the Single Local Expert, and in an Exclusive County Partnership, that expert is the partner.

Ohio consumers are primed for this whether or not they can name it. Pew Research Center found that 81% of US adults are concerned about how companies use the data collected about them, and that more than four in ten have already switched to a browser or search engine that does not track them. People have spent a decade taking their privacy back everywhere else online. Apple built it into a product line. DuckDuckGo and Brave each reached around 100 million users on it. Proton, 1Password, and Bitwarden built their products so that the company holding the data cannot open it, and they sell that as the feature.

Real estate got there late, and ez Home Search is what brought the shift into it. For a partner, the practical consequence is that people engage more honestly with a platform they trust, which is why a connection through ez Home Search arrives warm, with real activity behind it, instead of as a cold name several agents are dialing at once.

Deciding whether an Ohio county partnership fits your business

An Ohio agent looking at lead generation has three real options, and the right one depends less on budget than on whether they intend to work a database.

One option is to keep buying shared leads. Volume arrives immediately, several agents work the same name, the cost repeats with every lead, and the flow stops when the spending does. Plenty of good agents run this way and always will.

Another is to build the equivalent alone: an IDX site that takes quarters to rank, a valuation product, a content operation that never stops, a compliance layer for consent, and a CRM to hold it together. Any single piece is achievable. The combination costs more than a team or a brokerage can reasonably spend, and the property data underneath accurate valuations is the part that stays out of reach no matter the budget.

The third option sits between them: hold one Ohio county on a platform where all of that is already built, already running, and carrying your name. That one carries no charge per lead, no split at closing, and one partner in the territory.

The trade-off is worth stating plainly. A county partnership is a fixed commitment that rewards consistency, and it pays back most to the agent who works the database that comes with it. An agent who wants leads delivered and nothing else asked of them will not get their money’s worth. The partnership is built around follow-up, and follow-up is work.

One proof point outweighs the rest. A partner’s own past clients return at between 2.5 and 5 times the market rate, buying again or referring someone who does. That is business already earned once and normally lost, coming back.

That returns to the envelope. Somewhere in an Ohio county this month, a homeowner is holding a valuation notice with a number on it that is not what their house would sell for, attached to a tax bill that will not move the way they fear. They want a straight answer from someone local. The agent who is already in front of them, with their name on the home search that owner has been using for two years, gets to be that person. Everyone else finds out when the sign goes up.

Ohio has 88 counties. Check whether yours is still open.

Frequently asked questions

My clients just got county reappraisal letters with double-digit increases. How do I turn that into listing conversations instead of tax complaints?

Answer the question they are asking before the one you want to ask. Most owners open that letter believing their taxes are about to rise by the same percentage, and they are wrong about that, so the first useful thing an agent can do is explain the difference and point them to their county’s informal review window.

The listing conversation follows on its own. Once someone understands the county’s number is not a market number, the obvious next question is what the house would bring on the open market, and that is a comparative market analysis. Partners who run a co-branded home-value page and monthly value updates are already in that conversation, because the owner has been checking their value there for months.

Does a higher county valuation mean my Ohio clients’ property taxes go up by the same amount?

No, and Ohio has a statute that is the reason. House Bill 920 has been law since 1976, and it holds many property taxes back when values climb. Mahoning County’s auditor gave the clearest recent example: at the prior revaluation, an average 38% valuation increase produced roughly a 7% increase in taxes.

Voted levies matter more than the reappraisal in most bills. Butler County’s auditor quantified its 2026 additions, with a countywide two-mill developmental disabilities levy costing about $70 per $100,000 of value and a Fairfield Township fire levy at 4.49 mills costing about $157. An agent who can explain that distinction is useful to an owner long before that owner needs anyone to sell anything.
Ohio’s property tax laws changed in 2026. What should I tell owners weighing a sale now?

Tell them the relief is real and the timing is staged. Four bills, House Bills 186, 335, 129 and 309, were signed into law, with estimated relief of more than $3 billion. House Bill 186 took effect in December 2025 and the others on March 18, 2026, while the general reductions reach owners with their 2027 tax bills. Changes to the owner-occupancy credit are projected to return more than $800 million to Ohio homeowners over four years.

For a seller, none of that changes what the house is worth. It changes the carrying cost a buyer has to absorb, which is one of the less obvious inputs into what a home can sell for.

Intel’s New Albany fabs slipped to 2030 and 2031. Should agents in Licking County still be farming for that growth?

Yes, though the clock is longer than the original one. The investment is still more than $28 billion for a campus sized to hold up to eight factories, with roughly 3,000 manufacturing and 7,000 construction jobs attached, and the site is not moving. What changed is the timeline.
Plan for it the way you would plan any long-cycle farm. Newark, Pataskala, Heath and Granville will absorb demand as construction ramps, and the agent who has spent those years building recognition in Licking County will be the name people know. An agent expecting a 2026 boom will be disappointed. An agent building a database through 2030 will not be.

Central Ohio’s median runs near $350,000 while the statewide median is closer to $263,000. How do I build a lead strategy that works in a lower-priced Ohio county?

Stop paying per lead. In a county where the median is well under the state figure, a per-lead cost eats a much larger share of a commission than it does in Delaware County, which is exactly why cost-per-lead models get painful outside the expensive metros.

That is the structural argument for a county partnership in lower-priced Ohio markets. The fee does not scale with your price point or your volume, so a strong month in Ashtabula County costs the same as a slow one. Recognition also comes faster where fewer competitors are spending, which means the position is cheaper to hold than the equivalent position in Franklin County.

Ohio recorded its highest in-migration in 25 years. How do I reach those buyers before they choose an agent?

Reach them while they are still searching from somewhere else. Census figures show Ohio gained 11,926 residents on net between 2024 and 2025, and Ohio was one of only four states to post more births, fewer deaths, and improved domestic migration at once. Those people research a market for months before they ever contact anyone local.

National coverage is what makes that visible. ez Home Search covers every state, so someone researching Medina or Delaware County from outside Ohio is doing it on a platform where a local partner is already the named expert. The same coverage protects the other direction: when your own past client starts searching Arizona, you learn about the move in time to win the listing on the house they are leaving.
How does a county exclusivity model work in a county like Lorain, where the county seat and the largest city are two different cities?

The partnership is drawn on the county line, so it covers both. Lorain County is administered from Elyria while its largest city is Lorain, and a partner holds all of it, along with Amherst, Avon, North Ridgeville and the rest.

That is an advantage rather than a complication. A campaign organized around a single city misses half the county in places like Lorain and Warren, where the seat and the largest city diverge. County-level exclusivity matches the way Ohio owners think about where they live, and it matches the way the county auditor mails valuation notices, which is one envelope to every parcel in the county on the same schedule.

08.13.2026

Virginia Real Estate Leads: Most Agents Meet Them Too Late

Virginia law requires every home to be assessed at 100% of its fair market value. In the Virginia Department of Taxation’s Assessment/Sales Ratio Study for tax year 2024, the statewide median came in at 75.17%, down from 83.25% the year before, and only eight of Virginia’s 95 counties and six of its 38 independent cities landed inside the 90% to 110% band assessors treat as acceptable.

Read that as a homeowner rather than as an assessor. The number in your client’s kitchen drawer is roughly three quarters of what the house would fetch.

Virginia real estate leads begin in that gap. Somebody in that house eventually looks up what it is worth, and the year they look is rarely the year they list. By the time most agents in the Commonwealth hear about it, the search already happened, the plan is already made, and another name was answering the question first.

Virginia’s market is working fine. Agents lose on timing, and the loss compounds every year they keep entering late.

Virginia’s growth moved, and most of the people who moved were already here

Between the 2020 Census and July 2025, Virginia added 248,714 residents to reach 8.88 million, and net migration accounted for 170,326 of that gain against 78,388 from births outnumbering deaths, according to the Weldon Cooper Center for Public Service at the University of Virginia. Migration was the larger share. It was not a large number.

Size it the way an agent should. Roughly 34,000 net arrivals a year, in a state whose closed home sales ran 122,051 in 2017, peaked at 154,340 in 2021, and dropped to 98,464 in 2023. Sales then rose in each of the next two years to 103,722 in 2025, and the first half of 2026 ran 5.5% ahead of the same stretch a year earlier, per Virginia REALTORS. Across those ten years the line traces a rate cycle that has already turned twice. Interstate movement sits at the edge of that market rather than at the center of it. In 2024 about 265,500 people moved into Virginia from elsewhere in the country and nearly 264,000 moved out, close to a wash, with Maryland, Florida, North Carolina, California, and New York sending the most and Florida, North Carolina, Maryland, California, and Texas receiving the most (Virginia REALTORS, May 2026).

Both directions are business. Every person leaving Virginia lives in a home here first, so a departure is a listing plus a referral into the receiving market. Every person arriving is a buyer who does not yet know a single agent’s name. An agent who reads out-migration as loss is reading half the ledger.

The internal movement matters more than either flow.

Of Virginia’s 133 counties and independent cities, 119 posted positive net migration between 2020 and 2025 and 93 grew outright. Growth was that widely spread. Where it concentrated is the useful part: the four fastest-growing localities in the state, New Kent County at 21.5%, Goochland County at 15.0%, Louisa County at 12.8%, and Chesterfield County at 10.1%, all sit in or beside the Richmond metro. Chesterfield added 36,753 people across those five years, more in raw numbers than any other Virginia locality and ahead of Loudoun County‘s 25,720. Fairfax County, the largest locality in the Commonwealth and its economic engine for decades, lost 2,795 over the same span.

The same pattern shows up region after region. People move out of the expensive metropolitan core and into the counties beside it. They are Virginians already. They own homes already. They will sell one to buy the next.

Household formation points the same direction. Virginia public K-12 enrollment fell by 14,939 students in fall 2025, a 1.2% drop and the second largest single-year loss in three decades, and the Weldon Cooper Center’s projections expect enrollment across the state’s 131 school divisions to decline about 3%, to 1.172 million students, by fall 2030. Migration is not the driver. Virginia births peaked at 108,416 in 2007 and have fallen in most years since, with 2024 births running 14,422 below that peak.

Aerial view of Fairfax County, Virginia neighborhoods
Fairfax County has lost population in every year since the 2020 Census, even as Virginia’s overall population grew.

Fewer new households form each year. The households that already exist move among themselves more than they used to. That changes an agent’s arithmetic from catching arrivals to holding relationships with owners who will move two, three, and four times inside Virginia over the next twenty years.

Here is where those households are concentrated. Note how many of the ten largest are independent cities rather than counties, which is a Virginia problem all its own and one worth coming back to.

LocalityPopulationPrincipal cities and communities
Fairfax County1,147,837Reston, Tysons, McLean, Annandale, Centreville
Prince William County488,880Woodbridge, Dale City, Gainesville, Haymarket
Virginia Beach (independent city)456,349Hilltop, Kempsville, Great Neck, Sandbridge
Loudoun County432,998Leesburg, Ashburn, Sterling, Purcellville
Chesterfield County377,869Midlothian, Chester, Bon Air, Chesterfield Court House
Henrico County335,744Glen Allen, Short Pump, Highland Springs, Sandston
Chesapeake (independent city)252,583Great Bridge, Western Branch, Deep Creek, Hickory
Arlington County236,254Rosslyn, Clarendon, Ballston, National Landing
Norfolk (independent city)233,596Ghent, Ocean View, Larchmont, Downtown
Richmond (independent city)229,359The Fan, Church Hill, Northside, Southside

Population figures: 2024 American Community Survey 5-Year Estimates, US Census Bureau.

Virginia’s job market is doing several things at once

Virginia’s economy does not run on one industry, and a lead-generation plan built off a single headline covers a fraction of the state. In the year to June 2026, Virginia Works recorded federal government employment down 19,000 to 170,700 and Professional and Business Services, the sector most exposed to federal contracting, down 20,500 to 788,500, with total nonfarm employment off 43,600 and unemployment at 3.7%. Those are real losses. They are also concentrated in one corner of the map.

Across the same twelve months, Education and Health Services added 4,600 jobs to reach 631,000, state government added 4,200, and local government added 13,900.

The expansions are not evenly spread either. Where they sit is where an agent should be paying attention. In July 2026 the Navy awarded $76.6 billion for nine Virginia-class and five Columbia-class submarines to General Dynamics and HII, whose Newport News Shipbuilding yard anchors the Peninsula. Those are decade-long build programs. They hire on that horizon and they hold. The Port of Virginia has been dredging its channels to the deepest depths on the US East Coast, with terminal expansion running toward 2027, and an economic impact study by the College of William & Mary’s Raymond A. Mason School of Business ties port activity to nearly 437,000 jobs and roughly 11% of total employment in the Commonwealth. Two hours up Interstate 81, the Virginia Inland Port at Front Royal in Warren County supports more than 10,000 jobs and close to $1 billion in regional investment, with a $15 million program rebuilding its rail operation and container yard.

Aerial view of the Norfolk Highlands area of Chesapeake, Virginia
Hampton Roads carries the port, the shipyards, and one of the largest concentrations of military installations in the world.

Manufacturing added its own anchors. Eli Lilly committed in 2025 to a $5 billion plant at West Creek in Goochland County with 650 permanent positions, and Merck broke ground the same year on a $3 billion expansion at Elkton in Rockingham County.

Two facts belong side by side. CNBC ranked Virginia third among America’s Top States for Business in 2026. Cardinal News reported that same summer that Virginia had ranked 48th nationally in job growth over the prior twelve months. A state can carry an excellent business climate and a slow hiring year at once, and the counties where those two facts land are rarely the same counties.

That is the practical takeaway for anyone buying leads by metro. A prospecting map drawn around federal employment misses Newport News, Front Royal, Goochland, and Elkton entirely, and it misses them in the years those places are hiring hardest.

Virginia counties go to one ez Home Search partner apiece. It takes under a minute to learn whether yours has been taken.

Most Virginia buyers are also sellers, and most agents work only one side

Two requests dominate brokerage meetings across the Commonwealth. Get me listings. Buy me buyer leads. The two halves of one person’s move get worked as two different customers in two different campaigns, and the cost of that split is most of the business.

First-time buyers account for roughly one purchase in five nationally, per NAR’s Profile of Home Buyers and Sellers. That is the national figure, named as such, because no clean Virginia series exists to stand in for it. It still sets the shape. The other four in five arrive at a closing table already holding a deed, and that deed has to move before the purchase can happen. Look at one house and you see two households, one leaving and one arriving. Follow one household through a move and you see the same people doing both jobs in sequence.
Virginia’s own numbers fit that shape. The Commonwealth’s homeownership rate stood at 69.6% in 2025, and among households aged 75 to 84 it reached 82.9%, per Virginia REALTORS. Set that owner base against the 103,722 homes sold statewide in 2025 and the arithmetic is plain. The overwhelming majority of Virginia owners did not sell that year, and did not sell the year before it. They are the pool every listing you will ever take comes out of.

What changed underneath all of it is price against pay. Between 2012 and 2024, in inflation-adjusted dollars, Virginia’s median household income rose 9% while its median home price rose 23%, and the median home moved from 3.8 times median household income to 4.3 times, according to Virginia REALTORS in March 2026. Twelve years of that gap is why a Virginia move-up decision now turns on equity rather than on income, and why the owner who has never run the equity number is the owner most likely to sit still.

Three groups sit inside that owner base. The one-in-five first-time buyer runs on affordability and education, because there is no equity behind them yet. The four-in-five majority is working two transactions off one calendar, and what they want from an agent is a read on what the current house frees up, a sequence that does not leave them carrying two mortgages, and one person holding both ends of it. Estates, landlords stepping out of a rental, and owners moving in with family make up the smallest group, and they are the only Virginia owners who genuinely sell without buying.
ez Home Search watches what a person actually does and works whichever half of the move has woken up. Somebody who runs a valuation twice in a month, opens the equity view, or keeps landing back on their own home-value page has started the selling conversation in their own head. Somebody saving listings, opening alerts the morning they land, and asking to see a house has started the buying half. The same person does both, months apart, and the platform tracks the handoff instead of guessing at it. Each of them is matched with a Single Local Expert, one vetted agent for the whole move rather than a different name on each side of it.
This is where the assessment number from the top of this article earns its keep. The automated valuation model, or AVM, behind an ez Home Search partner’s co-branded home-value page does specific work in Virginia. It corrects a figure the Commonwealth’s own study put at roughly 75 cents on the dollar at the median in tax year 2024, and the corrected number is one a Virginia owner checks unprompted, month after month, with your name sitting beside it.

One more group is sitting in plain sight. Virginia’s largest graduating class was replaced in fall 2025 by the smallest ninth grade class since 2001. Those parents are the Commonwealth’s most immediate downsizing cohort, and almost none of them have raised a hand.

Remote work in Virginia grew for four decades before anyone called it remote work

Remote work has been rising in Virginia and nationally for forty years. Headlines calling it finished are reading one year against a four-decade slope.

The Bureau of Labor Statistics published a Monthly Labor Review study in 2026 following the National Longitudinal Survey of Youth 1979 cohort across their entire working lives, the longest continuous view of telework any federal statistical agency has produced. In the 1980s, when typewriters were still common in American offices, a job permitting telework was hard to find. Adoption then climbed incrementally, decade over decade, long before 2020. After the swing between 2020 and 2022, the share of workers reporting no telework or minimal telework never returned to its pre-pandemic level, which BLS reads as a structural shift toward wider telework adoption. Census figures trace the same slope from the other side. Roughly 0.7% of the American workforce primarily worked from home in 1980, and about 3% did by 2017. It more than quadrupled before COVID-19 existed.

Virginia rode that slope harder than most states did. In the Census Bureau’s American Community Survey one-year estimates, the share of Virginia workers who primarily work from home moved from 5.76% in 2019 to 15.82% in 2024, a gain of 10.06 percentage points and one of the four largest increases recorded in the country. That ranked Virginia eighth nationally in 2024. In Arlington County the 2024 rate ran above 35%.

Employers formalized the arrangement rather than retreating from it. The SHRM 2024 Employee Benefits Survey, conducted among more than 4,500 US human resources professionals, found 63% of employers offering hybrid work as a formal benefit and 70% rating flexible work as very or extremely important, a share that has held steady since 2022.

That reshaped Virginia’s map. Between 2019 and 2022, the number of Virginians living outside Northern Virginia while working for Washington-area employers rose by nearly 24,000, roughly the headcount of the Pentagon, according to Census LEHD data analyzed by the Weldon Cooper Center. Those households bought in Frederick and Shenandoah counties, in Rockingham and Augusta, in Louisa and Goochland and New Kent, in Montgomery and Pulaski, along the Northern Neck and the Middle Peninsula, and out on the Eastern Shore. Freddie Mac’s August 2024 Outlook found that four of the ten US metro areas with the largest post-pandemic price increases sit along Interstate 81 between Bristol and Knoxville.

Streets and buildings in downtown Staunton, Virginia
Staunton’s measured growth since 2020 was revised from 0.9% to 4.2% between two rounds of Weldon Cooper Center estimates.

For an agent, that is a buying signal with a shopping list attached. These buyers walk a house looking for one room they can shut the door on, a shed or garage or accessory dwelling unit they could finish into an office, floor plans a five-day commuter never needed, and internet service that holds a video call at nine in the morning. Ask about the work setup on the first call. You will learn more about their timeline in ninety seconds than any lead score will tell you in a month.

In most of those Virginia counties, no competing agent has built the recognized local position yet.

Seven Virginia regions, seven different lead conversations

Virginia does not have a housing market. It has seven of them, and an agent who reads a statewide number as the local story will misprice both their effort and their expectations.

Northern Virginia is the region the headlines describe worst. Fairfax County has lost population in every year since the 2020 Census, and in June 2026 the Northern Virginia Association of Realtors still forecast single-family detached price growth of 1.5% to 3.5% for that year alongside growth in unit sales, on the grounds that the regional workforce leans toward contractors and private technology and defense employers rather than civilian federal payrolls. Over the same decade, Loudoun County cut its real property tax rate in all ten years from tax year 2016, when it stood at $1.145 per $100 of assessed value, to tax year 2026, when it reached $0.805. A homeowner there watched the rate fall for ten straight years while the assessment climbed. That is a conversation worth having, and most agents are not having it.

Street view in Loudoun County, Virginia
Loudoun County cut its real property tax rate in all ten years from tax year 2016 through tax year 2026.

Greater Richmond is where the growth went. New Kent, Goochland, Louisa, and Chesterfield are the four fastest-growing localities in the Commonwealth, all of them in or beside the metro. New Kent also carries the most accurate assessments in Virginia, at 98.92% of sale price in tax year 2024 against a statewide median of 75.17%, so the home-value conversation there starts from a different place than it does two counties over.

Hampton Roads rewards patience. Virginia Beach has been losing population since 2020, and that loss slowed from 6,505 to 5,462 between one round of estimates and the next, driven by births outnumbering deaths rather than by any change in who is moving. Underneath it sits the port with the deepest channels on the US East Coast and a submarine build program measured in decades. Add the PCS cycle, which puts military buyers and sellers on orders instead of on seasons, and the timing problem in this region is sharper than anywhere else in the state.

The Shenandoah Valley keeps getting revised upward. Staunton’s measured growth since 2020 moved from 0.9% to 4.2% between two rounds of Weldon Cooper Center estimates, and Waynesboro’s from 3.3% to 7.9%. Merck broke ground on a $3 billion expansion at Elkton in 2025, and the inland port at Front Royal keeps pulling warehouse and logistics work into Warren County.

Roanoke and the New River Valley turned a corner. Roanoke, Salem, Radford, and Martinsville were each listed as losing population in one round of estimates and gaining it in the next. One honest note belongs here. The Census Bureau and the Weldon Cooper Center disagree about Roanoke’s direction because they use different methods, and telling a client that plainly builds more trust than picking whichever number flatters the pitch.

Night aerial view of Roanoke, Virginia
Roanoke, Salem, Radford, and Martinsville each flipped from losing population to gaining it between two rounds of estimates.

Southwest Virginia reversed a fifty-year pattern. Net domestic migration moved from a loss of roughly 1,300 people a year through the 2010s to a gain of roughly 1,300 a year after 2020, and new business applications filed by Virginians rose 70% in the region between 2019 and 2023, second among the state’s regions.

Southside and Central Virginia turned around late and are still turning. Danville’s population had fallen since 1990, reversed, and then accelerated to 1.4% growth since 2020. Lynchburg’s measured growth was revised upward from 1.7% to 3.0% across the same two rounds of estimates.

The distance between the ends of that list is measurable. Median household income in Loudoun County runs roughly four times what it runs in Buchanan County, and the Weldon Cooper Center’s finding is that no other state carries a larger income gap between two of its own counties. One playbook will not serve both ends of that.

RegionAnchor localitiesThe trend an agent should know
Northern VirginiaFairfax, Loudoun, Prince William, Arlington, AlexandriaFairfax has lost population every year since 2020, yet NVAR forecast 1.5% to 3.5% single-family price growth for 2026
Greater RichmondChesterfield, Henrico, Hanover, New Kent, Goochland, LouisaThe state’s four fastest-growing localities sit here; Chesterfield added 36,753 people from 2020 to 2025
Hampton RoadsVirginia Beach, Chesapeake, Norfolk, Suffolk, Newport News, Hampton, York, James CityVirginia Beach’s population loss slowed on births rather than migration, alongside port and shipbuilding expansion
Shenandoah ValleyFrederick, Rockingham, Augusta, Shenandoah, Warren, Winchester, Harrisonburg, Staunton, WaynesboroStaunton’s growth since 2020 was revised from 0.9% to 4.2% and Waynesboro’s from 3.3% to 7.9%
Roanoke and New River ValleyRoanoke County, Salem, Montgomery, Pulaski, Radford, Botetourt, FranklinRoanoke, Salem, Radford, and Martinsville flipped from losing population to gaining it between estimate rounds
Southwest VirginiaWashington, Wise, Tazewell, Smyth, Wythe, Russell, Scott, Lee, BristolNet domestic migration reversed to roughly +1,300 a year after 2020, the highest in half a century
Southside and CentralDanville, Pittsylvania, Halifax, Henry, Mecklenburg, Albemarle, Charlottesville, LynchburgDanville reversed a decline running since 1990 and reached 1.4% growth since 2020

Population and migration figures: Weldon Cooper Center for Public Service, 2025 Virginia Population Estimates. Forecast figures: Northern Virginia Association of Realtors, June 2026.

What Virginia agents are already doing, and what each approach costs

Everything on the list below works. The honest problem is that each approach carries a cost the pitch leaves out, and in Virginia those costs stack in a particular order.

Referrals are the strongest asset an agent has. NAR’s research finds more buyers and sellers find their agent through a referral than through any other source. The cost is scheduling. Referrals arrive when they arrive, and an agent who has been out of a past client’s inbox for four years does not get the call when that client’s neighbor asks for a name.

Farming and community sponsorship build the recognized local name, which is exactly the right goal. They also take years and a budget, and one agent cannot cover a county of 400,000 people on foot.

Shared portal leads put a name in your CRM this week. That same name usually lands in several CRMs the same week, and the person on the other end fields calls from strangers. Legacy portals sell the name because the model earns more from the sale than from the outcome.

Your own IDX site is a real asset. It compounds, which means it pays years after you fund it, and you fund the content, the search engine work, the technical maintenance, and the data feed for every one of those years. Ask any Virginia team lead what year one cost against what year one produced.

Cold calling and dialer campaigns reach people nothing else reaches. They also drop the agent squarely inside telemarketing law. Start prospecting by phone or by text and the burden of showing consent moves onto you, not onto the person who says they never agreed. Every call or text you cannot document becomes a $500 claim, or a $1,500 claim where the violation is found willful, and Virginia agents have no statutory ceiling standing between them and that arithmetic.

Predictive-seller scoring sorts a database by who looks likeliest to list. The score is a probability attached to a stranger, and somebody still has to earn the conversation that turns a probability into a signed listing agreement.

Home-value tools send an automated estimate every month. In Virginia that thread is more useful than in most states, given how far assessments run below sale prices. One thread does not make a system.

Done-for-you content services fill an inbox. They are also one more subscription to run, disconnected from anywhere the client already spends time.

Paid search and social produce volume on demand. They stop producing the day the card stops charging.

What ez Home Search does differently has a name and a logic underneath it. The consumer side runs confidentially, which means a Virginian can search, save homes, and pull a valuation on their own house without that activity turning their name, their price range, and their phone number into inventory for businesses they never picked. People who are not being resold use the thing honestly, and they use it for years. Years of honest use is what makes the signal readable: a dormant search that wakes up, a second valuation on the same address, a saved home someone keeps returning to, a tour finally requested. And because a Virginia county carries exactly one ez Home Search partner, that person arrives at you instead of at a rotating panel of bidders.

Two honest notes belong with that. The conversion window ez Home Search sees typically runs 30 to 60 days from the first connection rather than the first week. And a partner does not reach every owner in the county on day one; the position compounds as the co-branded experience works its way through the county’s households.

On the compliance question, ezVerify.ai does the part a dialer never could. It confirms each opt-in and keeps the recording of it, so a disputed consent meets a file instead of an argument. It runs every number against a known-litigator database and checks it against Do Not Call registrations before anyone dials. That is proof and screening, and nothing else. ezVerify.ai does not score the lead, and the position does not require it to.

A Virginia county carries one ez Home Search partner and no second. Finding out whether yours is spoken for is a one-minute question.

The Virginia counties that do not show up in a lead-source pitch

Lead pricing follows population, so the counties where an exclusive position is cheapest to build and fastest to compound are the ones nobody is pitching you. Virginia has a lot of them.

Frederick County wraps around Winchester and runs north to the West Virginia line, holding Stephens City, Middletown, Gore, and Star Tannery. Next door in Rockingham sit Bridgewater, Broadway, Timberville, and Elkton, where Merck is spending $3 billion. Augusta County takes in Verona, Stuarts Draft, Fishersville, and Craigsville. Bedford stretches from the town of Bedford east to Forest, then south to Moneta and Huddleston on Smith Mountain Lake. Warrenton, Bealeton, The Plains, and Marshall are all Fauquier. Further south, Pittsylvania County runs from Chatham through Gretna, Hurt, and Blairs, while Franklin covers Rocky Mount, Boones Mill, Ferrum, and Union Hall. Abingdon, Glade Spring, Damascus, and Meadowview sit in Washington County. Louisa, among the fastest-growing counties in the Commonwealth, holds the town of Louisa plus Mineral, Trevilians, and Bumpass on Lake Anna. Out on the Eastern Shore, Accomack runs from Accomac through Onancock and Chincoteague to Parksley.

None of those is a small market to the person who lives there.

Something is shifting across several of them at once. Data center development, which began in Loudoun County, has spread into Louisa, Pittsylvania, and Wise counties among others, and Virginia’s 2026 General Assembly session was dominated by bills on where those facilities can be sited and on how the cost of new transmission and generation gets allocated among electricity customers. For an agent, that is a carrying-cost question and a land-use question, and both come up at a kitchen table long before anyone lists. A buyer weighing two counties wants to know what the monthly bill looks like and what is being built half a mile away. Most agents cannot answer either one. The agent who can is the agent who gets called back.

The county exclusivity model does not weight itself toward the big metros. It runs the same way in Fairfax County and in Accomack County, since being the first name people think of in a market of 33,000 is worth what it is worth in a market of 1.1 million, and getting there takes far less time in the smaller one.

CountyPopulationCommunities
Frederick County95,008Stephens City, Middletown, Gore, Star Tannery
Rockingham County85,600Bridgewater, Broadway, Timberville, Elkton
Bedford County80,894Bedford, Forest, Moneta, Huddleston
Augusta County78,033Verona, Stuarts Draft, Fishersville, Craigsville
Fauquier County74,577Warrenton, Bealeton, The Plains, Marshall
Pittsylvania County59,856Chatham, Gretna, Hurt, Blairs
Franklin County55,130Rocky Mount, Boones Mill, Ferrum, Union Hall
Washington County53,926Abingdon, Glade Spring, Damascus, Meadowview
Louisa County39,980Louisa, Mineral, Trevilians, Bumpass
Accomack County33,335Accomac, Onancock, Chincoteague, Parksley

Population figures: 2024 American Community Survey 5-Year Estimates, US Census Bureau.

Virginia has 95 counties and 38 independent cities, and the difference matters

Virginia is the one state where the independent city is the rule rather than the exception, and that changes what a county territory contains. The Commonwealth is divided into 95 counties and 38 independent cities, 133 localities in all. An independent city belongs to no county. It is its own county equivalent, with its own government, its own tax rate, its own assessor, and its own set of public records.

The consequences are not academic. Winchester is the county seat of Frederick County and sits outside Frederick County. Harrisonburg does the same for Rockingham, Staunton for Augusta, and the City of Fairfax for Fairfax County, which surrounds that city on every side. Falls Church is an independent city too, bordered by Fairfax County along most of its edge and by Arlington County along the rest. Manassas and Manassas Park sit inside the outline of Prince William County without belonging to it, and they border each other. Virginia Beach, Chesapeake, Norfolk, and Richmond belong to no county whatsoever, and four of the ten most populous localities in the Commonwealth are independent cities.

For an agent buying leads or drawing a farm territory, that matters twice. A vendor selling you “Frederick County, VA” is not selling you Winchester, which is a separate locality with a separate market. And an agent who works both is working two tax rates, two assessment schedules, and two sets of recorded sales.

The second point compounds. Virginia reassessment cycles run from annual to every six years, and 31 localities reassessed annually as of the Department of Taxation’s tax year 2024 study. The accuracy of the number a homeowner is holding therefore depends on which of the 133 localities they live in, and the distance between assessed value and market value is wider in some Virginia markets than in others for reasons that have nothing to do with the housing market itself.

Any county exclusivity agreement in Virginia has to be read against that map. It is the first question worth asking about a territory here, and it is a question most national lead vendors have never had to answer.

What ez Home Search builds for the partner who holds a Virginia county

The Exclusive County Partnership puts an entire Virginia county in the hands of one agent, or one team, or one brokerage, sets that partner’s brand across the consumer experience, and keeps every rival partner off the same ground. The price is a single fee a partner can put in a budget. Nothing is charged against a lead, and nothing is taken out of the commission at the closing table, which means a heavy month lands in revenue rather than on an invoice.

Why those connections convert differently is a question about how the consumer side was built. The Only Confidential Home Search is the answer. A Virginian can look at houses, keep a list, compare two neighborhoods, and check what their own place is worth, and none of it turns their name and their price range into something a stranger bought. One vetted Single Local Expert takes it from there, disclosed, so the homeowner knows who holds their information and when it went. That design carries a name at ez Home Search: A Better Way To Discover Real Estate, delivered through a confidential search. It is why the private part of a Virginia family’s decision happens here, months ahead of anything they would risk somewhere that returns one search as a run of unsolicited calls.

The biggest return waiting for a Virginia partner sits in the list they already own, ahead of anything new the partnership brings in. Ask buyers after a closing and 88% to 92% will say they would use that agent again or point a friend toward them. About 18% actually do come back when the next purchase arrives. The distance between those two numbers is revenue an agent earned once and then let go. Repeat and referral work runs near 41% of the average agent’s volume and more than half of a veteran’s. Reactivation among ez Home Search partners, whether the past client buys again or refers someone, lands near 2.5 to 5 times the market rate. Plenty of Virginia partners run past that.

Even a well-kept database erodes while nobody is looking at it. Email addresses go dead at a rate of 15% to 22% a year, and as many as one homeowner in ten changes a phone number over the same span. The co-branded search, the valuation updates, and the listing alerts keep those same people logging in, which is how ez Home Search refreshes an address and a number the moment either one changes.

The home-value page is where all of this plays hardest in Virginia. An owner who has been told by the county what their home is worth, and who can see a maintained valuation with your name beside it saying something different, has a reason to come back every month. In tax year 2024 the Commonwealth’s own study put the median Virginia assessment at roughly 75 cents on the dollar of sale price. That gap is a standing invitation to a conversation, and it renews itself on every assessment cycle.

Relocation is the other leak worth closing. About 2.1% of Americans cross a state line in a given year and roughly another 3% relocate to a different county inside the same state, per Census figures, which puts one person in twenty outside the ground a single agent covers. A Virginia REALTORS member survey published in May 2026 found 15% of responding members saying their most recent client sold in order to move out of state. National coverage is what closes that leak. The client shopping Raleigh or Tampa does it on your co-branded platform, the search reads as an early signal, and the house they are giving up in Loudoun or Chesterfield stays a listing you take rather than one you find out about later.

The conversion tools arrive built and running. The search, the listing alerts, the home-value pages, an AVM widget for the partner’s own site, an open-house page that signs visitors in from a QR code, and a cash offer for any owner weighing a fast sale against the open market are all there on day one. Nothing needs configuring and nothing needs administering. Every bit of that activity lands in the CRM a team is already using. It goes furthest in Follow Up Boss, where saved homes and search history show up on the contact record and ezNurture runs the follow-up automatically, and furthest of all in Sure Send™. BoldTrail and the rest carry whatever their integrations will support.

The position compounds on its own. NAR’s Profile of Home Buyers and Sellers finds 81% of sellers reaching out to a single agent and stopping there. Among repeat buyers, 77% interview one agent and no more. Reputation ranks first for 35% of sellers at the moment the decision gets made. Most Virginians never run a comparison at all, which makes being the county’s recognized name the whole of the contest.

Only one partner holds a Virginia county

Exclusivity is the part of this with a clock on it. Virginia has 133 counties and independent cities. Each one goes to a single ez Home Search partner, and the count of unclaimed territories drops every month. Nobody can honestly tell you every Virginia county is open.

What makes the position lasting is that a competitor cannot buy their way into it. They can outspend you on advertising in Chesterfield or Rockingham or Washington County any month they choose. They cannot take the co-branded position on the search experience that county’s own residents are already using, because it belongs to one partner, and in that county you are the partner.

The other half of it is that the position works from day one. Nobody has to build a platform, hire a developer, or sit through two quarters waiting for a content program to compound. The partner arrives on a national platform millions of people are already using and finds their own brand sitting on the search, the listing alerts, the home-value updates, and the local market reports. The engineering, the data, and the consumer demand were all in place before that partner arrived, and all of it keeps running afterward.

The footprint can also grow. As counties open, an existing partner can take on additional territory, and everything the partnership already provides extends to that new ground without anyone starting over.

What a Virginia agent decides next

Three roads lead out of the timing problem this article opened with.

Most Virginia agents are already on the first one. Buy shared leads, work them hard, and rebuild the funnel next quarter when the campaign burns out. It produces closings. It also drops to zero the month the card stops charging, and everyone you did not close goes cold and stays cold.

The second road runs through the county itself. One partner holds one territory, on a platform that was running long before that partner signed, with a co-branded position no competitor inside the county can buy.

The third road is to build the whole thing in-house. You would need a confidential search experience, a valuation model accurate enough to correct a county assessment, listing data that refreshes fast enough to matter, alert infrastructure, a content program people actually open, and a consent and screening layer that survives a dispute. That is a multi-million-dollar engineering and data problem long before it becomes a marketing problem, and sourcing the data is on its own beyond what almost any Virginia team or brokerage can reach. Plenty of teams try. Most of them wind up operating the stack instead of operating the business.

The second road has an honest cost, and it belongs on the table before anyone picks it. A county exclusivity partnership is a position you hold and work. It does not produce closings in week one. The conversion window ez Home Search sees typically runs 30 to 60 days from the first connection, and database reactivation compounds across quarters rather than across days. If you need business by Friday, buy leads. If you want the county in three years, this is the move.

One number in this article carries more weight than the rest. An ez Home Search partner watches old clients circle back, buying a second home or handing over a name, at a pace running 2.5 to 5 times the market rate. Nobody in that group had to be found, because every one of them already knows the name and already said they would use it again.

The assessment notice sitting in your future client’s kitchen drawer says one thing. In tax year 2024 the Commonwealth’s own study put that number at roughly 75 cents on the dollar. Someone is going to tell that Virginia homeowner what their house is worth, and the only question worth your attention is whether it is you or a stranger.

Find out whether your Virginia county is still open.

Frequently asked questions

Virginia has 38 independent cities that are not part of any county. How does that change a county-based territory?

It changes what you are buying. An independent city is its own county equivalent in Virginia, so a territory drawn on a county line stops at that line. Frederick County does not include Winchester. Rockingham does not include Harrisonburg. Augusta does not include Staunton or Waynesboro. Fairfax County does not include the City of Fairfax or Falls Church.

For an ez Home Search partner, that is a question to settle at the start rather than discover later. It also cuts in your favor. An independent city is a territory in its own right, and in several Virginia markets the city and the county around it are two distinct opportunities with different price points, different tax rates, and different assessment schedules. A partner who understands the split can hold the piece that fits their business instead of paying for a map that does not match the market.

Federal employment in Virginia fell by 19,000 jobs in the year to June 2026. Is Northern Virginia still worth a lead-generation budget?

Yes, and the housing data is the reason. Virginia Works recorded that decline in federal government employment, and in June of that same year the Northern Virginia Association of Realtors forecast single-family detached price growth of 1.5% to 3.5% alongside growth in unit sales. Its reasoning was that the regional workforce leans toward contractors and private technology and defense employers rather than civilian federal payrolls, and that the region’s for-sale inventory, which counts homes on the market at a moment rather than homes that change hands over a year, loosens slowly.

What shifts in a period like that is who is moving and when. Employment disruption produces relocations, downsizes, and dual-income households rethinking a mortgage, and those decisions get made privately across months. An agent visible only at the raised-hand moment sees none of it. By the time that household acts, the advantage already sits with whichever agent they had come to trust.

New Kent, Goochland, Louisa, and Chesterfield are Virginia’s fastest-growing counties. Are those buyers coming from out of state?

Mostly not. All four sit in or beside the Richmond metro, and Virginia’s growth pattern since 2020 has been internal movement out of expensive metropolitan cores and into the counties next door. Statewide, the interstate flows were close to a wash in 2024, with roughly 265,500 people arriving from elsewhere in the country and nearly 264,000 leaving.

That shapes how you prospect. A buyer arriving from another state knows no agent at all. A buyer moving from Henrico to Goochland already knows one, or is one conversation away from being reminded of one. Competition in Virginia’s fastest-growing counties is a relationship competition, and it begins well before the search does.

Virginia Beach has lost population since 2020. Does that mean fewer listings there?

No. The Weldon Cooper Center’s estimates revised Virginia Beach’s loss since 2020 from 6,505 down to 5,462 between two rounds, and the improvement came from births outnumbering deaths rather than from any change in who is moving.

People moving out of Virginia Beach are people listing homes in Virginia Beach. Net out-migration is a listing-supply story first, and it comes paired with relocation business: the client leaving still owns a house in your market, and the referral into their new market is yours if you see the move coming. What loses both is hearing about it after the listing is signed. Hampton Roads adds its own timing layer, because PCS orders put military buyers and sellers on a schedule that has nothing to do with the selling season.

Virginia property tax rates run from $0.33 per $100 in Lunenburg County to $1.405 in Manassas Park. How does that spread show up in a lead conversation?

It shows up in what a buyer can afford and in what a seller can get. Property taxes are carried monthly on top of the mortgage and the insurance, so a wide rate spread between two neighboring Virginia localities changes the payment on an identical price, and the market corrects for that in what the house eventually sells for. A seller in a high-rate locality is competing against that arithmetic whether anyone names it or not.

The assessment gap is the other half. In tax year 2024 the Virginia Department of Taxation put the statewide median assessment at 75.17% of sale price, with only eight of 95 counties and six of 38 cities inside the range assessors treat as acceptable. An agent who can explain both the rate and the assessment gap for a specific Virginia locality is having a conversation almost no one else in that market is having.

Southwest Virginia is attracting more new residents than it has in fifty years. Which counties there justify a lead-generation spend?

Start where people are choosing to go. Look at Washington County around Abingdon, Montgomery and Pulaski in the New River Valley, Wythe and Smyth along the Interstate 81 corridor, and Wise County, where new investment has been announced. The regional shift is documented rather than anecdotal. Net domestic migration reversed from a loss of roughly 1,300 people a year through the 2010s to a gain of roughly 1,300 a year after 2020, with only two counties in the region still losing more people than they gained. New business applications filed by Virginians rose 70% across the region between 2019 and 2023.

The case for spending there is competitive as much as demographic. These are markets where no competitor has locked up the recognized local name, where lead costs have not been bid to metro levels, and where one partner holding the county can become the default answer in a couple of years rather than a decade.